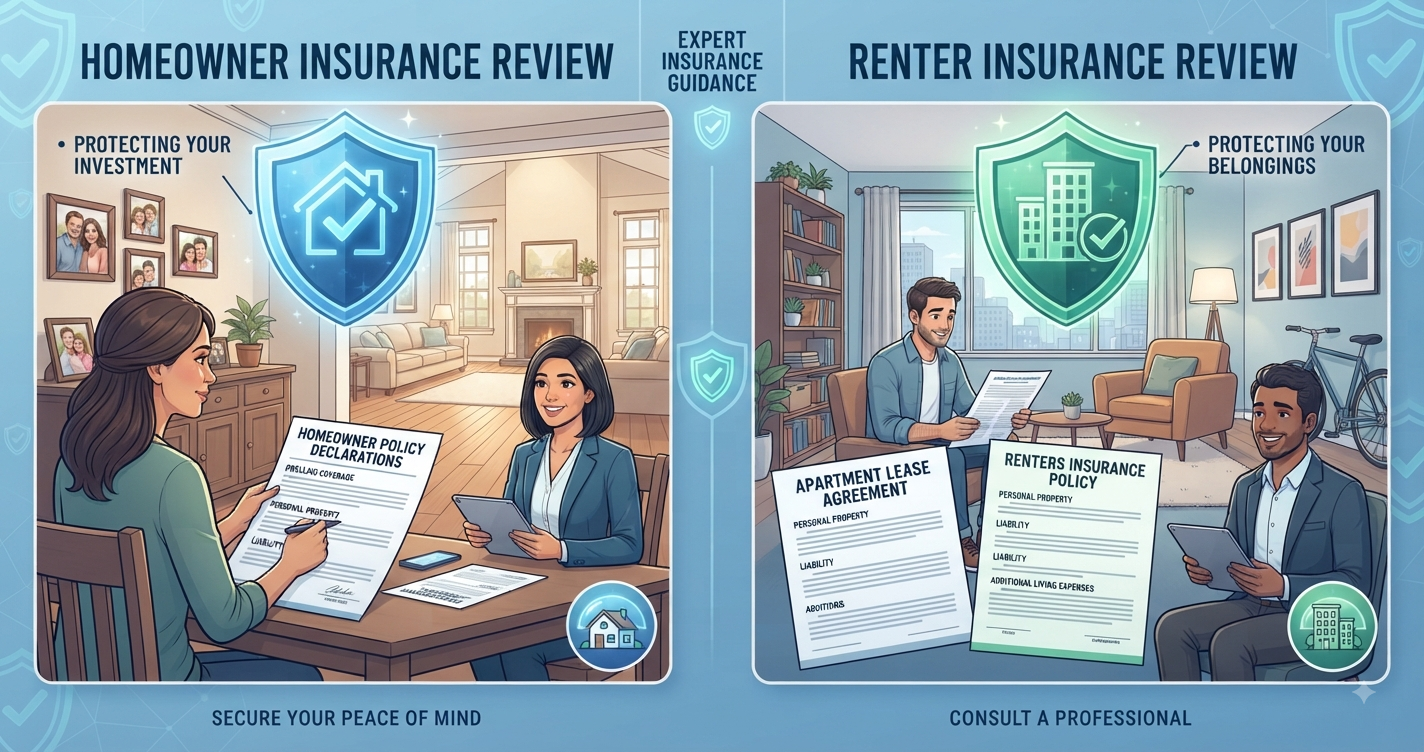
Your home is likely the most valuable asset you own. Yet many people protect it with inadequate or nonexistent insurance.
Consider these scenarios:
Scenario 1: House fire
Your $400,000 home burns down. Replacement cost: $450,000 (inflation, upgraded materials). Your insurance coverage: $250,000. Your personal responsibility: $200,000 (paid from personal assets or bankruptcy).
Scenario 2: Apartment theft
Burglary while you’re at work. $15,000 in electronics, furniture, and clothing stolen. Your coverage: $0 (no renters insurance). Your personal responsibility: $15,000 (paid from savings or credit cards).
Scenario 3: Liability lawsuit
Guest slips on icy steps and breaks leg. Medical bills: $50,000. Lawsuit damages: $100,000. Your liability insurance limit: $50,000. Your personal responsibility: $50,000 out-of-pocket.
These aren’t hypothetical. They happen constantly—and without proper insurance, they’re financially catastrophic.
Yet homeowners and renters insurance is surprisingly affordable:
- Homeowners: $800-$1,500/year
- Renters: $150-$200/year
In this comprehensive guide, you’ll understand what homeowners and renters insurance actually covers, how to calculate adequate coverage, how to find the best rates, and exactly what to do if disaster strikes.
Whether you own or rent, proper property insurance is essential protection.
Let’s ensure your home and possessions are protected.
Understanding Property Insurance: The Basics
Before diving into specifics, let’s understand what property insurance does.
The Purpose of Property Insurance
Property insurance protects you from financial loss due to:
- Damage to property: Fire, weather, theft, vandalism
- Liability: If someone is injured on your property
It’s not flood or earthquake insurance (separate policies). It’s not paying for normal maintenance. It’s specifically protecting against unexpected property damage and liability.
Who Needs Property Insurance
Homeowners with mortgage: Required by lender (non-negotiable)
Homeowners without mortgage: Not required by law, but essential protection
Renters: Not required by law, but essential protection (landlord’s insurance doesn’t cover your stuff)
Landlords with rental properties: Required by mortgage lender and essential
How Property Insurance Works
When damage occurs:
- You experience loss (fire, theft, weather damage)
- You contact insurance company to file claim
- Insurance company assigns adjuster
- Adjuster investigates and assesses damage
- Insurance company pays claim (minus deductible)
- You use proceeds to repair/replace
Important: Insurance pays for actual damage/loss, not profit.
Example:
- Your TV purchased for $1,000 five years ago
- Current value: $300 (depreciation)
- Insurance pays: $300 (actual cash value)
- Insurance does NOT pay: Original $1,000 cost
Homeowners Insurance: Complete Coverage Guide
Homeowners insurance protects your home and belongings, plus provides liability coverage.
What Homeowners Insurance Covers
Homeowners insurance has multiple coverage components:
Coverage A: Dwelling (Structure)
What it covers:
- Home structure (walls, roof, foundation)
- Attached structures (garage, deck, shed)
- Permanent fixtures (built-in appliances, fixtures)
- Cost to rebuild your home
What it doesn’t cover:
- Land (insurance covers structure, not the ground)
- Yard/landscaping (sometimes partial coverage)
- Personal property (covered under separate coverage)
- Detached structures over certain value
How much to buy:
Critical: Buy enough to FULLY rebuild your home.
Calculation:
Rebuilding cost per square foot: $150-$250 (varies by location and quality)
Home size: 2,000 square feet
Rebuild cost: 2,000 × $150-$250 = $300,000-$500,000
Common mistake: Insuring for original purchase price instead of rebuild cost.
Example:
- Bought house for $300,000 in 2005
- Today’s rebuild cost: $500,000
- Insuring for $300,000: Underinsured by $200,000
Action: Get formal replacement cost estimate from insurance company or appraiser.
Coverage options:
Actual Cash Value (ACV):
- What it pays: Replacement cost minus depreciation
- Example: $50,000 roof damage, roof is 15 years old (50% life remaining)
- Pays: $25,000 (50% of replacement cost)
- Cost: Cheaper premium
- Problem: Gap between what insurance pays and actual repair cost
Replacement Cost (RC):
- What it pays: Full replacement cost, no depreciation deduction
- Example: $50,000 roof damage, roof is 15 years old
- Pays: Full $50,000 (no depreciation deduction)
- Cost: Higher premium ($100-200/year more)
- Recommended: Almost always worth the cost
Guaranteed/Extended Replacement Cost:
- What it pays: Up to 120-150% of dwelling limit
- Example: Dwelling limit $400,000, pays up to $480,000-$600,000
- Cost: Slightly higher premium
- Best for: Inflation protection
Recommendation: Buy replacement cost coverage, not actual cash value.
Coverage B: Other Structures
What it covers:
- Detached garage
- Shed
- Pool house
- Guest house
- Fence (sometimes)
Coverage amount:
- Usually 10-20% of dwelling coverage
- Example: $400,000 dwelling = $40,000-$80,000 other structures
When it matters:
- Valuable detached structures
- Expensive pool houses or guest houses
- Consider increasing limit if structures valuable
Coverage C: Personal Property (Contents)
What it covers:
- Furniture
- Electronics (TV, computer, stereo)
- Clothing
- Appliances
- Jewelry
- Art
- Sports equipment
How much it covers:
- Usually 50-75% of dwelling coverage
- Example: $400,000 dwelling = $200,000-$300,000 contents
Valuation options:
Actual Cash Value:
- Pays based on current market value (with depreciation)
- Example: 5-year-old couch bought for $2,000, now worth $500, insurance pays $500
- Cheaper premium
Replacement Cost:
- Pays what it costs to buy new item
- Example: Same couch costs $2,000 new, insurance pays $2,000 (if limit allows)
- Higher premium ($100-200/year more)
- Recommended: Better coverage
Important limits:
Some items have sub-limits (maximum payout):
- Jewelry: Often $1,500-$5,000 limit
- Electronics: Sometimes $2,500-$5,000
- Art/collectibles: Often limited
- Cash: Usually $200-$500
Solution for high-value items: Schedule them separately (floater policy).
Calculate how much you need:
- Walk through home, list all possessions
- Estimate replacement cost for each category
- Total the amounts
- Buy dwelling × 50-75% at minimum
- Consider higher limit if you have valuable items
Example:
- Furniture: $10,000
- Electronics: $8,000
- Clothing: $4,000
- Kitchen items: $3,000
- Bedroom items: $4,000
- Living room items: $5,000
- Miscellaneous: $6,000
- Total: $40,000
If dwelling is $400,000, should have $200,000+ contents coverage.
Coverage D: Loss of Use (Additional Living Expenses)
What it covers:
- Temporary housing if home becomes uninhabitable
- Meals and food
- Transportation
- Other living expenses during repairs
How it works:
Home damaged by fire, uninhabitable for 3 months:
- Monthly living expenses increased by: $2,000 (temporary housing adds to normal expenses)
- 3 months × $2,000 = $6,000
- Insurance covers: Full $6,000
Coverage amount:
- Usually 20-30% of dwelling coverage
- Example: $400,000 dwelling = $80,000-$120,000 loss of use
Recommendation: Accept whatever limit insurance offers (rarely a limiting factor).
Coverage E: Liability Protection
What it covers:
- If someone injured on your property
- Legal defense (your attorney paid by insurance)
- Medical bills for injured person
- Damages if sued
How it works:
Guest slips on icy steps, breaks leg:
- Medical bills: $50,000
- Ongoing care: $20,000
- Pain and suffering damages: $30,000
- Total claim: $100,000
If liability limit is $300,000:
- Insurance pays: Full $100,000
- Your responsibility: $0
If liability limit is $50,000:
- Insurance pays: $50,000
- Your responsibility: $50,000
Coverage amounts:
- Typical offered: $100,000-$300,000
- Recommended: $300,000-$500,000
- High-risk properties (pool, trampoline): $500,000+
When to increase:
- You have pool or trampoline
- You have pets (liability risk)
- Frequent guests
- High net worth (more attractive lawsuit target)
Cost: Increasing from $100,000 to $300,000 usually costs only $10-20/year.
Recommendation: Buy at least $300,000 (cheap upgrade with significant protection increase).
Coverage F: Medical Payments
What it covers:
- Medical bills for anyone injured on your property (regardless of fault)
- Automatic coverage, no lawsuit needed
How it works:
Neighbor slips on your driveway (no negligence on your part), breaks arm:
- Medical bills: $5,000
- No lawsuit needed
- Medical payments covers: Full $5,000
Coverage amounts:
- Usually $1,000-$5,000
- Default is often sufficient for most situations
When to increase:
- Frequent guests
- High injury risk environment (pool, sports activities)
- Rarely necessary to increase
What Homeowners Insurance Doesn’t Cover
Water damage from floods: Excluded (requires separate flood insurance)
Earthquake damage: Excluded (requires separate earthquake insurance)
Routine maintenance: Not insurance claim (normal wear and tear)
Intentional damage: Not covered (if you intentionally cause damage)
Neglect: Not covered (damage from lack of maintenance)
Business use: Not covered (operating business from home usually excluded)
Certain weather: Some policies exclude wind/hail damage (especially in high-risk areas)
Important: Know what’s NOT covered in your policy.
Homeowners Insurance Costs
Typical annual premiums:
- Basic homeowners: $800-$1,200/year
- Average home value $350,000: $1,000-$1,500/year
- High-risk area: $1,500-$3,000+/year
What affects cost:
- Home value: Higher value = higher premium
- Age of home: Older = higher cost (roof age critical)
- Location: High-crime areas cost more
- Weather risk: Areas with hurricanes, tornadoes cost more
- Deductible: Higher deductible = lower premium
- Construction type: Wood frame more expensive than brick
- Distance to fire station: Rural homes cost more
- Claims history: Previous claims increase rates
- Credit score: Better credit = lower rates
- Safety features: Alarm systems, fire extinguishers reduce cost
Deductible options and cost impact:
$500 deductible: Base premium
$1,000 deductible: 10-15% savings ($100-150/year)
$2,500 deductible: 25-30% savings ($250-350/year)
$5,000 deductible: 40-50% savings ($400-600/year)
Sweet spot: $1,000 deductible (balances reasonable savings with manageable out-of-pocket).
Example cost breakdown (mid-sized home, good credit, no claims):
- Dwelling: $400,000 = $900/year
- Contents: $200,000 = $100/year
- Liability: $300,000 = $50/year
- Loss of use: $100,000 = $30/year
- Medical payments: $5,000 = $20/year
- Total: ~$1,100/year ($92/month)
Homeowners Insurance Discounts
Bundle discount: Home + auto = 10-25% savings
New construction: 5-10% discount
Updated roof: 5-10% discount (newer roof = less weather risk)
Updated electrical/plumbing: 5-10% discount
Alarm system: 5-10% discount
Fire extinguisher: 2-5% discount
Security system: 5-15% discount
Good credit: 5-15% discount
No claims: Maintained 3+ years = 5-10% discount
Loyalty discount: Customer 3+ years = 5-10% discount
Paid-in-full: Annual payment vs monthly = 2-5% discount
Multiple discounts: Can stack significantly (often 20-40% total)
Action: After enrolling, contact insurance to ensure all discounts applied.
Renters Insurance: Protection for Apartment Dwellers
Renters insurance protects your possessions and provides liability coverage. Critical for renters, yet most don’t have it.
What Renters Insurance Covers
Coverage A: Personal Property (Contents)
What it covers:
- All your possessions in rental unit
- Furniture
- Electronics
- Clothing
- Kitchen items
- Bedroom items
- Everything you own in apartment
What it doesn’t cover:
- Landlord’s property (walls, appliances, fixtures)
- Vehicles (covered under auto insurance)
- High-value items (unless scheduled separately)
Coverage amount:
- Typical: $20,000-$50,000
- Calculate what you own (see homeowners section)
- Most people need $25,000-$40,000
Valuation:
- Actual cash value (depreciated value): Cheaper
- Replacement cost (new item cost): Better, slightly more expensive
Recommendation: Replacement cost is worth small premium increase.
Sub-limits (maximums for specific items):
- Jewelry: Often $2,500 limit
- Electronics: Often $2,500 limit
- Valuable items: May be limited
Solution: Schedule valuable items separately for full coverage.
Coverage B: Liability Protection
What it covers:
- If someone injured in your apartment
- Legal defense
- Damages if sued
How it works:
Friend visits, slips on your wet floor, breaks arm:
- Medical bills: $15,000
- Damages: $25,000
- Total: $40,000
If liability limit is $300,000:
- Insurance pays: Full $40,000
- Your responsibility: $0
If liability limit is $50,000:
- Insurance pays: $50,000
- Your responsibility: $0 (stays within limit)
Coverage amounts:
- Typical offered: $100,000-$300,000
- Recommended: $300,000 (same as homeowners)
- Cost difference minimal ($10-15/year between $100k and $300k)
When to increase:
- Frequent visitors
- High injury risk activities
- Generally, $300,000 is standard and sufficient
Coverage C: Medical Payments
What it covers:
- Medical bills for anyone injured in your apartment
- No lawsuit needed
- Covers regardless of your fault
Coverage amount:
- Usually $1,000-$5,000
- $1,000 typically sufficient
Rarely necessary to increase.
Coverage D: Loss of Use (Additional Living Expenses)
What it covers:
- Temporary housing if apartment becomes uninhabitable
- Meals
- Other living expenses
How it works:
Apartment damaged by fire, uninhabitable for 1 month:
- Temporary housing: $1,500/month additional cost
- Insurance covers: Full $1,500
- 1 month = $1,500 total covered
Coverage amount:
- Usually adequate at default amounts
- Rarely limiting factor
What Renters Insurance Doesn’t Cover
Landlord’s responsibility: Insurance only covers your stuff, not building damage
Flood damage: Requires separate flood insurance
Roommate damage: Damage caused by roommate intentionally usually not covered
Maintenance issues: Normal wear and tear not covered
Business use: Operating business from apartment usually excluded
Renters Insurance Costs
Typical annual cost: $150-$300/year ($12-25/month)
Extremely affordable considering coverage provided.
What affects cost:
- Coverage amount: Higher coverage = higher cost
- Location: High-crime areas cost more
- Building safety: Buildings with better security, fire suppression = lower cost
- Claims history: Previous claims increase rates
- Credit score: Better credit = lower rates
- Deductible: Higher deductible = lower cost
Deductible impact:
$250 deductible: Base premium ($200/year example)
$500 deductible: 10% savings ($180/year)
$1,000 deductible: 20% savings ($160/year)
Sweet spot: $500 deductible (balances savings with manageable out-of-pocket).
Why renters insurance is cheap:
Insurance companies pay less frequent claims (theft, fire rare in apartments). Risk lower than homeowners = cheaper insurance.
Example cost breakdown:
- Personal property ($30,000): $100/year
- Liability ($300,000): $40/year
- Medical payments ($1,000): $10/year
- Loss of use ($10,000): $10/year
- Total: ~$160/year ($13/month)
Renters Insurance Discounts
Bundle discount: Renters + auto = 10-20% savings
Good credit: 5-10% discount
No claims: 3+ years = 5-10% discount
Loyalty discount: Customer 3+ years = 5-10% discount
Paid-in-full: Annual payment vs monthly = 2-5% discount
Safety features: Fire extinguisher, alarm system = 5-10% discount
Multi-policy: Multiple policies with same insurer = 10-25% discount
Discounts stack: Can achieve 20-40% total discount.
Why Renters Don’t Buy It (And Why They Should)
Common reasons renters skip coverage:
- “It’s expensive” (Actually $13/month—less than one coffee)
- “My landlord’s insurance covers my stuff” (No, landlord’s covers building only)
- “I don’t have much stuff” (Even basic possessions worth $15,000+)
- “I’m never home” (Theft/fire can happen anytime)
- “It won’t happen to me” (Burglary affects 1 in 36 households annually)
Reality check:
Average apartment contents value: $25,000
Cost to replace without insurance: $25,000
Cost of renters insurance: $160/year
Payoff from single theft or fire: Enormous
The math is irrefutable: Renters insurance is the best financial bargain available.
Comparing Homeowners and Renters Insurance
Key Similarities
| Feature | Homeowners | Renters |
|---|---|---|
| Personal property coverage | Yes | Yes |
| Liability protection | Yes | Yes |
| Medical payments | Yes | Yes |
| Additional living expenses | Yes | Yes |
| Deductible options | Yes | Yes |
| Discount opportunities | Yes | Yes |
| Can add riders | Yes | Yes |
Key Differences
| Feature | Homeowners | Renters |
|---|---|---|
| Dwelling/structure | Yes (covers home) | No (landlord’s responsibility) |
| Contents | $200,000-$500,000 typical | $20,000-$50,000 typical |
| Annual cost | $800-$1,500 | $150-$300 |
| Required by lender | Yes (if mortgage) | Usually no |
| Deductible typical | $500-$1,000 | $250-$500 |
| Coverage scope | Home + belongings | Belongings only |
How to Get Homeowners or Renters Insurance
Step 1: Determine Coverage Needed
For homeowners:
- Get replacement cost estimate for home
- Walk through home, estimate contents value
- Determine liability limit needed ($300,000 minimum recommended)
- Note special features (pool, trampoline, valuable items)
For renters:
- Walk through apartment, list contents
- Estimate total value (usually $25,000-$40,000)
- Choose liability limit ($300,000 recommended)
- Note high-value items needing separate schedule
Step 2: Get Quotes from Multiple Companies
Online quote tools:
- InsWeb
- The Zebra
- Insurify
- Direct company websites (State Farm, Progressive, Allstate, Geico, etc.)
In-person quotes:
- Local independent insurance agents
- Company-specific agents
Get quotes from 5-7 companies (rates vary 20-40%).
Step 3: Compare Quotes
Key metrics to compare:
- Premium amount (annual and monthly)
- Deductible options available
- Coverage amounts (dwelling, liability, contents)
- Discounts available
- Replacement cost vs actual cash value
- Additional riders/endorsements
Use comparison spreadsheet:
| Company | Premium | Deductible | Dwelling | Contents | Liability | Discounts |
|---|---|---|---|---|---|---|
| Company A | $950 | $1,000 | $400k | $200k | $300k | 25% |
| Company B | $1,050 | $500 | $400k | $200k | $300k | 20% |
| Company C | $900 | $1,000 | $400k | $200k | $300k | 30% |
Step 4: Review Coverage Details
Before purchasing, verify:
- Deductible amount (check you understand what you’ll pay)
- Coverage limits adequate
- Replacement cost (not actual cash value) for dwelling and contents
- Liability limit at least $300,000
- Special coverage for high-value items if needed
- Discounts properly applied
- Company reputation (good customer service rating)
Step 5: Purchase and Set Up
Finalize purchase:
- Choose company with best value (not necessarily cheapest)
- Complete application
- Arrange payment (monthly or annual)
- Set up automatic payments
After purchase:
- Download policy documents
- Save in safe place (physical and digital)
- Create inventory with photos/video
- Document all coverage details
- Update beneficiaries if applicable
- Note renewal date (annual review reminder)
Step 6: Annual Review
Every year during renewal:
- Review coverage limits (adequate?)
- Check if new discounts available
- Verify all discounts still applied
- Compare quotes from competitors
- Switch if better deal found (1-3 hour investment for $100-200 savings)
What to Do When Disaster Strikes: Filing Claims
Understanding the claims process helps you get paid faster and more completely.
Step 1: Document the Damage (Before Repairs)
Critical: Do NOT repair damage before insurance adjuster sees it.
What to do:
- Take photos/video of all damage
- Document everything visible
- Note any damaged items (furniture, electronics, clothing)
- Don’t move items (may need to verify condition)
- List any items lost to theft/fire
Example:
- Fire damage: Photograph walls, ceilings, damaged furniture
- Theft: Photograph broken lock, areas where items were
- Water damage: Photograph affected areas, stains, damage progression
Step 2: Contact Insurance Company
Call your agent or company claim line:
- Report claim with date and time damage occurred
- Describe what happened
- Request claim number
- Ask about claims process timeline
- Get claim adjuster contact information
Important: Report promptly. Most policies have time limits (usually 30-60 days).
Step 3: Meet with Claims Adjuster
Adjuster will:
- Inspect property and damage
- Document findings with photos
- Ask detailed questions about what happened
- Request documentation (receipts, warranties, etc.)
- Assess repair/replacement costs
- Determine coverage and deductible
What to prepare:
- Original receipts (if you have them, though not always required)
- Warranty information
- List of damaged items with descriptions
- Photos you took documenting damage
- Any documentation of pre-loss condition (home inspection, appraisal, etc.)
What to say:
- Be honest and thorough
- Describe exactly what happened
- Provide all requested information
- Ask questions if you don’t understand something
- Don’t agree to settlement immediately if uncomfortable
Step 4: Provide Documentation
Adjuster requests:
- Original receipts for items (if available)
- Bank/credit card statements showing purchases
- Warranties
- Serial numbers
- Photos of items before damage
- Repair estimates
If you don’t have receipts:
- You can still be covered (insurance knows most people don’t keep receipts)
- Provide descriptions of items and approximate purchase price/time
- Insurance can research typical prices
- Estimated depreciation applied
Step 5: Settlement
Insurance company offers settlement:
- Initial offer includes:
- Payment for covered loss
- Minus deductible
- Minus depreciation (if ACV policy; not if replacement cost)
Options:
- Accept settlement and sign release
- Negotiate if amount seems too low
- Request itemized breakdown if unclear
- Request appraisal if significant disagreement about value
Typical timeline: 30-60 days from claim filing to settlement.
Step 6: Repairs and Replacement
Use settlement funds for:
- Home repairs
- Item replacement
- Temporary housing (if covered)
Important: Insurance doesn’t require you to use specific contractors. Choose your own. Get multiple repair quotes if needed.
Common Homeowners and Renters Insurance Mistakes to Avoid
Mistake 1: Underinsuring Home Value
Error: Insuring $250,000 home for $300,000 thinking it’s adequate
Reality: Rebuild cost often exceeds purchase price. Old $300k house might cost $450k to rebuild today.
Solution: Get formal replacement cost estimate. Update coverage regularly (home values change).
Mistake 2: Choosing Actual Cash Value Instead of Replacement Cost
Error: Saving $100-150/year by choosing ACV
Reality: When damage occurs, depreciation reduces payout significantly.
Example:
- 10-year-old roof costs $12,000 to replace
- ACV policy pays: $6,000 (50% depreciated)
- You pay: $6,000 out-of-pocket
- Replacement cost policy pays: Full $12,000
Solution: Buy replacement cost. Small premium increase provides huge protection.
Mistake 3: Not Documenting Possessions
Error: Relying on memory to list what you own if there’s a loss
Reality: When disaster occurs, you’re stressed and forget items. Insurance can’t cover items you didn’t mention.
Solution: Create home inventory NOW:
- Walk through every room
- List furniture, electronics, appliances
- Take photos/video
- Store list somewhere safe (cloud storage, email to yourself)
- Update annually
Value of inventory: Claims settle 10-20% faster and 15-25% higher with documentation.
Mistake 4: Buying Minimum Liability Coverage
Error: Accepting $50,000-$100,000 liability limit
Reality: One serious injury lawsuit easily exceeds $100,000.
Example:
- Permanent injury: $500,000+ damages
- Your limit: $100,000
- Your responsibility: $400,000 out-of-pocket
Solution: Buy $300,000+ liability (costs only $10-20/year more than $100k).
Mistake 5: Skipping Renters Insurance
Error: Assuming you don’t have valuable possessions needing insurance
Reality: Average apartment has $20,000-$30,000 in possessions. Theft/fire can happen anytime.
Solution: Buy renters insurance ($160/year is cheapest insurance bargain available).
Mistake 6: Not Comparing Quotes Annually
Error: Keeping same policy year after year
Reality: Rates change. Better deals available. Competitor often cheaper.
Solution: Every 2-3 years, get 3-5 quotes. Switch if better deal found.
Typical savings: $200-400/year switching to cheaper competitor.
Mistake 7: Not Using Available Discounts
Error: Not claiming all eligible discounts
Reality: Discounts can save 20-40% total.
Common missed discounts:
- Bundle discount (not bundling home + auto)
- Safety features (alarm system, fire extinguisher)
- Updated roof
- Good credit
- Paid-in-full (annual vs monthly)
Solution: After purchasing, call agent and ask: “What discounts am I missing?”
Mistake 8: High-Value Items Without Special Coverage
Error: Assuming jewelry, art, electronics fully covered
Reality: Policy sub-limits (maximum payouts) often too low.
Example:
- You own $10,000 diamond ring
- Jewelry sub-limit: $2,500
- Insurance pays: Only $2,500
- You lose: $7,500
Solution: Schedule valuable items separately on floater policy (small additional cost).
Mistake 9: Unclear Coverage Gaps
Error: Not knowing what ISN’T covered
Common exclusions:
- Flood damage (need separate flood insurance)
- Earthquake damage (need separate earthquake insurance)
- Maintenance/neglect (damage from poor upkeep)
- Intentional damage
Solution: Read your policy. Understand exclusions. Buy separate policies for excluded risks if relevant.
Mistake 10: Not Updating Coverage When Home Improvements Increase Value
Error: Buying $500k coverage when home now worth $600k
Reality: Coverage becomes inadequate as home value increases.
Solution: Update coverage annually. After major improvements, reassess and increase limits.
Special Coverage: Floods and Earthquakes
Standard homeowners insurance doesn’t cover floods or earthquakes. If you’re in high-risk areas, separate policies essential.
Flood Insurance
Why separate policy required:
Floods are excluded from standard homeowners insurance because:
- Extremely expensive to insure
- Risk concentrated in specific areas
- Standard insurers can’t profitably offer it
Who needs flood insurance:
- Located in flood zone (check FEMA flood map: msc.fema.gov)
- History of flooding in area
- Property near river, stream, or low elevation
- Required if mortgage lender in designated flood zone
How much coverage:
- Dwelling: Up to $250,000
- Contents: Up to $100,000
Cost:
- Low-risk area: $300-500/year
- Moderate-risk area: $500-1,000/year
- High-risk area: $1,000-3,000+/year
How to buy:
Contact insurance agent for National Flood Insurance Program (NFIP) policy or private flood insurance options.
Earthquake Insurance
Why separate policy required:
Earthquakes excluded from standard homeowners insurance because:
- Rare but extremely expensive when they occur
- Concentration of risk in specific areas
- Standard insurers can’t profitably offer it
Who needs earthquake insurance:
- California, Oregon, Washington, Alaska, Hawaii (highest risk)
- Any area with seismic activity
- Older home in seismic area (higher damage risk)
How much coverage:
- Dwelling: Up to full home value
- Contents: 15-25% of dwelling coverage typical
Cost:
- Low-risk area: $200-400/year
- Moderate-risk area: $400-800/year
- High-risk area: $800-2,000+/year
Deductible:
- Often 10-20% of coverage amount (higher than standard)
- Example: $400,000 coverage = $40,000-$80,000 deductible
How to buy:
Contact insurance agent. Earthquake insurance available through private carriers or California Earthquake Authority (if California resident).
Frequently Asked Questions About Property Insurance
If I have a mortgage, can I drop homeowners insurance?
Legally: Yes, no law requires it
Practically: No, lender requires it as mortgage condition
Reality: If you drop it, lender will buy force-placed insurance (much more expensive, less comprehensive)
Bottom line: You’ll have it whether you choose to or not. Buy it directly for better rates and coverage.
What if I’m a renter and my landlord requires me to have renters insurance?
Some landlords require renters insurance as part of lease.
It’s actually good news: Forces you to have important protection.
Cost: Only $150-300/year, reasonable requirement.
Where to buy: Same places as renters shopping independently (insurers, agents, online).
Can I get a discount if I bundle homeowners and auto insurance?
Yes, significant discount:
- Typical bundle discount: 10-25%
- Savings example: $1,100 homeowners + $1,200 auto = $2,300
- With 20% bundle discount: $1,840
- Savings: $460/year
It’s worth bundling even if one insurer is slightly more expensive on individual policy (discount often outweighs higher base rate).
How often should I review my homeowners/renters insurance?
Minimum: Annually (policy renewal)
Better: Every time you:
- Make significant home improvement
- Buy valuable items (jewelry, electronics, art)
- Move (new property, new area)
- Change life situation (marriage, children, business)
- Experience claim (adjust coverage based on experience)
Shop for better rates: Every 2-3 years, get quotes from competitors.
If I experience a claim, will my rates increase?
Usually yes, depending on:
At-fault claims (you caused damage):
- Likely to increase rates 10-25%
- Increase lasts 3-5 years
- Rate increase varies by insurer
Not-at-fault claims (weather, theft):
- Less likely to increase rates
- If increased, smaller amount (5-10%)
- Some insurers don’t increase for weather
No claims: After 3-5 years, you become eligible for loyalty discount.
What documents should I keep safe?
Essential to save:
- Original homeowners/renters policy
- Coverage details (limits, deductible, policy numbers)
- Recent appraisal or home inspection
- Home improvement receipts
- Expensive item receipts
- Photos of home and contents
- List of valuable items
- Insurance claim documents (if any)
Storage:
- Fireproof safe at home
- Cloud storage (digital backup)
- Safety deposit box at bank
Can I insure my home for more than it’s worth?
No, insurance companies prevent “overinsurance”:
Insurance is designed to restore you to pre-loss condition, not profit from loss.
Why: Prevents fraudulent claims and incentive to cause damage.
The limit: Insurance won’t pay more than replacement/actual cash value.
If I improve my home, do I need to notify my insurance company?
Yes, significant improvements should be reported:
Improvements that increase home value:
- New roof
- New electrical/plumbing
- Room addition
- Major kitchen/bathroom remodeling
- Swimming pool addition
- Security system addition
Why: These improvements often REDUCE risk (new roof means less weather damage risk), which should LOWER your rates.
Reality: Many people improve homes and never tell insurance company—missing opportunities for rate reductions.
What’s the difference between actual cash value and replacement cost?
Actual Cash Value (ACV):
- What it pays: Current market value minus depreciation
- Example: 10-year-old couch bought for $2,000, worth $500 today, insurance pays $500
- Cost: Cheaper premium ($200/year example)
- Problem: Gap between what insurance pays and what new item costs
Replacement Cost (RC):
- What it pays: Full cost to replace with new item
- Example: Same couch costs $2,000 new, insurance pays $2,000
- Cost: Higher premium ($300/year example)
- Benefit: No gap, covers full replacement cost
Recommendation: Replacement cost is worth the $100/year premium difference.
What happens if I’m underinsured and need major repairs?
Example scenario:
Home insured for $300,000, actual rebuild cost $400,000.
House catches fire, needs $300,000 in repairs (total is fully destroyed).
What happens:
- Insurance pays: $300,000 (your policy limit)
- Actual cost: $300,000
- Gap: $0 (lucky in this example, but catastrophic if damage exceeded rebuild cost)
Coinsurance clause (sometimes applies):
Many policies have clause requiring you to insure for 80-90% of replacement cost.
If you insure for LESS:
- Insurance company may apply “coinsurance penalty”
- You pay larger portion of loss
Example with coinsurance:
- Home rebuild cost: $400,000
- You insure for: $300,000 (75% of value)
- Damage amount: $80,000
- Coinsurance penalty applies
- You pay more than just deductible
Avoid this: Insure for full replacement cost to avoid penalties.
Is there liability coverage if my dog bites someone?
Yes, homeowners/renters liability covers:
Dog bite injury claims:
- Medical bills
- Damages for permanent scarring
- Pain and suffering
How it works:
Your dog bites guest, causing injuries:
- Claim filed against your homeowners insurance
- Insurance covers (up to liability limit)
- You’re protected
Some exclusions:
- Certain breeds may be excluded (check your policy)
- Prior bite history might affect coverage
- Intentional harm not covered
Note: High-risk breeds (pit bulls, etc.) may have exclusions or require special endorsement (additional cost).
Take Action: Your Property Insurance Action Plan
30-Day Property Insurance Checklist
Week 1: Assess Current Situation
Homeowners:
- Review current policy documents
- Note dwelling coverage amount
- Note contents coverage amount
- Note liability limit
- Note deductible
- Note policy expiration date
- Get home replacement cost estimate (call insurer or get appraisal)
- Compare estimated rebuild cost to current dwelling coverage
Renters:
- Determine if you have renters insurance (check apartment documents)
- If yes, review policy and note coverage amounts
- If no, plan to purchase
Week 2: Get Quotes
- Visit 5-7 insurance websites (InsWeb, The Zebra, direct insurers)
- Enter home/apartment information
- Get quotes for your desired coverage
- Create comparison spreadsheet
- Note which company has best value (not just cheapest)
- Check company ratings (JD Power, AM Best)
Week 3: Make Decision
- Choose insurance company with best value
- Verify coverage amounts meet your needs
- Confirm replacement cost (not ACV) for dwelling/contents
- Verify liability limit at least $300,000
- Complete application
- Schedule policy start date
Week 4: Finalize and Prepare
- Complete insurance application
- Set up automatic payment (monthly or annual)
- Download policy documents
- Save documents (cloud storage + physical backup)
- Create home inventory (walk through, list contents, take photos/video)
- Note policy number, deductible, claim process
- Set calendar reminder for annual review
Ongoing Maintenance
Quarterly:
- Review any home improvements made
- Note valuable items purchased
- Update inventory list
Annually:
- Review coverage limits (still adequate?)
- Get 2-3 quote comparisons
- Verify all discounts applied to your policy
- Switch if better deal found
When life changes:
- Major home improvement: Update coverage
- Expensive item purchase: Consider scheduling
- Change jobs: Verify coverage still adequate
- Marriage/children: May affect liability needs
Conclusion: Property Insurance Protects Your Most Valuable Assets
Your home and possessions represent years of financial sacrifice and hard work. Losing them to preventable catastrophe is devastating.
Yet proper property insurance is remarkably affordable:
- Homeowners: $800-1,500/year ($67-125/month)
- Renters: $150-300/year ($12-25/month)
These small investments protect against financial devastation worth hundreds of thousands of dollars.
The core principles:
✅ Buy adequate dwelling coverage: Full replacement cost, updated annually
✅ Buy adequate contents coverage: 50-75% of dwelling coverage minimum
✅ Buy sufficient liability: Minimum $300,000 (cheap upgrade)
✅ Choose replacement cost: Worth small premium increase
✅ Document possessions: Photos/video of everything you own
✅ Schedule valuable items: Special coverage for high-value goods
✅ Bundle home + auto: 10-25% savings
✅ Use available discounts: Safety features, good credit, loyalty
✅ Shop every 2-3 years: Better deals available regularly
✅ Update when home improves: New roof, renovations should reduce rates
Your home isn’t just walls and furniture—it’s your sanctuary, your nest egg, your security. Protect it properly.
Ready to complete your financial protection? Explore these related guides:
- Complete Insurance Guide: Protect Your Financial Future – Comprehensive protection overview
- Life Insurance Explained: Term vs Whole Life and How Much You Need – Family protection
- Health Insurance Guide: Choose the Right Plan and Save Money – Medical protection
- Disability Insurance: Protect Your Income From Unexpected Events – Income protection
- Best Bank Accounts for 2025: Checking, Savings & Money Market – Safe savings accounts
- Best Budgeting Apps: Top Tools to Manage Your Money in 2025 – Track insurance costs
Leave a Reply