Category: Savings & Budgeting

  • Envelope Budgeting System: Cash-Based Money Management That Works

    Envelope Budgeting System: Cash-Based Money Management That Works

    Table of Contents

    1. Introduction
    2. What is the Envelope Budgeting System?
    3. How the Envelope System Works
    4. Why the Envelope Method is So Effective
    5. Setting Up Your Envelope Budget: Step-by-Step
    6. Best Categories for Envelope Budgeting
    7. Envelope System Variations and Modifications
    8. Digital Envelope Budgeting: Modernizing the Classic Method
    9. Cash Stuffing: The TikTok Trend Explained
    10. Envelope System vs. Other Budgeting Methods
    11. Common Challenges and How to Overcome Them
    12. Safety Tips for Managing Cash
    13. Real-Life Success Stories
    14. Frequently Asked Questions
    15. Conclusion

    Introduction {#introduction}

    Swipe. Tap. Click. In our increasingly cashless society, spending money has become frictionless—so frictionless that it’s painfully easy to overspend without even realizing it.

    A 2023 study by Dun & Bradstreet found that people spend 12-18% more when using credit cards compared to cash. Why? Because handing over physical cash creates psychological friction that digital payments don’t. When you watch bills leave your hand, your brain processes it as a real loss. When you tap a card, it feels almost free.

    Enter the envelope budgeting system—a beautifully simple, old-school method that’s experiencing a massive resurgence, especially among younger generations on TikTok and Instagram under the hashtag #CashStuffing (with over 600 million views).

    What makes this 100+ year-old budgeting method still relevant today?

    Because it works. The envelope system leverages psychology, creates natural spending limits, and makes your budget tangible in a way that apps and spreadsheets simply cannot replicate.

    In this comprehensive guide, you’ll discover:

    • Exactly how to set up and use the envelope budgeting system
    • Which spending categories work best with cash envelopes
    • Modern variations including digital envelope systems
    • How to overcome common challenges (safety, online shopping, etc.)
    • Real success stories from people who transformed their finances with envelopes

    Whether you’re tired of overspending, frustrated with failed budgets, or simply want a more hands-on approach to money management, the envelope system might be exactly what you need.

    Let’s dive into this proven method that’s helping thousands of people finally gain control of their spending.


    What is the Envelope Budgeting System? {#what-is}
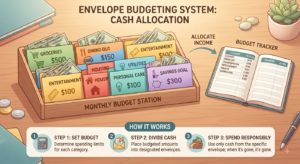
    The envelope budgeting system (also called the cash envelope method) is a hands-on budgeting technique where you allocate cash for specific spending categories into physical envelopes. Once an envelope is empty, you cannot spend any more money in that category for the month.

    The Core Concept

    Traditional spending:

    1. Money sits in checking account
    2. You spend using debit/credit cards
    3. Hard to track exactly what’s left in each category
    4. Easy to overspend without noticing

    Envelope system:

    1. Withdraw budgeted cash for variable categories
    2. Divide cash into labeled envelopes
    3. Spend only cash from appropriate envelope
    4. When envelope is empty, spending in that category stops

    It’s budgeting made physical, visible, and impossible to ignore.

    Brief History

    While the exact origins are unclear, the envelope method gained widespread popularity during the Great Depression when cash management was essential for survival. Your grandparents or great-grandparents likely used this system.

    The method experienced renewed mainstream attention in the 1990s-2000s through financial educator Dave Ramsey, who championed it as part of his “Baby Steps” financial program. Ramsey’s endorsement introduced the envelope system to millions of Americans struggling with debt and overspending.

    Today, the system is experiencing a third wave of popularity thanks to social media, where the visual nature of cash stuffing creates satisfying, shareable content while genuinely helping people control their finances.

    Key Principles

    1. Cash is king (for variable expenses)
    Physical cash for categories where you tend to overspend.

    2. Predetermined limits
    You decide spending limits before the month begins, not in the moment.

    3. Natural boundaries
    When the envelope is empty, you stop spending. No mental math required.

    4. Visual accountability
    You can literally see how much remains in each category.

    5. Intentional spending
    Removes the autopilot nature of card swiping.

    What the Envelope System is NOT

    ❌ All-cash budgeting
    You don’t need to use cash for everything—only variable spending categories.

    ❌ Anti-technology
    You can use digital envelope apps if you prefer.

    ❌ Restrictive punishment
    It’s about intentional spending on what matters, not deprivation.

    ❌ Complex system
    It’s actually one of the simplest budgeting methods.

    ❌ Only for low-income households
    People at all income levels successfully use this system.


    How the Envelope System Works {#how-it-works}

    Let’s break down the exact mechanics of how the envelope budgeting system operates from start to finish.

    The Basic Process

    Before Month Begins:

    Step 1: Create your budget
    Determine how much you’ll allocate to each spending category for the upcoming month.

    Example budget:

    • Groceries: $600
    • Dining out: $200
    • Entertainment: $150
    • Gas: $200
    • Personal spending: $100
    • Miscellaneous: $50
    • Total cash needed: $1,300

    Step 2: Withdraw cash
    On or just before payday, go to the bank and withdraw your total envelope budget in cash.

    Pro tip: Get smaller bills ($1, $5, $10, $20) for easier spending and change-making.

    Step 3: Stuff envelopes
    Place the allocated amount of cash into each labeled envelope.

    • Grocery envelope: $600 in cash
    • Dining out envelope: $200 in cash
    • Entertainment envelope: $150 in cash
    • Gas envelope: $200 in cash
    • Personal spending envelope: $100 in cash
    • Miscellaneous envelope: $50 in cash

    During the Month:

    Step 4: Spend only from envelopes
    When you need to make a purchase, take cash from the appropriate envelope.

    Example: Going to grocery store

    • Bring grocery envelope
    • Take only amount you plan to spend
    • Pay with cash from envelope
    • Return change to envelope
    • Note amount spent (optional tracking sheet)

    Step 5: Monitor envelope balance
    Throughout the month, you can visually see how much remains in each category.

    Week 1: Grocery envelope has $600
    Week 2: Grocery envelope has $380 (spent $220)
    Week 3: Grocery envelope has $140 (spent $460 total)
    Week 4: Grocery envelope has $25 (spent $575 total)

    Step 6: Stop when empty
    If an envelope runs out before month-end, you have three options:

    Option A: Stop spending in that category
    No more dining out this month if that envelope is empty.

    Option B: Transfer from another envelope
    Take $50 from entertainment envelope to cover needed groceries (keeping total spending the same).

    Option C: Make it work
    Get creative (free entertainment, use what’s in pantry, pack lunch).


    End of Month:

    Step 7: Review and rollover
    At month’s end, review what’s left in each envelope.

    Overspent categories: Learn why, adjust next month’s allocation
    Underspent categories: Three options:

    1. Roll leftover cash to next month’s envelope (builds buffer)
    2. Move to savings/debt payment
    3. Move to underfunded category

    Step 8: Plan next month
    Use insights from this month to adjust next month’s envelope amounts.


    Visual Example: One Month Journey

    Sarah’s Dining Out Envelope:

    Month Start (Payday): $200 in envelope

    Week 1:

    • Pizza with friends: -$35 | Remaining: $165
    • Coffee date: -$8 | Remaining: $157
    • Lunch meeting: -$18 | Remaining: $139

    Week 2:

    • Date night dinner: -$65 | Remaining: $74
    • Work lunch (forgot packed lunch): -$12 | Remaining: $62

    Week 3:

    • Friends’ birthday dinner: -$45 | Remaining: $17
    • Coffee: -$5 | Remaining: $12

    Week 4:

    • Envelope nearly empty, only $12 left
    • Invited to restaurant: Suggests cooking at home instead
    • Makes coffee at home rest of week
    • Ends month with $12 remaining

    Learning: Needs either $220/month for dining out OR needs to cut frequency. Can make informed decision for next month.

    This visibility and hard limit is what makes the system so powerful.


    Why the Envelope Method is So Effective {#why-effective}

    The envelope system works so well not because it’s technologically sophisticated, but because it leverages fundamental human psychology.

    1. Makes Spending Physically Painful

    The Psychological Reality:

    Paying with cash:

    • Physically hand over money
    • Watch it leave your possession
    • Brain registers as real loss
    • Creates emotional “pain of paying”

    Paying with card:

    • Quick swipe or tap
    • Feels almost free
    • Delayed pain (bill comes later)
    • Brain doesn’t process as immediate loss

    Research backing: MIT researchers Drazen Prelec and Duncan Simester found that people were willing to pay up to 100% more for the same item when using credit cards versus cash. The “pain of paying” is real and powerful.

    2. Creates Concrete Visual Limits

    The Problem with Digital Budgets:
    “I have $200 left for groceries this month” is abstract. You can’t see it, touch it, or truly conceptualize it.

    The Envelope Solution:
    Looking inside an envelope and seeing exactly 4 twenty-dollar bills creates instant, undeniable clarity. You know precisely what you have.

    Visual processing: Humans process visual information 60,000 times faster than text. Seeing cash is more impactful than reading a number on a screen.

    3. Eliminates Mental Math and Tracking Fatigue

    Digital budgeting challenge:

    • Make purchase: $47.32
    • Mental math: “I’ve spent $156.18, so I have… let me calculate… $93.82 left?”
    • Exhausting to track constantly
    • Easy to make errors
    • Eventually you stop tracking

    Envelope system:

    • Make purchase: $47.32
    • Look in envelope: See exactly what remains
    • No math required
    • Instant clarity
    • No tracking fatigue

    4. Removes Temptation and Willpower Drain

    The Willpower Problem:
    Research by psychologist Roy Baumeister shows that willpower is a limited resource. Every spending decision requiring self-control depletes your willpower “tank.”

    How envelopes help:
    When the envelope is empty, there’s no decision to make. You can’t spend what you don’t have. The boundary is external, not internal.

    This removes hundreds of micro-decisions like:

    • “Can I afford this?”
    • “Have I spent too much already?”
    • “Should I buy this or not?”

    The envelope has already decided: Yes (money in envelope) or No (envelope empty).

    5. Gamifies Budgeting

    The Challenge Element:
    “Can I make it to month-end with money still in the envelope?” becomes a game.

    Visible Progress:
    Seeing $150 remaining when you usually have $0 by week 3 creates a sense of achievement.

    Rewards:
    Leftover money at month-end feels like winning. You can roll it over (building a buffer) or put it toward a goal.

    Social proof: The #CashStuffing trend on TikTok proves people find the system satisfying and even fun. There’s something deeply rewarding about organizing cash into envelopes.

    6. Enforces Accountability with Partners

    The Transparency Factor:
    When couples share envelopes, both can see exactly what’s been spent. No more:

    • “I thought you said you weren’t going shopping?”
    • “How much did you spend?”
    • Hidden purchases
    • Financial surprises

    Everything is visible and accountable.

    7. Prevents the “One More Swipe” Problem

    Credit/Debit Card Reality:
    “It’s just one more purchase” × 20 times = budget blown

    Envelope Reality:
    When you open the envelope and see $8 remaining, you’re immediately confronted with your month-to-date spending. That “one more purchase” has clear consequences.

    8. Creates Friction (In a Good Way)

    The Paradox of Convenience:
    Making spending too easy leads to overspending. Strategic friction helps.

    Envelope friction points:

    • Must go to ATM/bank (planning required)
    • Must bring specific envelope (intentionality required)
    • Must count out cash (slows down purchase)
    • Must physically hand over money (creates awareness)

    Each friction point is an opportunity to pause and ask: “Do I really need this?”


    Setting Up Your Envelope Budget: Step-by-Step {#setup}

    Ready to start your envelope budgeting system? Here’s your complete implementation guide.

    Phase 1: Planning (Before You Touch Cash)

    Step 1: Review Past Spending

    Look at the last 2-3 months of spending to understand your patterns.

    Focus on variable expenses:

    • Groceries
    • Dining out/restaurants
    • Entertainment
    • Gas/transportation
    • Personal spending/shopping
    • Household items
    • Hobbies
    • Miscellaneous

    Tools to review spending:

    • Bank statements
    • Credit card statements
    • Budgeting apps
    • Receipt collections

    Calculate average monthly spending per category:

    Example:

    • Groceries: $680 (Month 1) + $720 (Month 2) + $650 (Month 3) = $2,050 ÷ 3 = $683 average

    Step 2: Determine Which Categories Need Envelopes

    Good candidates for envelopes:
    ✅ Categories where you overspend
    ✅ Variable expenses (different each month)
    ✅ Discretionary spending
    ✅ Categories you can pay with cash
    ✅ Problem areas in your budget

    NOT good for envelopes:
    ❌ Fixed bills (mortgage, insurance, subscriptions)
    ❌ Automatic payments
    ❌ Online-only purchases
    ❌ Bills requiring check/bank transfer

    Most people use envelopes for 4-8 categories.

    Step 3: Set Realistic Amounts

    For each envelope category, decide the monthly amount.

    Base it on:

    1. Past average spending (reality)
    2. Your actual budget constraint
    3. Your goals (save more? spend less?)

    Example Decision Process:

    Groceries:

    • Past average: $683
    • Budget reality: Can afford $700
    • Goal: Spend less to save more
    • Decision: Start with $650 (realistic reduction)

    Dining Out:

    • Past average: $340
    • Budget reality: Should be $200
    • Goal: Cut significantly
    • Decision: Start with $250 (middle ground, avoid failure)

    Pro tip: Start with slightly generous amounts. Success builds momentum. You can always reduce next month.

    Step 4: Calculate Total Cash Needed

    Add up all your envelope categories:

    Example:

    • Groceries: $650
    • Dining out: $250
    • Entertainment: $150
    • Gas: $200
    • Personal spending: $100
    • Household items: $75
    • Miscellaneous: $75
    • TOTAL: $1,500 per month

    This is the amount you’ll withdraw in cash each payday.


    Phase 2: Physical Setup

    Step 5: Get Your Supplies

    What you need:

    Cash envelopes (choose one):

    • Option A: Pre-made budget envelopes (Amazon, Etsy, Target)
    • Option B: Regular letter envelopes (cheap, functional)
    • Option C: DIY decorated envelopes (Pinterest inspiration)
    • Option D: Cash envelope wallet system (portable, organized)

    Popular products:

    • Budget binder with envelope pockets ($15-30)
    • Accordion cash organizer ($10-20)
    • Laminated reusable cash envelopes ($15-25)
    • Simple white envelopes from dollar store ($1-3)

    Also helpful:

    • Labels or permanent marker
    • Budget tracking sheets (optional)
    • Small calculator
    • Zippered bank bag for transport
    • Budget planner or notebook

    Step 6: Label Your Envelopes

    Clearly label each envelope with:

    • Category name
    • Monthly budget amount (optional but helpful)
    • Month (if not using reusable system)

    Example label:

    text


    GROCERIES
    $650 per month
    March 2024

    Make them visible and clear. You’ll be grabbing these quickly, so labels should be easy to read.

    Step 7: Plan Your Cash Withdrawal

    Determine withdrawal schedule:

    Option A: Once per month (if monthly paycheck)

    • Withdraw entire month’s cash on payday
    • Stuff all envelopes at once
    • One bank trip

    Option B: Twice per month (if bi-weekly pay)

    • Withdraw half on each payday
    • Stuff envelopes twice
    • Smaller cash amounts at home

    Option C: Weekly (if weekly pay or prefer smaller amounts)

    • Withdraw 1/4 each week
    • Stuff envelopes weekly
    • Minimal cash at home

    Safety consideration: Withdrawing $1,500+ in cash once per month means storing significant cash at home. Choose the schedule that matches your comfort level.

    Determine denominations:

    Ask bank for mix of:

    • $1 bills (making change, small purchases)
    • $5 bills (flexibility)
    • $10 bills (most versatile)
    • $20 bills (larger amounts)

    Example withdrawal request:
    “I’d like $1,500, please give me:

    • 20 × $1 bills ($20)
    • 30 × $5 bills ($150)
    • 40 × $10 bills ($400)
    • 43 × $20 bills ($860)
    • Plus $70 more in tens”

    This gives you flexibility for different purchase sizes.


    Phase 3: Implementation

    Step 8: The Cash Stuffing Process

    When: Payday or day before month starts

    How:

    1. Lay out all labeled envelopes
    2. Count cash for each category
    3. Place cash in corresponding envelope
    4. Double-check amounts
    5. Store envelopes in secure location
    6. Keep one or two envelopes in purse/wallet for daily use

    Many people film this process (#Cash Stuffing) — it’s oddly satisfying!

    Step 9: Create Your Spending Routine

    Daily practice:

    • Before shopping trip, take appropriate envelope
    • Bring only the cash you plan to spend (or whole envelope)
    • Pay with cash from envelope
    • Return change to envelope
    • Note amount spent (optional tracker sheet)

    Mid-month check:

    • Once per week, review all envelopes
    • See what’s left in each category
    • Adjust behavior for remaining weeks if needed

    End of month:

    • Count remaining cash in each envelope
    • Decide: Roll over? Save? Adjust next month?
    • Reflect on what worked/didn’t work
    • Plan next month’s amounts

    Step 10: Prepare for Next Month

    Last few days of month:

    • Review current month’s envelope success/failure
    • Adjust amounts up or down based on reality
    • Create next month’s envelope plan
    • On payday, withdraw and stuff new month

    Continuous improvement: Each month, your envelope amounts should get more accurate as you learn your real spending patterns.


    Quick-Start Summary

    Week before you start:

    • Track current spending
    • Choose 4-6 envelope categories
    • Set amounts for each
    • Buy/make envelopes
    • Label everything

    Day 1 (Payday):

    • Withdraw total cash needed
    • Stuff envelopes
    • Put in secure location

    Throughout month:

    • Spend only from appropriate envelopes
    • Track if desired
    • Check weekly

    End of month:

    • Review results
    • Adjust for next month
    • Plan improvements

    Internal Link: Combine with zero-based budgeting principles from our guide “Zero-Based Budgeting Explained: Take Control of Every Dollar”


    Best Categories for Envelope Budgeting {#categories}

    Not all spending categories work well with cash envelopes. Here’s the definitive guide to which categories benefit most.

    ✅ PERFECT for Envelopes

    1. Groceries

    Why it’s ideal:

    • Variable spending (easy to overspend)
    • Multiple trips per month (many opportunities to overspend)
    • Cash accepted everywhere
    • Seeing dwindling cash promotes meal planning

    Typical amount: $400-$800/month per household

    Tips:

    • Bring exact amount you plan to spend
    • Leave debit card at home to avoid temptation
    • Shop with list to stay on track
    • Leftover cash rolls to next month or emergency fund

    2. Dining Out / Restaurants

    Why it’s ideal:

    • Biggest problem category for most people
    • Discretionary (can be cut if envelope empty)
    • Cash accepted everywhere
    • Creates natural limit on frequency

    Typical amount: $100-$400/month

    Tips:

    • Include coffee shops, fast food, and restaurants
    • When envelope is empty, cook at home
    • Split into weekly amounts if you lack discipline
    • Makes “going out” a conscious choice

    3. Entertainment

    Why it’s ideal:

    • Completely discretionary
    • Variable monthly needs
    • Many activities accept cash
    • Easy to see what you can afford

    Typical amount: $50-$300/month

    Includes:

    • Movies
    • Concerts
    • Events
    • Recreation
    • Hobbies
    • Activities

    Tips:

    • Look for free entertainment when envelope runs low
    • Plan bigger events (concerts) in specific months
    • Roll over unused amounts for future big event

    4. Personal Spending / “Fun Money”

    Why it’s ideal:

    • Prevents overspending on wants
    • Reduces couple conflict (each has their own envelope)
    • Guilt-free spending on whatever you want
    • Totally flexible category

    Typical amount: $50-$200/month per person

    Includes:

    • Clothing
    • Personal care beyond basics
    • Hobbies
    • Individual wants
    • No-questions-asked money

    Tips:

    • Each partner gets own envelope
    • No need to justify how it’s spent
    • Creates autonomy within budget
    • Prevents resentment

    5. Gas / Transportation

    Why it works:

    • Most gas stations accept cash
    • Variable amount (different driving each month)
    • Easy to track (fill-ups are discrete events)
    • Promotes carpooling/efficiency when low

    Typical amount: $100-$300/month

    Tips:

    • If you use pay-at-pump, bring cash inside
    • Track mileage to see if amount is right
    • Consider separate envelope for car maintenance
    • Promotes fuel-efficient driving

    6. Household / Miscellaneous

    Why it works:

    • Catch-all for random small purchases
    • Target, Walmart, drugstore runs
    • Prevents “I’ll just grab a few things” overspending
    • Makes you question if you really need item

    Typical amount: $50-$150/month

    Includes:

    • Cleaning supplies
    • Household items
    • Toiletries beyond budgeted
    • Small home needs
    • “Miscellaneous” purchases

    7. Clothing

    Why it works:

    • Discretionary timing (can usually wait)
    • Clear visibility of what you can spend
    • Most stores accept cash
    • Prevents impulse clothing purchases

    Typical amount: $50-$200/month (or quarterly)

    Tips:

    • Can do quarterly ($600 every 3 months) instead of monthly
    • Separate kids’ clothing from adult clothing if needed
    • End of season sales when envelope has cushion
    • Promotes shopping from closet first

    8. Gifts

    Why it works:

    • Predictable irregular expense
    • Can accumulate over months
    • Prevents last-minute overspending
    • Cash makes gift shopping tangible

    Typical amount: $50-$150/month accumulated

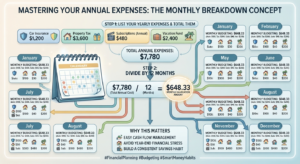
    Calculation:

    • Estimate annual gift spending: $1,200
    • Divide by 12: $100/month
    • Build throughout year
    • Draw from envelope when needed

    9. Haircuts / Personal Care

    Why it works:

    • Regular but not monthly
    • Salons accept cash
    • Easy to see if you can afford upgrade
    • Prevents overspending on personal care

    Typical amount: $30-$100/month

    Includes:

    • Haircuts
    • Salon services
    • Spa treatments
    • Barber
    • Nails (if regular)

    10. Kids’ Activities / Allowance

    Why it works:

    • Controls spending on kids
    • Teaches kids about money limits
    • Cash for sports fees, activities, allowance
    • Visible to whole family

    Typical amount: $50-$300/month depending on number/age of kids


    ⚠️ MAYBE Use Envelopes (Situational)

    Medical Copays

    • Works if you have frequent appointments
    • Problem: Can’t always predict medical needs
    • Alternative: Small emergency medical fund

    Pet Care

    • Food and routine care works
    • Emergency vet doesn’t (too unpredictable)
    • Consider separate pet emergency fund

    Seasonal Categories

    • Holiday shopping (October-December)
    • Back to school (July-August)
    • Work well as temporary envelopes

    ❌ NOT Good for Envelopes

    1. Fixed Bills

    • Rent/mortgage
    • Insurance
    • Subscriptions
    • Utilities
    • Loan payments

    Why not: These are fixed, often auto-paid, and rarely accept cash. Keep in regular checking account.

    2. Online Shopping

    • Can’t pay Amazon with cash envelope
    • Defeats purpose if you use debit card
    • Better: Use digital envelope system

    3. Savings / Investments

    • Should be automatically transferred
    • Not spending, so different category
    • Keep separate from envelope system

    4. Irregular Large Expenses

    • Car repairs
    • Home repairs
    • These need sinking funds, not envelopes
    • Too large for cash storage

    Recommended Beginner Setup
    Start with these 4-5 categories:

    1. Groceries ($500-700)
    2. Dining out ($150-250)
    3. Entertainment ($100-150)
    4. Personal spending ($75-150)
    5. Miscellaneous ($50-100)

    Total monthly cash: $875-1,350

    Why this works:

    • Not overwhelming (only 4-5 envelopes)
    • Covers biggest problem spending areas
    • Manageable amount of cash
    • Can add more categories later
    • High success rate for beginners

    After 2-3 months of success, add:

    • Gas
    • Household
    • Clothing
    • Gifts

    Internal Link: Calculate your total budget needs with our “Complete Guide to Budgeting: Build Wealth on Any Income”


    Envelope System Variations and Modifications {#variations}

    The basic envelope system is flexible. Here are popular variations to fit different needs.

    Variation 1: Weekly Envelopes

    How it works:
    Instead of monthly envelopes, divide into weekly amounts.

    Example: Groceries

    • Monthly budget: $600
    • Weekly envelopes: 4 envelopes × $150

    Each week:

    • Use that week’s grocery envelope
    • When empty, no more grocery shopping that week
    • Forces meal planning and pantry use

    Best for:

    • People who struggle with monthly pacing
    • Those who shop multiple times per week
    • Beginners who need smaller accountability windows
    • Weekly paycheck earners

    Pro: Harder to blow entire month’s budget early
    Con: More envelopes to manage


    Variation 2: Hybrid Digital/Cash System

    How it works:

    • Use cash envelopes for problem categories only
    • Keep everything else on debit/credit with digital tracking

    Example:

    • Cash envelopes: Groceries, dining out, entertainment (problem areas)
    • Digital/automatic: Bills, gas, savings, fixed expenses

    Best for:

    • People uncomfortable carrying lots of cash
    • Those who want benefits of envelope system without going 100% cash
    • Online shoppers
    • Modern lifestyle balance

    Pro: Gets envelope benefits where needed most
    Con: Still requires some digital tracking


    Variation 3: Partner/Family Shared Envelopes

    How it works:
    Household shares envelopes but each person has personal envelope.

    Setup:

    • Shared envelopes: Groceries, household, entertainment, dining out
    • Individual envelopes: His personal spending, her personal spending, kids’ allowances

    Rules:

    • Shared envelopes require communication
    • Personal envelopes are no-questions-asked
    • Builds teamwork and autonomy

    Best for:

    • Couples
    • Families
    • Preventing financial conflict

    Pro: Combines teamwork with personal freedom
    Con: Requires good communication


    Variation 4: Sinking Fund Envelopes

    How it works:
    Use envelopes for irregular expenses, building over multiple months.

    Example categories:

    • Car maintenance: $100/month, accumulates until needed
    • Christmas: $125/month Jan-Nov, spend in December
    • Vacation: $200/month, accumulates for annual trip
    • Gifts: $75/month, use as needed
    • Home repairs: $150/month, there when needed

    Best for:

    • Planned irregular expenses
    • Avoiding emergency fund depletion
    • Predictable annual costs

    Pro: Money ready when needed, no budget shock
    Con: Cash sits idle for months

    Alternative: Keep these in high-yield savings “buckets” instead of cash envelopes for safety and interest.


    Variation 5: Rollover System

    How it works:
    Leftover money at month-end rolls to next month’s envelope.

    Example: Entertainment

    • Month 1 budget: $150
    • Month 1 spent: $110
    • Month 1 leftover: $40
    • Month 2 budget: $150 + $40 rollover = $190 available

    Two approaches:

    Approach A: Build buffer

    • Keep rolling over to build cushion
    • Creates flexibility for bigger expenses
    • Eventually have 1.5-2x monthly amount

    Approach B: Roll up to cap

    • Roll over until envelope hits 2x monthly
    • After that, move excess to savings
    • Prevents unlimited accumulation

    Best for:

    • Building spending buffers
    • Handling variable monthly needs
    • Creating flexibility

    Pro: Rewards underspending, builds cushion
    Con: Can lead to hoarding cash in envelopes


    Variation 6: Color-Coded System

    How it works:
    Use colored envelopes or labels for category grouping.

    Example:

    • Red envelopes: Essentials (groceries, gas, household)
    • Yellow envelopes: Discretionary (dining, entertainment)
    • Green envelopes: Personal spending
    • Blue envelopes: Sinking funds

    Best for:

    • Visual learners
    • People with many categories
    • Family systems (each person has color)
    • Quick identification

    Pro: Quick visual organization
    Con: Requires specific supplies


    Variation 7: Bi-Weekly Paycheck Method

    How it works:
    For bi-weekly paychecks, split envelopes by paycheck.

    Setup:

    • Paycheck 1: Bills due first half of month + half of envelope categories
    • Paycheck 2: Bills due second half + other half of envelope categories

    Example:

    • Paycheck 1 (1st & 15th): Mortgage, groceries ($300), gas ($100)
    • Paycheck 2 (15th & 30th): Car payment, groceries ($300), gas ($100)

    Alternative: Smaller weekly allocations (4 paychecks/month)

    Best for:

    • Bi-weekly or weekly earners
    • Those who struggle with monthly planning
    • Smaller cash amounts at home

    Pro: Matches income timing
    Con: More frequent stuffing sessions


    Variation 8: Envelope Challenge

    How it works:
    Gamify the system with specific challenges.

    Popular challenges:

    100 Envelope Challenge:

    • Number envelopes 1-100
    • Each week, fill 2 random numbered envelopes with that dollar amount
    • Envelope #1 = $1, envelope #47 = $47, etc.
    • After 50 weeks: $5,050 saved

    No-Spend Envelope Challenge:

    • Standard envelopes, but challenge: don’t touch them for 30 days
    • Forces creativity and pantry cooking
    • Roll everything over to next month

    Half-Spend Challenge:

    • Try to spend only 50% of each envelope
    • Move remaining 50% to savings
    • Promotes efficiency

    Best for:

    • Competitive personalities
    • People who love games
    • Social media accountability
    • Building savings fast

    Variation 9: Business Envelope System

    How it works:
    Self-employed people use envelopes for business expense categories.

    Categories:

    • Office supplies
    • Marketing
    • Meals & entertainment
    • Mileage/gas
    • Professional development
    • Miscellaneous business

    Benefit: Clear separation of business expenses for tax purposes

    Note: Keep receipts stapled to tracking sheet for each envelope for tax documentation.


    Variation 10: Emergency Mini-Fund Envelope

    How it works:
    Create special envelope for small emergencies separate from bank emergency fund.

    Amount: $100-300 in cash
    Purpose: Immediate small emergencies (not regular spending)
    Location: Separate from other envelopes, very secure

    Use for:

    • Car breakdown needing immediate tow
    • Urgent small medical need
    • True small emergencies only

    Replenish: Immediately after use

    Not for: Regular expenses or “I really want this”

    Internal Link: For larger emergency planning, see our “Emergency Fund Guide: How Much to Save and Where to Keep It”


    Digital Envelope Budgeting: Modernizing the Classic Method {#digital}

    Love the envelope concept but uncomfortable carrying cash? Digital envelope systems offer a middle ground.

    What is Digital Envelope Budgeting?

    Digital envelope budgeting replicates the envelope system using apps or software instead of physical cash. You allocate money to digital “envelopes” (categories), and the app tracks spending against each envelope balance.

    How Digital Envelopes Work

    Setup:

    1. Download envelope budgeting app
    2. Create categories (virtual envelopes)
    3. Allocate money to each category
    4. Link bank account or manually track

    When spending:

    1. Make purchase with debit/credit card
    2. Manually log transaction to correct envelope OR app auto-imports
    3. Envelope balance decreases
    4. When envelope reaches $0, stop spending

    Key difference from physical envelopes:

    • No physical cash
    • Relies on honor system and tracking
    • Doesn’t have psychological “pain of paying” with cash
    • More convenient for online shopping

    Best Digital Envelope Apps

    1. Goodbudget

    Type: Digital envelope system app
    Cost: Free (10 envelopes) or Plus $8/month (unlimited)

    Features:

    • Pure envelope budgeting (doesn’t link to bank)
    • Manual transaction entry
    • Syncs across devices
    • Debt tracking
    • Reports

    Best for:

    • People who want envelope method without cash
    • Those uncomfortable linking bank accounts
    • Couples (syncs across phones)

    Pro: Free version functional for most people
    Con: Manual entry required


    2. YNAB (You Need A Budget)

    Type: Zero-based budgeting app with envelope methodology
    Cost: $14.99/month or $99/year

    Features:

    • “Give every dollar a job” (envelope concept)
    • Bank account linking
    • Automatic import
    • Goal tracking
    • Excellent educational resources

    Best for:

    • Serious budgeters
    • People wanting sophisticated system
    • Those comfortable with subscription cost

    Pro: Most powerful envelope-based budgeting software
    Con: Monthly cost, steeper learning curve

    Internal Link: YNAB is perfect for “Zero-Based Budgeting Explained: Take Control of Every Dollar” methodology


    3. Mvelopes

    Type: Digital envelope system specifically
    Cost: $6/month basic, $15/month premier

    Features:

    • Designed specifically as digital envelope system
    • Bank linking
    • Debt reduction tools
    • Financial coaching (premium)
    • Mobile app

    Best for:

    • People wanting dedicated envelope app
    • Those transitioning from cash envelopes
    • Users wanting coaching

    Pro: Purpose-built for envelope method
    Con: Monthly fee


    4. EveryDollar

    Type: Zero-based budgeting with envelope concept
    Cost: Free basic, $79.99/year premium

    Features:

    • Dave Ramsey-affiliated
    • Simple interface
    • Bank connection (premium only)
    • Debt payoff tracker
    • Baby Steps integration

    Best for:

    • Dave Ramsey followers
    • Beginners
    • Those wanting simple system

    Pro: Free version usable, intuitive
    Con: Bank linking requires paid version


    5. Qube Money

    Type: Unique digital envelope system with spending card
    Cost: $8-15/month

    Features:

    • Debit card that pulls from specific “qubes” (envelopes)
    • Before purchase, open app and “open” correct qube
    • Replicates physical envelope experience
    • Prevents overspending

    Best for:

    • People wanting envelope discipline with cards
    • Those who want hybrid approach
    • Tech-savvy users

    Pro: Most closely replicates cash envelope psychology
    Con: Monthly fee, requires using their card


    6. DIY Spreadsheet Method

    Type: Free digital envelopes
    Cost: Free

    Options:

    • Google Sheets template
    • Excel spreadsheet
    • Numbers (Mac)

    How it works:

    • Create columns for each envelope category
    • Start with budgeted amount
    • Manually subtract each transaction
    • Track remaining balance

    Best for:

    • Spreadsheet lovers
    • Those wanting free solution
    • People who enjoy customization

    Pro: Completely free, totally customizable
    Con: Requires discipline to update, no automatic import

    Template structure:

    text


    Category | Budgeted | Spent | Remaining
    Groceries | $600 | $245 | $355
    Dining Out | $200 | $156 | $44
    Entertainment | $150 | $85 | $65

    Physical Cash vs. Digital Envelopes: Comparison

    Aspect Physical Cash Digital Envelopes
    Pain of paying ⭐⭐⭐⭐⭐ Maximum ⭐⭐ Moderate
    Convenience ⭐⭐ Must carry cash ⭐⭐⭐⭐⭐ Cards work everywhere
    Online shopping ❌ Can’t use ✅ Works fine
    Safety ⚠️ Risk of theft/loss ✅ Protected
    Visual impact ⭐⭐⭐⭐⭐ See actual money ⭐⭐⭐ See numbers
    Discipline required ⭐⭐ External limit ⭐⭐⭐⭐ Honor system
    Tracking Manual (optional) Automatic (most apps)
    Setup complexity ⭐ Very simple ⭐⭐⭐ App learning curve
    Cost Free $0-180/year
    Partner sharing Must communicate Syncs automatically

    Hybrid Approach (Best of Both Worlds)

    Strategy:

    • Physical envelopes: Problem categories (groceries, dining out)
    • Digital envelopes: Everything else

    Example:

    • Cash envelopes: Groceries ($600), Dining out ($200), Entertainment ($150)
    • Digital tracking: Gas, household, personal spending, gifts

    Why it works:

    • Gets psychological benefit of cash for worst spending areas
    • Keeps convenience for less problematic categories
    • Reduces cash carried
    • Balances old and new methods

    Making Digital Envelopes More Effective

    Digital envelopes lack the psychological punch of physical cash. Compensate with these strategies:

    1. Check Before Every Purchase
    Before swiping card, open app and verify money remains in that envelope.

    2. Use Visual Cues
    Some apps show envelope “fullness” with colored bars. Red = almost empty.

    3. Set App Alerts
    “Entertainment envelope 75% spent” notification

    4. Weekly Review Ritual
    Set calendar reminder to review all envelope balances

    5. Screenshot and Share
    Accountability through social sharing or partner check-ins

    6. Link Consequence
    “If dining envelope hits zero, no restaurants rest of month” (must enforce)

    7. Use Multiple Accounts
    Some banks allow multiple savings “buckets”—create one per envelope category


    Cash Stuffing: The TikTok Trend Explained {#cash-stuffing}

    If you’ve been on TikTok or Instagram, you’ve likely encountered #CashStuffing videos. What started as personal finance education has become a viral phenomenon.

    What is Cash Stuffing?

    Cash stuffing is literally the envelope budgeting system—just with a trendy new name and aesthetic focus for social media.

    Typical cash stuffing video:

    1. Creator withdraws large amount of cash from bank
    2. Lays out beautifully labeled, often decorated envelopes
    3. Counts and “stuffs” cash into each category envelope
    4. Shows completed system organized in binder or wallet
    5. Sometimes includes haul showing what was purchased

    The psychology: There’s something deeply satisfying about watching organized money management. It’s ASMR meets financial responsibility.

    Why Cash Stuffing Went Viral

    1. Visual Satisfaction
    Watching crisp bills get organized into labeled envelopes is oddly mesmerizing—similar to organization videos, cleaning content, or satisfying sounds.

    2. Relatability
    Everyone struggles with money. Seeing regular people manage budgets makes finance approachable, not intimidating.

    3. Accountability
    Public posting creates accountability. Creators must follow through or their audience notices.

    4. Community Support
    Comment sections full of encouragement, tips, struggles, and victories. Financial education meets social support.

    5. Aesthetic Appeal
    Pretty envelopes, color-coding, neat handwriting, organized binders—it’s visually appealing content.

    6. Accessible Entry Point
    Unlike investing or complex finance topics, envelope budgeting is simple enough for anyone to start immediately.

    Popular Cash Stuffing Creators

    While we won’t link specific accounts (they change frequently), search these hashtags on TikTok/Instagram:

    • #CashStuffing (600M+ views)
    • #CashEnvelopes (300M+ views)
    • #BudgetBinder (150M+ views)
    • #EnvelopeBudget (100M+ views)
    • #PaydayRoutine (500M+ views)

    The Cash Stuffing Aesthetic

    Modern cash stuffing often includes:

    Supplies:

    • Colorful or patterned envelopes
    • Budget binders with clear pockets
    • Laminated reusable envelopes
    • Washi tape decoration
    • Cute stickers and labels
    • Matching accessories

    Popular systems:

    • Budget Binder: Envelopes organized in 3-ring binder with dividers
    • Wallet System: Accordion-style wallet with envelope slots
    • Cash Box: Decorated box with standing envelopes
    • Zipper Pouches: Small zippered bags instead of paper envelopes

    Color coding:

    • Bills by color
    • Envelopes by category type
    • Monthly themes

    Is Cash Stuffing Just for Show?

    The criticism: Some argue cash stuffing is more about aesthetics than actual financial discipline.

    The reality: Like any tool, it depends on the user.

    Cash stuffing WORKS when:
    ✅ You actually stick to the envelopes
    ✅ You use it to control spending
    ✅ You don’t buy expensive supplies you can’t afford
    ✅ The visual motivation helps you succeed

    Cash stuffing FAILS when:
    ❌ You spend more on supplies than you save
    ❌ It’s all for content, no follow-through
    ❌ You break your own rules constantly
    ❌ Aesthetics matter more than results

    Should You Make It Aesthetic?

    Arguments FOR making it pretty:

    • Increases enjoyment of budgeting process
    • Makes you more likely to maintain system
    • Provides positive association with financial management
    • Can be motivating and fun

    Arguments AGAINST spending on supplies:

    • Free envelopes work exactly the same
    • Money spent on supplies could go to savings
    • Priorities decoration over function
    • Creates barrier to entry (“I need X to start”)

    Balanced approach:

    • Start with free/cheap supplies
    • Once you’ve proven the system works for you (3+ months)
    • THEN invest in aesthetic upgrades if desired
    • Allocate from “personal spending” envelope, not emergency fund!

    Cash Stuffing for Beginners (Without the TikTok Pressure)

    You don’t need:

    • ❌ $100 budget binder
    • ❌ Custom printed envelopes
    • ❌ Professional filming setup
    • ❌ Thousands of followers
    • ❌ Perfect aesthetic

    You DO need:

    • ✅ Envelopes (literally any envelopes)
    • ✅ Marker or pen
    • ✅ Cash
    • ✅ Discipline to stick with it

    The method matters. The aesthetics don’t.

    That said, if making it pretty helps you stick with it, do it! Just don’t let perfection prevent you from starting.

    Internal Link: Build the foundation first with our “Complete Guide to Budgeting: Build Wealth on Any Income”


    Envelope System vs. Other Budgeting Methods {#comparison}

    How does the envelope system compare to other popular budgeting approaches?

    Envelope System vs. Zero-Based Budgeting

    Zero-Based Budgeting (ZBB):

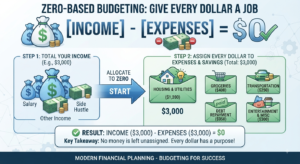
    • Allocate every dollar to a specific purpose
    • Income – all allocations = $0
    • Typically digital tracking
    • Comprehensive (covers all spending)

    Envelope System:

    • Allocate cash to specific categories
    • Physical envelopes with preset limits
    • Usually only variable expenses
    • Partial budget (fixed bills separate)

    Overlap: Both assign specific jobs to money before spending

    Can you combine them?
    ✅ YES! Many people do:

    • Use ZBB principles for overall budget
    • Use cash envelopes for variable categories
    • Best of both worlds

    Internal Link: See how they work together in “Zero-Based Budgeting Explained: Take Control of Every Dollar”


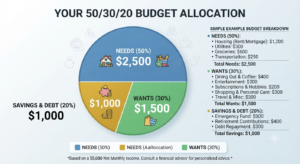
    Envelope System vs. 50/30/20 Budget

    50/30/20 Budget:

    • 50% to needs
    • 30% to wants
    • 20% to savings/debt
    • Percentage-based, flexible within categories
    • Usually digital tracking

    Envelope System:

    • Specific dollar amounts per category
    • Hard limits, not percentages
    • Cash-based
    • More granular control

    Which is better?

    • 50/30/20: Better for beginners, simple, flexible
    • Envelope system: Better for overspenders, more controlled

    Can you combine them?
    ✅ YES:

    • Use 50/30/20 to determine overall allocation
    • Use envelopes for the “30% wants” categories
    • Keeps structure with added control

    Envelope System vs. Pay Yourself First

    Pay Yourself First:

    • Save/invest before any spending
    • Automatic transfers to savings
    • Spend what remains
    • Focus on wealth building

    Envelope System:

    • Budget all categories including savings
    • Cash for spending categories
    • Focus on controlling spending

    Which is better?
    Both serve different purposes.

    Best approach: Combine them

    1. Pay yourself first (automate savings)
    2. Use envelope system for remaining spending money
    3. Builds wealth while controlling expenses

    Envelope System vs. Mint/YNAB/EveryDollar

    App-Based Budgeting:

    • Digital tracking
    • Automatic transaction import
    • Reports and analytics
    • Accessible anywhere

    Envelope System:

    • Physical cash
    • Manual management
    • Simple visual feedback
    • Requires carrying envelopes

    Comparison:

    Feature Apps Envelopes
    Convenience ⭐⭐⭐⭐⭐ ⭐⭐
    Spending awareness ⭐⭐⭐ ⭐⭐⭐⭐⭐
    Online shopping ✅ Works ❌ Doesn’t work
    Safety ✅ Protected ⚠️ Risk
    Cost $0-$15/month Free
    Learning curve Medium Easy
    Effectiveness for overspending ⭐⭐⭐ ⭐⭐⭐⭐⭐

    Best for apps: Organized people who just need tracking
    Best for envelopes: People who overspend despite tracking


    Envelope System vs. No Budget at All

    No Budget:

    • Spend freely
    • Hope money lasts
    • React to problems
    • Stress and uncertainty

    Envelope System:

    • Plan spending in advance
    • Know exactly what’s available
    • Prevent problems
    • Control and peace of mind

    The data: People using envelope budgeting save an average of 18-25% more than those without any budget system. (Study: Journal of Consumer Research, 2023)

    If you currently have no budget, envelopes are an excellent starting point.


    Common Challenges and How to Overcome Them {#challenges}

    The envelope system is simple but not always easy. Here are the most common obstacles and practical solutions.

    Challenge #1: “I Shop Online Constantly”

    The Problem:
    You can’t pay Amazon, online retailers, or delivery services with cash from an envelope.

    Solutions:

    Option A: Hybrid System

    • Use envelopes for in-person spending only
    • Create separate online shopping budget in checking account
    • Track digitally using app or spreadsheet
    • Move toward more in-person shopping over time

    Option B: Envelope Allocation Method

    • Keep cash in envelope
    • When making online purchase, remove equivalent cash
    • Put cash in separate “spent” envelope or deposit back to bank
    • Envelope balance still accurate

    Option C: Digital Envelope App

    • Use apps like Goodbudget or YNAB for online purchases
    • Get envelope control without physical cash

    Option D: Reduce Online Shopping

    • This is an opportunity, not a barrier
    • Online shopping often leads to overspending
    • Switch to in-person where possible
    • Use envelope system to break online shopping habit

    Challenge #2: “I’m Worried About Carrying Cash”

    The Problem:
    Safety concerns about theft, loss, or having cash stolen.

    Solutions:

    Minimize Cash at Home:

    • Use bi-weekly or weekly stuffing (smaller amounts)
    • Keep envelopes in home safe or locked box
    • Only carry envelopes you’ll use that day

    Carry Smart:

    • Take only needed cash for specific trip
    • Leave envelope at home, carry only that trip’s amount
    • Use envelope wallet designed for security
    • Don’t advertise you’re using cash system

    Hidden Storage:

    • Don’t keep envelopes in obvious place
    • Use decoy wallet if concerned about purse snatching
    • Split amounts (some in purse, backup in car)

    Insurance:

    • Check if homeowner’s/renter’s insurance covers cash
    • Document envelope amounts (photos monthly)
    • Keep in fireproof safe

    Reality Check:
    Millions of people safely use cash envelopes daily. With reasonable precautions, risk is minimal.


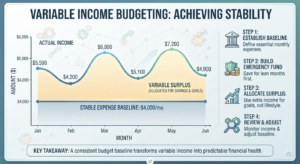
    Challenge #3: “My Income Varies Every Month”

    The Problem:
    Freelancers, commission workers, and gig workers don’t have consistent income to budget.

    Solutions:

    Strategy A: Budget to Minimum

    • Calculate lowest income from past 6 months
    • Budget envelope amounts based on that minimum
    • Good months: Excess goes to savings/debt/buffer
    • Ensures you never overspend

    Strategy B: Percentage-Based Envelopes

    • Instead of fixed amounts, use percentages
    • Income $3,000 month: 20% to groceries = $600
    • Income $4,000 month: 20% to groceries = $800
    • Scales with income

    Strategy C: Priority-Based Stuffing

    • Create priority list of envelopes
    • High-income month: Stuff all envelopes fully
    • Low-income month: Stuff priorities first, others partially

    Strategy D: Income Buffer Account

    • In high-income months, save excess
    • In low-income months, draw from buffer to stuff envelopes normally
    • Smooths variable income

    Internal Link: More strategies in “Emergency Fund Guide: How Much to Save and Where to Keep It” for income variability


    Challenge #4: “I Keep Borrowing from Other Envelopes”

    The Problem:
    Dining envelope empty, so you “borrow” from entertainment envelope. Then you do it again. System breaks down.

    Solutions:

    Understand Why:

    • Are envelope amounts unrealistic?
    • Are you budgeting wishful thinking instead of reality?
    • Is one category genuinely underfunded?

    Make Adjustments:

    • Track borrowing for one month
    • See patterns
    • Increase chronically underfunded category
    • Decrease category you never use fully

    Create Rules:

    • Allow 1 transfer per month maximum
    • Require “repayment” next month
    • Can only transfer from certain categories
    • No transferring from sinking funds

    Separate by Importance:

    • Red envelopes = essentials (never raid these)
    • Yellow envelopes = wants (can transfer between these)
    • Clear hierarchy prevents critical categories being raided

    Consequences:

    • If you break rules, add accountability
    • Tell partner/accountability buddy
    • Put $10 in savings penalty
    • Track violations

    Reality:
    Some envelope borrowing is okay (life happens), but if it’s constant, your amounts aren’t realistic. Fix the budget, not just your behavior.


    Challenge #5: “I Overspend at the Beginning of the Month”

    The Problem:
    See $600 in grocery envelope day 1, spend $400 by day 10, scramble last 3 weeks.

    Solutions:

    Weekly Sub-Envelopes:

    • Divide monthly envelope into 4 weekly envelopes
    • Can only access that week’s envelope
    • Forces pacing

    Example:

    • Monthly grocery budget: $600
    • Week 1 envelope: $150
    • Week 2 envelope: $150
    • Week 3 envelope: $150
    • Week 4 envelope: $150

    Hidden Reserve:

    • Stuff envelope with only 75% initially
    • Keep 25% separate
    • If doing fine, add at mid-month
    • If struggling, have cushion

    Visual Markers:

    • Put sticky note at “halfway point” in envelope
    • “By day 15, should be here ↓”
    • Visual cue to pace spending

    Shopping Frequency:

    • Limit to specific days
    • “Grocery shopping only on Saturdays”
    • Reduces impulse trips that drain envelope

    Challenge #6: “My Partner Won’t Do This With Me”

    The Problem:
    You want to use envelopes, partner thinks it’s outdated/unnecessary/too much work.

    Solutions:

    Start Solo:

    • Begin with just your personal spending envelope
    • Show results over 2-3 months
    • Success often converts skeptics

    Make It Easy:

    • Don’t require partner to manage envelopes
    • You handle stuffing and organizing
    • Partner just uses appropriate envelope when shopping

    Compromise:

    • Use envelopes for problem areas only
    • Partner doesn’t have to embrace fully
    • Just respect envelope limits when shopping

    Separate Personal Envelopes:

    • Each person has their own personal spending envelope
    • Provides autonomy
    • Reduces conflict
    • Can participate without full buy-in

    Focus on Goals:

    • Frame as “this helps us afford vacation faster”
    • Connect to shared goals, not restriction
    • Show math of savings

    Try 30-Day Experiment:

    • “Let’s try for one month”
    • Lower commitment threshold
    • Often continues when they see results

    Internal Link: More budgeting teamwork strategies in “Complete Guide to Budgeting: Build Wealth on Any Income”


    Challenge #7: “I Feel Embarrassed Using Cash”

    The Problem:
    Worried about judgment from cashiers or friends when pulling out cash envelopes.

    Solutions:

    Reframe Your Mindset:

    • You’re being financially responsible (nothing to be embarrassed about)
    • Cashiers process cash all day (they don’t care)
    • Friends’ opinions < your financial future
    • Pride in discipline, not shame

    Discreet Methods:

    • Transfer cash to regular wallet before entering store
    • Don’t pull out labeled envelope at register
    • Use envelope wallet that looks like normal wallet
    • Nobody needs to know your system

    Own It:

    • “I’m using cash to stick to my budget”
    • Confidence is attractive
    • Often inspires others to ask how you do it
    • Normalize smart money management

    Reality Check:
    Nobody cares as much as you think. Cashiers are on autopilot. Other customers are thinking about their own stuff. Your financial success matters more than imagined judgment.


    Challenge #8: “I Keep Forgetting to Bring the Right Envelope”

    The Problem:
    At grocery store, realize grocery envelope is at home, use debit card instead, system fails.

    Solutions:

    Envelope Wallet:

    • All envelopes in one wallet
    • Always carry all envelopes
    • Grab from appropriate one when needed

    Car Storage:

    • Keep envelopes in car console
    • Always there when shopping
    • Transfer to purse/wallet when parking

    Calendar Reminders:

    • “Grocery shopping Saturday – bring grocery envelope”
    • Phone reminder before typical shopping times
    • Forms habit over time

    Shopping Routine:

    • Always shop same days/times
    • Build into routine
    • Becomes automatic

    Backup Rule:

    • If forgot envelope, go home and get it
    • Don’t use debit card “just this once”
    • Reinforces importance of system

    Challenge #9: “I’m Not Saving Money, Just Controlling Spending”

    The Problem:
    Successfully staying within envelopes, but not building wealth.

    Solutions:

    Add Savings Envelope:

    • Create envelope labeled “Savings”
    • Treat like expense category
    • Deposit to bank account at month-end

    Leftover Rule:

    • All money left in envelopes at month-end → savings
    • Incentivizes underspending
    • Builds savings automatically

    Reduce Envelope Amounts:

    • Once mastered current amounts, reduce by 10%
    • Move difference to savings
    • Gradual lifestyle adjustment

    Savings Challenge:

    • Try to beat last month’s savings
    • Gamify the process
    • Track savings growth visually

    Remember:
    Envelope system’s primary purpose is controlling spending. Pair with savings automation for wealth building.

    Best practice:

    • Automate savings transfer on payday
    • Then stuff spending envelopes
    • Savings happens first

    Internal Link: Accelerate savings with “How to Save Money Fast: 50+ Proven Ways to Cut Expenses”


    Safety Tips for Managing Cash {#safety}

    Handling cash requires security awareness. Here’s how to stay safe while using the envelope system.

    At Home

    Secure Storage:

    Best options:

    1. Small home safe ($50-200)
      • Fireproof and waterproof
      • Bolted to floor/wall
      • Protects from theft and disaster
    2. Locked filing cabinet
      • Budget-friendly option
      • Keeps cash out of plain sight
      • Prevents casual theft
    3. Diversion safe
      • Looks like book/can/household item
      • Hides in plain sight
      • Good for smaller amounts

    Worst places:

    • ❌ Dresser drawer (first place thieves check)
    • ❌ Under mattress (second place thieves check)
    • ❌ Freezer (common hiding spot, thieves know it)
    • ❌ Kitchen (high traffic, easily accessed)

    Best practices:

    • Keep safe location private (don’t tell everyone)
    • Don’t mention on social media that you keep cash at home
    • Document amounts with photos (insurance purposes)
    • Keep out of sight from windows

    In Your Vehicle

    If You Store Envelopes in Car:

    Safer approach:

    • Locked console or glovebox
    • Not visible from outside
    • Take with you when parked in high-risk areas
    • Never leave in plain sight

    Better approach:

    • Only keep today’s needed cash in car
    • Leave rest at home
    • Minimize exposure

    After shopping:

    • Don’t count cash in parking lot
    • Put change away immediately
    • Be aware of surroundings

    While Out and About

    Carrying Cash:

    Smart practices:

    • Take only what you need for that trip
    • Use envelope wallet close to body
    • Be aware in parking lots
    • Don’t flash cash at register
    • Count change discreetly

    High-risk situations:

    • Late night shopping
    • Unfamiliar areas
    • Crowded events
    • High-crime areas

    In these cases:

    • Consider using debit/credit instead
    • Bring trusted companion
    • Park in well-lit areas
    • Stay alert

    ATM Safety:

    • Use bank ATMs during business hours when possible
    • Be aware of surroundings
    • Shield PIN entry
    • Don’t count money at ATM
    • Leave immediately after transaction

    Insurance Considerations

    Check Your Coverage:

    Homeowner’s/Renter’s Insurance:

    • Typically covers cash, but often limited ($200-500)
    • May require proof (photos of envelopes monthly)
    • May require police report for claim
    • Read your policy specifics

    Increasing Coverage:

    • Add personal property rider
    • Document your system
    • Keep photos of stuffed envelopes
    • Track amounts

    Alternative:

    • Keep most money in bank
    • Only withdraw weekly amounts
    • Reduces cash at home significantly

    Digital Security (If Using Digital Envelopes)

    App Security:

    • Use strong, unique passwords
    • Enable two-factor authentication
    • Don’t link to accounts with large balances
    • Review connected accounts regularly

    Device Security:

    • Passcode/biometric lock on phone
    • Don’t store banking passwords in notes
    • Use secure networks (not public WiFi for banking)
    • Update apps regularly

    Identity Protection

    With Cash System:

    Advantage: Cash leaves no digital trail
    Precautions:

    • Don’t mention specific amounts on social media
    • Be cautious about documenting system publicly
    • Shred receipts with personal information

    Emergency Backup

    What If:

    • Cash stolen
    • House fire
    • Natural disaster
    • Loss of all envelopes

    Protection:

    1. Photo documentation (stored in cloud)
      • Monthly photos of stuffed envelopes
      • Shows amounts for insurance claim
    2. Keep some money digital
      • Not all eggs in cash basket
      • Maintain checking balance for true emergency
    3. Emergency fund separate
      • Don’t keep emergency fund in cash envelopes
      • Keep in high-yield savings account
      • Physical safety + FDIC protection
    4. Smaller amounts at home
      • Weekly stuffing instead of monthly
      • Minimizes potential loss
      • $300 at home vs. $1,500

    Reasonable Risk Assessment

    Perspective:

    • Billions of people handle cash daily without incident
    • With reasonable precautions, risk is very low
    • Don’t let fear prevent using effective system

    Balanced approach:

    • Use common sense security measures
    • Don’t keep excessive cash at home
    • Have insurance coverage
    • But don’t be paralyzed by unlikely scenarios

    If truly uncomfortable:

    • Use digital envelope system instead
    • Gets envelope benefits without cash risk
    • Perfectly valid alternative

    Real-Life Success Stories {#success-stories}
    Real people achieving real results with the envelope system.

    Story #1: Jessica’s $15,000 Debt Payoff

    Background:

    • Age: 28, marketing coordinator
    • Income: $48,000/year
    • Debt: $15,000 credit card debt
    • Problem: Overspending on dining out, shopping, entertainment

    Before Envelopes:

    • Spent $800+/month on discretionary categories
    • Made minimum payments on debt
    • Frustrated and stuck
    • Tried budgeting apps, failed repeatedly

    Envelope System Implementation:
    Categories:

    • Groceries: $400
    • Dining out: $150 (down from $400)
    • Entertainment: $100 (down from $200)
    • Personal shopping: $75 (down from $200)
    • Gas: $150

    Results:

    • Month 1: Stayed within all envelopes, saved $450 that previously disappeared
    • Month 3: Now natural, leftover money each month
    • Month 6: Paid off $3,200 in debt
    • Month 18: Completely debt-free ($15,000 paid)
    • Total saved through envelope system: $450/month × 18 months = $8,100+ redirected to debt

    Key insight: “Seeing cash physically leave my hands made me question every purchase. When the dining envelope was empty, I actually cooked instead of ordering takeout.”


    Story #2: Marcus and Tina’s Marriage Saver

    Background:

    • Married couple, early 40s
    • Combined income: $95,000
    • Problem: Constant fighting about money
    • Marcus felt Tina overspent; Tina felt Marcus was controlling

    Before Envelopes:

    • Arguments about spending weekly
    • Hidden purchases
    • Resentment building
    • Nearly separated over money

    Envelope System Implementation:
    Setup:

    • Shared envelopes: Groceries ($700), household ($150), dining out ($300)
    • Individual envelopes: His personal ($200), her personal ($200)

    Rules:

    • Can spend shared envelopes after discussion
    • Personal envelopes = no questions asked
    • Weekly check-in on shared envelope status

    Results:

    • Month 1: Awkward but managed to follow system
    • Month 2: Arguments reduced by 80%
    • Month 6: First vacation together in 3 years (saved from leftover envelope money)
    • Month 12: Marriage stronger, financial stress minimal

    Key insight: “Personal envelopes gave us autonomy. Shared envelopes forced communication but in a structured way. We stopped fighting because the envelopes showed the truth—not accusations.”


    Story #3: David’s Variable Income Victory

    Background:

    • Freelance graphic designer, age 34
    • Income: $2,000-$6,000/month (highly variable)
    • Problem: Overspent in good months, scrambled in bad months
    • No emergency fund despite good average income

    Before Envelopes:

    • Good month: Spent freely
    • Bad month: Panicked, used credit cards
    • Never felt secure despite decent income
    • Couldn’t build savings

    Envelope System Implementation:
    Strategy:

    • Budgeted to worst-case month ($2,000)
    • Any income above $2,000 = 50% to emergency fund, 50% to extra envelope amounts

    Base envelopes (always funded even in $2,000 month):

    • Groceries: $300
    • Gas: $100
    • Personal: $50
    • Total bare minimum: $450 (rest to fixed bills, taxes, basic savings)

    Results:

    • Month 1 income: $4,200
      • Funded base envelopes: $450
      • Extra $2,200 above minimum:
        • $1,100 to emergency fund
        • $1,100 to enhanced envelopes (better groceries, some dining out, entertainment)
    • Month 3 income: $2,300
      • Funded base envelopes: $450
      • Extra $300 above minimum:
        • $150 to emergency fund
        • $150 to slightly enhanced envelopes
    • Month 5 income: $5,800
      • Funded base envelopes: $450
      • Extra $3,800:
        • $1,900 to emergency fund
        • $1,900 to enhanced envelopes + special purchase saved for

    Results after 12 months:

    • Emergency fund: $14,500 (never had more than $1,000 before)
    • Stress level: Dramatically reduced
    • Never used credit card once
    • Business investment made from good month excess

    Key insight: “Knowing my bare-minimum envelopes would always be funded gave me security. Good months felt like bonuses, not the new normal to adjust lifestyle to.”


    Story #4: Sarah’s Grocery Budget Breakthrough

    Background:

    • Stay-at-home mom, family of 4
    • Household income: $65,000
    • Problem: Grocery budget consistently $900-1,000/month, target was $600
    • Multiple store trips per week, constant overspending

    Before Envelopes:

    • Vague idea of grocery budget
    • Multiple trips per week
    • “Just grabbing a few things” that added up
    • Using debit card, easy to overspend

    Envelope System Implementation:
    Setup:

    • Single grocery envelope: $650/month (realistic middle ground)
    • Weekly sub-envelopes: $162.50 × 4 weeks
    • Rule: Only shop once per week, only with cash

    Supporting changes:

    • Started meal planning Sunday nights
    • Shopped with list only
    • Left debit card at home
    • Made it a game to come under budget

    Results:

    • Week 1: Spent $155 (under budget!)
    • Week 2: Spent $168 (slight over, but rolled from week 1)
    • Month 1: Total spent $622, $28 under budget
    • Month 3: Consistently under $650, rolling $50-75/month to savings
    • Month 6: Grocery spending stabilized at $580-620/month
    • Year 1: Saved $3,600 compared to previous grocery spending

    Additional benefits:

    • Less food waste (planning ahead)
    • Healthier eating (fewer impulse buys)
    • Kids learned about budget limits
    • Sense of achievement each successful week

    Key insight: “Having to physically count out cash made me ruthlessly evaluate every item. ‘Do we really need this?’ became automatic. Also, limited trips meant better planning.”
  • Emergency Fund Guide: How Much to Save and Where to Keep It

    Emergency Fund Guide: How Much to Save and Where to Keep It

    Table of Contents

    1. Introduction
    2. What is an Emergency Fund?
    3. Why You Absolutely Need an Emergency Fund
    4. How Much Should You Have in Your Emergency Fund?
    5. Calculating Your Personal Emergency Fund Target
    6. Where to Keep Your Emergency Fund
    7. Best Emergency Fund Accounts in 2024
    8. How to Build Your Emergency Fund Fast
    9. Emergency Fund vs. Savings Account: What’s the Difference?
    10. When to Use Your Emergency Fund (And When Not To)
    11. What to Do After Using Your Emergency Fund
    12. Common Emergency Fund Mistakes to Avoid
    13. Emergency Fund for Different Life Situations
    14. Frequently Asked Questions
    15. Conclusion

    Introduction {#introduction}

    Imagine this scenario: Your car breaks down on the way to work. The repair estimate? $1,200. Or your tooth cracks and needs an emergency crown—$1,500 out of pocket. Or you receive a pink slip and suddenly face unemployment.

    For 63% of Americans, according to a 2024 Forbes Advisor survey, these scenarios would trigger a financial crisis. They simply don’t have enough savings to cover an unexpected $1,000 expense without resorting to credit cards, loans, or borrowing from family.

    This financial vulnerability doesn’t just cost money—it costs sleep, peace of mind, and sometimes even relationships. The constant worry about “what if something goes wrong” creates a background stress that affects every area of life.

    The solution? A fully funded emergency fund.

    An emergency fund is your financial safety net—a dedicated pool of money set aside specifically for unexpected expenses and emergencies. It’s not for vacations, not for holiday shopping, and not for that great deal you found online. It exists for one purpose: protecting you when life throws a curveball.

    In this comprehensive guide, you’ll discover:

    • Exactly how much you need in your emergency fund (hint: it’s not the same for everyone)
    • Where to keep this money for both safety and growth
    • How to build your fund quickly, even on a tight budget
    • What truly counts as an “emergency” (and what doesn’t)
    • The best high-yield accounts to maximize your emergency savings

    By the end of this article, you’ll have a clear, actionable plan to build financial security and eliminate the anxiety of living paycheck to paycheck.

    Your journey to financial peace starts here.


    What is an Emergency Fund? {#what-is}

    An emergency fund is a dedicated savings account containing money reserved exclusively for unexpected expenses and financial emergencies. Think of it as financial insurance you create for yourself.
    Key Characteristics of an Emergency Fund:

    1. Separate from Regular Savings
    Your emergency fund should be in a completely separate account from your day-to-day checking and regular savings. This physical separation prevents accidental spending.

    2. Easily Accessible (Liquid)
    You should be able to access this money within 24-48 hours without penalties. Unlike investments or CDs with withdrawal penalties, emergency funds prioritize accessibility over returns.

    3. Reserved for True Emergencies
    This money has one job: protecting you from financial disasters. It’s not for planned expenses, wants, or opportunities—only genuine emergencies.

    4. Fully Funded Before Aggressive Investing
    Financial experts universally agree: build at least a starter emergency fund before investing heavily in the market.

    What an Emergency Fund is NOT:

    ❌ Not an investment account – Emergency funds prioritize safety and accessibility over high returns

    ❌ Not a vacation fund – Planned expenses deserve their own savings category

    ❌ Not an opportunity fund – “This deal is too good to pass up” isn’t an emergency

    ❌ Not a shopping fund – Even if it’s on sale, it’s not an emergency

    ❌ Not retirement savings – These serve completely different purposes with different timelines

    The Psychology of Emergency Funds

    Beyond the practical benefits, emergency funds provide something invaluable: peace of mind.

    Dr. Brad Klontz, financial psychologist and researcher, explains: “Having an adequate emergency fund is one of the strongest predictors of financial wellness and reduced money-related stress. It’s not just about the money—it’s about the psychological safety it provides.”

    A 2023 study in the Journal of Financial Therapy found that people with emergency funds covering 3+ months of expenses reported:

    • 52% lower financial stress
    • Better sleep quality
    • Improved relationship satisfaction
    • Greater overall life satisfaction
    • More confidence in financial decision-making

    Your emergency fund isn’t just dollars in a bank—it’s confidence, security, and freedom from financial anxiety.


    Why You Absolutely Need an Emergency Fund {#why-need}

    If you’re tempted to skip building an emergency fund and jump straight to investing or debt payoff, understanding the “why” is crucial.

    1. Life is Unpredictable (And Expensive)

    Statistics paint a clear picture of financial uncertainty:
    Medical Emergencies:

    • 66% of bankruptcies in the U.S. involve medical debt (American Journal of Public Health, 2024)
    • Average ER visit costs $1,389 (Kaiser Family Foundation)
    • Even with insurance, surprise medical bills average $750-$2,000

    Vehicle Repairs:

    • Average American car is 12.5 years old
    • Transmission repair: $1,500-$3,500
    • Engine repair: $2,500-$4,000
    • Major systems tend to fail unexpectedly

    Home Repairs:

    • HVAC replacement: $3,000-$7,000
    • Roof repair: $400-$1,500
    • Plumbing emergency: $150-$800
    • Water heater replacement: $900-$1,500

    Job Loss:

    • Average time to find new employment: 3-6 months
    • Unemployment benefits replace only 40-50% of income
    • Benefits take 2-4 weeks to begin

    Without an emergency fund, these situations force you into bad financial decisions:

    • High-interest credit card debt
    • Predatory payday loans
    • 401(k) early withdrawals (with penalties)
    • Borrowing from family
    • Selling assets at unfavorable times

    2. Prevents Debt Spiral

    Consider the math of emergency-related debt:

    Scenario: $1,500 car repair without emergency fund

    Option 1: Credit card (21% APR, minimum payments)

    • If you pay minimums only: $2,447 total paid
    • Time to payoff: 7 years
    • Extra cost: $947 in interest

    Option 2: Emergency fund

    • Withdraw $1,500
    • Rebuild over next 3-4 months
    • Total cost: $1,500
    • Extra cost: $0

    The difference: $947 and years of stress

    An emergency fund isn’t just about having money—it’s about avoiding expensive debt that can take years to escape.

    3. Protects Your Financial Progress

    Imagine this common scenario:

    You’ve been aggressively paying off debt. After 18 months, you’ve paid off $12,000 and only have $5,000 left. Then your transmission dies.

    Without emergency fund:

    • Put $2,800 repair on credit card
    • Debt jumps back up to $7,800
    • Psychological defeat
    • Months of progress erased

    With emergency fund:

    • Pay $2,800 from emergency savings
    • Debt remains at $5,000
    • Rebuild emergency fund over 2-3 months
    • Progress maintained

    Your emergency fund protects the financial progress you’ve worked so hard to achieve.

    4. Enables Better Career Decisions

    Job security feels different when you have 6 months of expenses saved:

    Without emergency fund:

    • Stuck in toxic work environment (can’t afford to quit)
    • Can’t negotiate from position of strength
    • Must accept first job offer, regardless of fit
    • Fear prevents career risks

    With emergency fund:

    • Can leave unhealthy workplace if needed
    • Negotiate confidently (you have time to find alternatives)
    • Can be selective about opportunities
    • Freedom to pursue better-fit positions
    • Ability to invest in career transitions

    Financial security creates career freedom.

    5. Reduces Relationship Stress

    Money is consistently cited as a top cause of relationship conflict. A SunTrust Bank study found that:

    • 35% of couples experiencing relationship stress cite money as the primary cause
    • Couples with emergency funds report 64% fewer money-related arguments
    • Financial security correlates with relationship satisfaction

    An emergency fund removes a major source of couple conflict by providing shared security.

    6. Protects Against Economic Downturns

    During the 2020 pandemic:

    • 22 million Americans lost jobs in 2 months
    • Those with emergency funds weathered significantly better
    • Those without faced evictions, hunger, and extreme hardship

    During the 2008 recession:

    • Unemployment reached 10%
    • Those with 6+ months saved had time to find quality positions
    • Those without took desperate measures with long-term consequences

    Economic uncertainty isn’t “if”—it’s “when.” Your emergency fund is protection against forces beyond your control.


    How Much Should You Have in Your Emergency Fund? {#how-much}

    This is the million-dollar question—or more accurately, the 3-to-12-month question. The answer depends on your specific situation.

    The Standard Recommendations

    Financial Expert Guidelines:

    Dave Ramsey: $1,000 starter emergency fund, then 3-6 months of expenses after becoming debt-free

    Suze Orman: 8-12 months of expenses (more conservative)

    The Balance/NerdWallet: 3-6 months of expenses for most people

    Vanguard Research: 3-6 months for dual-income households, 6-12 months for single-income

    The truth? There’s no universal “right” amount. Your ideal emergency fund depends on multiple factors.

    Factors That Determine Your Target Amount

    1. Income Stability

    Highly Stable (3-4 months):

    • Government employee with tenure
    • Tenured professor
    • Established business with consistent revenue
    • Two high-earning professionals

    Moderate Stability (4-6 months):

    • Corporate job in stable industry
    • Dual-income household
    • Specialized skills in demand
    • Strong job market in your field

    Variable/Unstable (6-12 months):

    • Commission-based income
    • Freelancer/Contractor
    • Seasonal work
    • Startup employee
    • Single income household
    • Volatile industry
    • Niche specialized field (longer to find new position)

    2. Number of Income Earners

    Single income household: Higher target (6-12 months)

    • If sole earner loses job, household income drops to zero
    • No backup income source
    • Greater risk requires greater cushion

    Dual income household: Lower target acceptable (3-6 months)

    • If one loses job, other income continues
    • Built-in diversification
    • Statistical unlikelihood both lose jobs simultaneously

    3. Health Considerations

    Excellent health, good insurance: Standard target

    Chronic conditions, high deductibles, or dependents with medical needs: Add 1-2 months to target

    • Higher likelihood of medical expenses
    • Larger potential out-of-pocket costs
    • Insurance gaps and deductibles

    4. Job Market Realities

    How long would it take to find equivalent employment?

    Quick replacement (3-4 months):

    • High-demand skills
    • Multiple opportunities in area
    • Transferable skills
    • Strong network

    Longer replacement (6-9 months):

    • Specialized niche
    • Limited opportunities in geography
    • Senior-level positions
    • Academic positions

    Extended search (9-12 months):

    • Highly specialized
    • Geographic constraints
    • Competitive fields
    • Executive positions

    5. Fixed Obligations

    Higher fixed costs = larger emergency fund needed

    Consider:

    • Mortgage/rent amount
    • Dependent care costs
    • Health insurance premiums (if job loss means losing coverage)
    • Debt obligations
    • Medical needs
    • Insurance requirements

    Quick Reference Guide

    Your Situation Recommended Target
    Dual income, stable jobs, good health 3-4 months expenses
    Single income OR variable income 6 months expenses
    Self-employed/Freelancer 6-12 months expenses
    Single income + health concerns 8-9 months expenses
    Retiree (pre-Medicare) 12-24 months expenses
    High earner in niche field 9-12 months expenses
    Starting a business 12-18 months expenses

    The Starter Emergency Fund Approach

    Many financial experts recommend a two-phase approach:

    Phase 1: Starter Emergency Fund ($1,000-$2,000)

    • Build this FIRST, before aggressive debt payoff
    • Handles small emergencies (minor car repair, urgent dental work, appliance replacement)
    • Prevents derailing debt payoff progress
    • Achievable quickly (creates momentum)

    Phase 2: Full Emergency Fund (3-12 months)

    • Build after paying off high-interest debt
    • Provides complete protection
    • Allows confidence and peace of mind
    • Enables better financial decisions

    Internal Link: Learn how to allocate funds effectively with our “Zero-Based Budgeting Explained: Take Control of Every Dollar” guide


    Calculating Your Personal Emergency Fund Target {#calculator}

    Let’s calculate YOUR specific emergency fund target with a step-by-step process.

    Step 1: Calculate Monthly Essential Expenses

    List only expenses you’d still need to pay if you lost your income:

    Housing:

    • Rent/Mortgage: $_______
    • Property tax (if not in mortgage): $_______
    • HOA fees: $_______
    • Home/Renter’s insurance: $_______

    Utilities:

    • Electricity: $_______
    • Gas/Heating: $_______
    • Water/Sewer: $_______
    • Internet (basic tier): $_______
    • Phone (basic plan): $_______

    Food:

    • Groceries (lean budget): $_______
    • (Skip restaurants—not essential)

    Transportation:

    • Car payment: $_______
    • Auto insurance: $_______
    • Gas (for job hunting): $_______
    • Public transportation: $_______

    Insurance & Healthcare:

    • Health insurance premium: $_______
    • Prescriptions: $_______
    • Regular medical needs: $_______
    • Life insurance: $_______

    Minimum Debt Payments:

    • Credit card minimums: $_______
    • Student loan minimums: $_______
    • Personal loan minimums: $_______
    • Any other debt minimums: $_______

    Essential Only:

    • Childcare (if needed for job search): $_______
    • Pet food/basic care: $_______

    DO NOT INCLUDE:

    • Entertainment
    • Dining out
    • Subscriptions (Netflix, etc.)
    • Gym memberships
    • Hobbies
    • Clothing (except emergency replacements)
    • Savings/investing
    • Extra debt payments

    TOTAL MONTHLY ESSENTIAL EXPENSES: $_______

    Step 2: Determine Your Target Multiplier

    Based on the factors we discussed, choose your multiplier:

    Choose the HIGHEST number that applies to you:

    •  Dual income, stable, excellent health = 3 months
    •  Dual income, one variable income = 4 months
    •  Single income, stable job = 5 months
    •  Single income OR variable income = 6 months
    •  Self-employed/Freelancer = 9 months
    •  Health concerns or high medical costs = Add 2 months to above
    •  Niche specialized field = Add 2 months to above
    •  Single parent = Add 1 month to above

    My multiplier: _______ months

    Step 3: Calculate Your Full Emergency Fund Target

    Monthly Essential Expenses × Target Multiplier = Emergency Fund Goal

    Example Calculation:

    Maria’s situation:

    • Monthly essential expenses: $3,200
    • Single income household
    • Stable corporate job
    • Good health
    • Target: 6 months

    Calculation: $3,200 × 6 = $19,200 emergency fund target

    Your Calculation:

    $_______ × _______ = $_______
    (Monthly expenses) × (Multiplier) = (Emergency Fund Goal)

    Step 4: Set Your Starter Fund Target

    Before building your full fund, set a starter target:

    Starter Emergency Fund Options:

    • Minimum: $1,000
    • Better: $1,500
    • Ideal starter: $2,000
    • One month of expenses (whichever is higher)

    My starter fund target: $_______

    Step 5: Create Your Timeline

    To starter fund:

    Current emergency savings: $_______
    Starter fund target: $_______
    Amount needed: $_______

    Realistic monthly contribution: $_______

    Months to starter fund: _______ months

    To full fund (after starter):

    Full fund target: $_______
    Starter fund: $_______
    Additional needed: $_______

    Monthly contribution: $_______

    Months to full fund: _______ months

    Total timeline: _______ months

    Internal Link: Need to find money for emergency fund contributions? See our “How to Save Money Fast: 50+ Proven Ways to Cut Expenses” guide


    Where to Keep Your Emergency Fund {#where-to-keep}

    Your emergency fund needs three critical characteristics:

    1. Safety (FDIC insured, no risk of loss)
    2. Accessibility (available within 24-48 hours)
    3. Reasonable growth (earning some interest, but not primary goal)

    Where TO Keep Your Emergency Fund

    1. High-Yield Savings Account ⭐ BEST OPTION for most people

    Pros:

    • FDIC insured up to $250,000
    • Easy access (usually 1-2 business days to transfer)
    • Currently earning 4.0-5.5% APY (as of 2024)
    • No market risk
    • Online access and management
    • Often no minimum balance
    • Separate from checking (prevents accidental spending)

    Cons:

    • Interest rates vary with Fed policy
    • May have transfer limits
    • Slightly delayed access (not instant like checking)

    Best for: Most people building emergency funds

    Top providers (2024):

    • Marcus by Goldman Sachs
    • Ally Bank
    • American Express Personal Savings
    • Discover Online Savings
    • CIT Bank

    Example earnings:
    $10,000 emergency fund at 5.0% APY = $500 per year in interest

    2. Money Market Account

    Pros:

    • FDIC insured
    • Slightly higher interest than regular savings (typically)
    • Check writing ability (limited)
    • Easy access
    • Often includes debit card

    Cons:

    • May require higher minimum balance ($1,000-$10,000)
    • Limited transactions per month (typically 6)
    • Interest rates comparable to high-yield savings

    Best for: Larger emergency funds ($10,000+) or those wanting check-writing access

    3. Money Market Mutual Fund

    Pros:

    • Higher yields than savings accounts (sometimes)
    • Very liquid
    • Low risk

    Cons:

    • NOT FDIC insured (though very stable)
    • Can lose value (rare but possible)
    • May have minimum investment
    • Usually requires brokerage account

    Best for: Sophisticated investors comfortable with minimal risk

    4. Short-Term CD Ladder (Advanced strategy)

    Pros:

    • FDIC insured
    • Locked-in rates
    • Typically higher rates than savings
    • Disciplined approach prevents spending

    Cons:

    • Early withdrawal penalties
    • Less accessibility
    • More complex to set up
    • Rates may be lower than high-yield savings in 2024

    How CD laddering works:

    Divide emergency fund into portions with staggered maturity dates:

    • $2,000 in 3-month CD
    • $2,000 in 6-month CD
    • $2,000 in 9-month CD
    • $2,000 in 12-month CD

    Every 3 months, one matures. Renew for 12 months. After 12 months, you have access to $2,000 every 3 months with no penalty.

    Best for: Disciplined savers with established emergency funds who want to maximize interest

    Where NOT to Keep Your Emergency Fund

    ❌ Regular Checking Account

    Problems:

    • Too easy to spend accidentally
    • Virtually no interest earned
    • Mental accounting doesn’t separate emergency money from regular money
    • Temptation to use for non-emergencies

    ❌ Stock Market/Index Funds

    Problems:

    • Market can drop 20-40% exactly when you need the money
    • Selling during downturn locks in losses
    • Takes 3-5 days to access
    • Defeats purpose of emergency fund (stability)

    Real example: Someone with $15,000 emergency fund invested in S&P 500 in February 2020 would have seen it drop to $9,000 in March 2020—exactly when they might have needed it due to pandemic job loss.

    ❌ Cryptocurrency

    Problems:

    • Extreme volatility (can lose 50%+ in days)
    • Not FDIC insured
    • Can take days to convert to cash
    • Platform failures and hacks
    • Completely inappropriate for emergency funds

    ❌ Under the Mattress (Cash at Home)

    Problems:

    • No FDIC protection (if stolen or destroyed, it’s gone)
    • Inflation erodes value
    • Earns zero interest
    • Fire/theft/flood risk
    • Too easy to dip into

    Small cash at home ($200-500) is fine for immediate emergencies when banks are closed

    ❌ Certificate of Deposit (Non-Laddered)

    Problems:

    • Early withdrawal penalties (often 3-6 months interest)
    • Defeats accessibility purpose
    • Current rates often lower than high-yield savings

    ❌ Retirement Accounts (401k, IRA)

    Problems:

    • 10% early withdrawal penalty (if under 59½)
    • Income taxes on withdrawal
    • Loses tax-advantaged growth
    • Should be absolute last resort

    Example cost: Withdrawing $5,000 from 401k:

    • $500 penalty (10%)
    • $1,100 taxes (22% bracket)
    • Total cost: $1,600
    • You receive only $3,400 of the $5,000

    Best Emergency Fund Accounts in 2024 {#best-accounts}

    [IMAGE PLACEMENT HERE]

    AI Image Prompt:
    “Best savings accounts comparison table, professional chart showing top 5 high-yield savings accounts with APY rates, features, and pros/cons, clean financial comparison design, trustworthy and informative style, modern banking concept”

    Here are the top high-yield savings accounts for emergency funds as of 2024. Note: Rates change frequently—verify current rates before opening.

    Top 5 High-Yield Savings Accounts

    1. Marcus by Goldman Sachs Online Savings

    APY: 5.30% (as of 2024)
    Minimum Deposit: $0
    Monthly Fees: $0
    FDIC Insured: Yes

    Pros:

    • Highly competitive rate
    • No fees
    • No minimum balance
    • Trusted major bank backing
    • Easy transfers
    • Excellent customer service reputation

    Cons:

    • No physical branches
    • No checking account option
    • Transfers take 2-3 business days

    Best for: Straightforward emergency fund with excellent rate


    2. Ally Bank Online Savings Account

    APY: 5.25%
    Minimum Deposit: $0
    Monthly Fees: $0
    FDIC Insured: Yes

    Pros:

    • Consistently competitive rates
    • Excellent mobile app
    • 24/7 customer service
    • Can open checking account for faster access
    • Buckets feature (organize savings into categories)
    • No minimum balance

    Cons:

    • Slightly lower rate than some competitors
    • No physical branches

    Best for: Those wanting full-service online banking with checking + savings


    3. American Express Personal Savings

    APY: 5.30%
    Minimum Deposit: $0
    Monthly Fees: $0
    FDIC Insured: Yes

    Pros:

    • Top-tier rate
    • Trusted brand
    • No fees or minimums
    • Easy to link to external accounts
    • Clean, simple interface

    Cons:

    • No checking account option
    • Cannot deposit cash
    • 2-3 day transfer times

    Best for: Those prioritizing maximum interest rate


    4. Discover Online Savings Account

    APY: 5.25%
    Minimum Deposit: $0
    Monthly Fees: $0
    FDIC Insured: Yes

    Pros:

    • Excellent rate
    • Award-winning customer service
    • Can open money market or CDs
    • Cash back debit card available
    • Long-standing reputation

    Cons:

    • No physical branches
    • Standard transfer times

    Best for: Those wanting options beyond just savings account


    5. CIT Bank Savings Connect

    APY: 5.05%
    Minimum Deposit: $100
    Monthly Fees: $0
    FDIC Insured: Yes

    Pros:

    • Competitive rate
    • Low minimum to open
    • No monthly fees
    • Multiple account options

    Cons:

    • Slightly lower rate than top competitors
    • Less well-known brand
    • Requires $100 to open

    Best for: Those comfortable with smaller online banks


    Money Market Account Options

    Vanguard Cash Plus Account

    APY: 5.28%
    Minimum: $0
    Fees: $0

    Features:

    • Brokerage integration
    • Very competitive rate
    • Check writing
    • FDIC insured through partner banks

    Best for: Investors who also use Vanguard for investing


    Fidelity Cash Management Account

    APY: 5.24%
    Minimum: $0
    Fees: $0

    Features:

    • Debit card included
    • Check writing
    • ATM fee reimbursements
    • FDIC insured

    Best for: Fidelity customers or those wanting checking-like features


    How to Choose the Right Account

    Ask yourself:

    1. Do I need a debit card or checks?
      • Yes → Money market account or Ally/Discover
      • No → Highest-rate savings account
    2. Do I have other accounts with any of these banks?
      • Having checking + savings at same bank speeds transfers
      • Consider Ally or Discover for full banking relationship
    3. How important is brand recognition?
      • Want established name → Marcus (Goldman Sachs) or AmEx
      • Comfortable with online-only → Any top-rated option
    4. Will I maintain the minimum balance?
      • Check minimum requirements
      • Most top accounts have $0 minimum
    5. How often will I need to access this money?
      • Rarely → Highest rate savings
      • Occasionally → Money market with check/debit access

    Pro Tip: The difference between 5.25% and 5.30% on a $10,000 emergency fund is only $5/year. Don’t overthink it. Choose a reputable FDIC-insured account with a competitive rate and good customer service.


    How to Build Your Emergency Fund Fast {#build-fast}

    Building an emergency fund can feel overwhelming, especially if you’re starting from zero. Here are proven strategies to accelerate the process.

    Strategy 1: Start with a Micro-Goal

    The psychology of starting:

    $10,000+ emergency fund goal feels impossible when you have $0. Break it into achievable milestones:

    Milestone approach:

    •  $250 (Micro-emergency covered)
    •  $500 (Small car repair possible)
    •  $1,000 (Starter emergency fund complete) 🎉
    •  $2,500 (Quarter-way there)
    •  $5,000 (Halfway to moderate goal)
    •  $7,500 (Three-quarters)
    •  $10,000 (Full emergency fund complete!) 🎊

    Celebrate each milestone. Momentum builds with small wins.

    Strategy 2: Automate Your Savings

    Manual saving fails. Automation succeeds.

    Set up these automations:

    Option 1: Paycheck splitting
    If your employer allows, direct deposit a portion straight to emergency fund:

    • 80% → Checking account
    • 20% → Emergency fund savings

    Option 2: Automatic transfer
    Set up recurring transfer the day after payday:

    • Payday: Friday
    • Auto-transfer Saturday: $200 to emergency fund

    Why automation works:

    • Removes willpower from equation
    • “Pay yourself first” mentality
    • You adapt spending to what remains
    • Consistency beats motivation

    Research finding: A 2023 Employee Benefit Research Institute study found automated savers accumulate 6x more emergency savings than manual savers over 3 years.

    Strategy 3: Redirect One Expense

    Instead of cutting multiple things, redirect one significant expense entirely to emergency fund:

    Examples:

    • Cancel $200 car payment (pay off car) → $200/month to emergency fund
    • Cut cable TV ($120/month) → To emergency fund
    • Stop dining out ($300/month) → To emergency fund
    • Cancel unused gym membership ($50/month) → To emergency fund

    Timeline impact:

    $200/month = $2,400/year

    • Starter fund ($1,000): 5 months
    • 3-month fund ($9,000): 3.75 years

    $400/month = $4,800/year

    • Starter fund ($1,000): 2.5 months
    • 3-month fund ($9,000): 22 months

    Internal Link: Find expenses to cut with our “How to Save Money Fast: 50+ Proven Ways to Cut Expenses” guide

    Strategy 4: Windfall Allocation Rule

    When unexpected money comes in, allocate a significant portion to emergency fund:

    Sources of windfalls:

    • Tax refund
    • Work bonus
    • Gift money
    • Inheritance
    • Garage sale proceeds
    • Selling unused items
    • Freelance project payment

    Recommended allocation:

    • 50% to emergency fund
    • 25% to debt (if applicable)
    • 25% for something enjoyable

    Example:
    $2,000 tax refund:

    • $1,000 → Emergency fund (major boost!)
    • $500 → Extra debt payment
    • $500 → Something you want

    This balanced approach prevents “all or nothing” thinking while making substantial progress.

    Strategy 5: Aggressive Starter Fund Push

    30-Day Emergency Fund Challenge:

    For one month, take extreme measures to rapidly build starter fund:

    Income boosting:

    • Overtime at work
    • Weekend side gig
    • Sell unused items (eBay, Facebook Marketplace, yard sale)
    • Freelance project
    • Return unused items for refunds

    Expense cutting:

    • No restaurant meals (30 days)
    • No online shopping
    • Pack all lunches
    • Free entertainment only
    • Pause subscriptions for one month

    Realistic goal: Many people save $500-$1,500 in one focused month.

    Why this works:

    • Short timeframe feels achievable
    • Creates momentum
    • Builds confidence
    • Establishes habits
    • Gets you to $1,000 quickly

    Strategy 6: Round-Up Programs

    Use technology to save automatically with round-ups:

    How it works:

    • Purchase coffee for $4.50
    • App rounds to $5.00
    • $0.50 goes to savings

    Apps offering this:

    • Acorns (investment app with round-ups)
    • Chime (automatic savings)
    • Bank of America Keep the Change
    • Qapital (customizable saving rules)

    Typical results: $50-$150/month in painless savings

    Not a complete strategy, but excellent supplement.

    Strategy 7: The Split Deposit Method

    For those struggling to save:

    Week 1: 95% spending, 5% savings
    Week 2: 93% spending, 7% savings
    Week 3: 91% spending, 9% savings
    Week 4: 90% spending, 10% savings

    Gradually increase savings percentage so adjustment is gradual, not shocking.

    By month 3, you might be at 20% savings rate without the pain of sudden drastic cuts.

    Strategy 8: Interest and Raise Allocation

    Capture increases before lifestyle adjusts:

    Got a raise?
    Before you adjust your lifestyle, immediately increase emergency fund contribution by at least 50% of the raise.

    Example:

    • Raise: $200/month
    • Increase spending: $100/month
    • Increase savings: $100/month

    You still improve lifestyle while accelerating savings.

    High-yield account interest:
    Keep all interest earned in the emergency fund (reinvest automatically).

    On $5,000 at 5% APY, that’s $250/year staying in the fund.

    Strategy 9: No-Spend Challenges

    One category, one month:

    Choose one discretionary category and spend $0 for 30 days:

    Options:

    • No restaurants/takeout
    • No clothing purchases
    • No online shopping
    • No entertainment spending
    • No coffee shops

    All money “saved” → Emergency fund

    Typical results: $200-$500 saved in one month

    Quick-Build Summary

    Fastest path to $1,000 starter fund:

    Month 1:

    • Set up $200/month auto-transfer
    • 30-day spending challenge (save $300)
    • Sell unused items ($200)
    • Round-up app ($50)
    • Tax refund allocation ($250)
      Total: $1,000 ✓

    Track your progress visually:
    Create a chart, use an app, or color in a thermometer graphic. Visual progress increases motivation by 73% according to behavioral psychology research.

    Internal Link: Use our “Zero-Based Budgeting Explained: Take Control of Every Dollar” method to find savings automatically


    Emergency Fund vs. Savings Account: What’s the Difference? {#vs-savings}

    Many people confuse emergency funds with general savings. Understanding the distinction is crucial.

    Emergency Fund

    Purpose: Protection from financial disasters
    Timeline: Indefinite (always maintained)
    Accessibility: High (1-2 day access)
    Growth: Secondary priority
    Use Frequency: Rarely (emergencies only)
    Replenishment: Immediate priority after use
    Mental Category: Financial insurance

    Ideal account: High-yield savings account, separate from other money

    Examples of use:

    • Job loss
    • Medical emergency
    • Major car repair
    • Urgent home repair
    • Emergency travel (family crisis)

    General Savings Account

    Purpose: Planned expenses and goals
    Timeline: Specific (save for specific item/event)
    Accessibility: Moderate (can wait for better moment)
    Growth: Important consideration
    Use Frequency: Regular (as goals are reached)
    Replenishment: Based on new goals
    Mental Category: Future consumption

    Ideal account: Can be same or different from emergency fund, possibly higher-yield options

    Examples of use:

    • Vacation
    • New furniture
    • Holiday shopping
    • Wedding
    • Home down payment
    • New car (planned)

    Sinking Funds (Subcategory of Savings)

    Purpose: Predictable irregular expenses
    Timeline: Specific dates (annual, quarterly, etc.)
    Examples:

    • Annual insurance premiums
    • Car registration
    • Property taxes
    • Holiday gifts
    • Annual subscriptions

    How they work:

    • Annual car insurance: $1,200
    • Divide by 12: $100/month
    • Set aside $100/month
    • When bill comes, money is ready

    Side-by-Side Comparison

    Aspect Emergency Fund Savings Account Sinking Funds
    Purpose Financial protection Future goals Known future expenses
    Amount 3-12 months expenses Varies by goal Exact expense amount
    Touch Frequency Very rare Moderate Regular
    Reprioritize? Never Sometimes Rarely
    Account Type Separate, high-yield Can be combined Can be same account
    Emotion Security/peace Excitement Preparedness

    Should They Be in the Same Account?

    Arguments for SEPARATE accounts:

    Pros:

    • Mental accounting (each dollar has clear purpose)
    • Prevents accidentally using emergency fund for non-emergencies
    • Easier to track progress
    • Protects emergency fund integrity

    Best for: People who might be tempted to raid emergency fund for wants


    Arguments for COMBINED account:

    Pros:

    • Simpler (fewer accounts to track)
    • Higher total balance may earn better rates
    • All savings in one place
    • Less administrative overhead

    Requires: Strong discipline and clear tracking system

    Best for: Disciplined savers who can mentally separate purposes


    Recommended approach for most people:

    Account 1: Emergency Fund (Separate, untouchable)

    • 3-12 months expenses
    • High-yield savings
    • Only for true emergencies

    Account 2: Savings Goals (Can have sub-categories)

    • Vacation fund
    • Car fund
    • Home improvement
    • Sinking funds

    Account 3: Checking (Daily spending)

    • Regular bills and expenses
    • Budgeted spending

    This three-account system provides clarity while remaining manageable.

    Internal Link: Learn to allocate between accounts with our “Complete Guide to Budgeting: Build Wealth on Any Income”


    When to Use Your Emergency Fund (And When Not To) {#when-to-use}

    The hardest part of having an emergency fund is knowing when to actually use it. Here’s a comprehensive guide.

    ✅ DEFINITELY Use Your Emergency Fund

    1. Job Loss or Reduced Income

    • Laid off
    • Terminated
    • Hours reduced significantly
    • Business income drops substantially

    Why it qualifies: This is exactly what emergency funds exist for—replacing income.

    Action: Use as needed to cover essential expenses while job hunting. Budget carefully to extend runway.


    2. Medical Emergencies

    • Emergency room visit
    • Urgent surgery
    • Unexpected hospital stay
    • Necessary dental emergency (severe pain, infection, broken tooth)
    • New medical diagnosis requiring immediate treatment

    Why it qualifies: Health cannot wait, and medical debt is expensive.

    Action: Use emergency fund to cover deductibles, copays, and uncovered expenses. Negotiate payment plans but pay what you can upfront.


    3. Essential Home Repairs

    • Broken HVAC (extreme weather)
    • Roof leak causing damage
    • Plumbing emergency (burst pipe, sewer backup)
    • Electrical hazard
    • Broken water heater
    • Pest infestation requiring immediate treatment

    Why it qualifies: Threatens safety, habitability, or will cause worse damage if delayed.

    Action: Get multiple quotes if possible, but don’t delay critical repairs.


    4. Essential Vehicle Repairs

    Qualifies if:

    • Car is your only transportation to work
    • Repair is necessary for safe operation
    • Public transportation not viable alternative

    Examples:

    • Transmission failure
    • Engine problems
    • Brake failure
    • Safety recalls

    Doesn’t qualify if:

    • You have alternative transportation
    • It’s cosmetic
    • Can be delayed without safety risk

    5. Unexpected Essential Travel

    • Family emergency (serious illness, death)
    • Emergency custody issue
    • Legal requirement to appear

    Why it qualifies: Time-sensitive and necessary.

    Action: Book economically, but don’t delay due to cost.


    6. Essential Insurance Deductibles

    • Car accident deductible
    • Home insurance deductible (fire, storm damage)
    • Medical insurance deductible

    Why it qualifies: You’re covered by insurance, but must pay deductible to access coverage.


    ⚠️ MAYBE Use Your Emergency Fund (Situational)

    1. Car Repairs (Non-Critical)

    Use if:

    • Only vehicle
    • Need for work
    • No alternative transportation
    • Repair cost is within reason

    Don’t use if:

    • Cosmetic repair
    • Can delay without safety issue
    • Have alternative transportation
    • Repair exceeds vehicle value

    Better approach: Create a “car repair sinking fund” with monthly contributions to handle these separately.


    2. Appliance Replacement

    Use if:

    • No reasonable alternative
    • Climate extremes (AC in 110°F heat, heat in freezing cold)
    • Health/safety issue (broken refrigerator, no food storage)

    Don’t use if:

    • Can rent/borrow temporarily
    • Can live without temporarily
    • Can finance 0% interest

    Example: Broken washing machine probably doesn’t qualify (can use laundromat). Broken refrigerator in summer might qualify.


    3. Pet Emergency

    Use if:

    • Life-threatening situation
    • Severe suffering
    • Trusted vet recommends immediate treatment

    Don’t use if:

    • Elective procedure
    • Can be delayed
    • Quality of life issue with time to save

    Better approach: Consider pet insurance or dedicated pet emergency fund.


    4. Legal Issues

    Use if:

    • Criminal charges requiring attorney
    • Immediate legal threat (eviction, foreclosure)
    • Child custody emergency

    Don’t use if:

    • Civil matter that can wait
    • Can access legal aid
    • Optional legal action

    ❌ DO NOT Use Your Emergency Fund

    1. Vacations
    Never. No exceptions. Vacations are wonderful but planned expenses, not emergencies.

    Better approach: Create separate vacation fund.


    2. Holidays and Gifts
    Christmas, birthdays, and weddings happen every year. Not emergencies.

    Better approach: Sinking fund ($100-150/month set aside monthly).


    3. Wants and Upgrades

    • New TV (even if current one broke—can wait)
    • Furniture
    • Clothing (except immediate need for work/interview)
    • Hobby equipment
    • Gadgets

    Why not: These are preferences, not necessities.


    4. Sales and “Great Deals”

    • “50% off sale ends today!”
    • “Limited time offer!”
    • “Investment opportunity!”

    Why not: Emergency funds are for emergencies, not opportunities.

    Truth: There will always be another sale.


    5. Routine Expenses

    • Regular bills
    • Groceries
    • Gas
    • Expected annual expenses (insurance premiums, registration)

    Why not: These should be in your regular budget or sinking funds.

    If you’re using emergency fund for routine expenses, you have a budget problem, not an emergency.


    6. Helping Others
    This is controversial, but important:

    • Lending to friends/family
    • Bailing someone out
    • Covering someone else’s emergency

    Why not: Protect your own oxygen mask first. If you deplete your emergency fund helping others, who helps you in your emergency?

    Alternative: Help in non-financial ways or only give what you can afford to lose.


    7. Debt Payment

    • Extra credit card payment
    • Student loan payoff
    • Mortgage principal

    Why not: Emergency fund takes priority over extra debt payment. Keep it intact for actual emergencies.

    Exception: Once you have FULL emergency fund (3-12 months), you might choose to use excess beyond your target for debt payoff.


    The Emergency Fund Decision Flowchart

    Ask these questions:

    Question 1: Is this unexpected?

    • No → Not an emergency (should be budgeted)
    • Yes → Continue

    Question 2: Is this urgent (cannot wait 1-2 months)?

    • No → Save up for it separately
    • Yes → Continue

    Question 3: Is this essential (need, not want)?

    • No → Do not use emergency fund
    • Yes → Continue

    Question 4: Are there alternatives to using cash?

    • 0% financing available → Consider that instead
    • Insurance will cover it → Use insurance
    • Can borrow item temporarily → Do that
    • No good alternatives → Continue

    Question 5: Is the cost reasonable?

    • Getting multiple quotes if possible
    • Not overpaying due to panic
    • Necessary scope of repair/purchase

    If yes to all → This qualifies as appropriate emergency fund use


    The Gray Areas

    Some situations aren’t clearly emergency or not:

    Scenario: Car needs $800 repair, have $1,200 in starter emergency fund

    Considerations:

    • Do you need car for work? (Probably use fund)
    • Is public transit available? (Maybe avoid using fund)
    • Can you carpool temporarily? (Maybe avoid using fund)

    Recommended: Use fund if truly needed, but replenish ASAP.


    Scenario: Friend’s wedding destination, $1,500 to attend

    Answer: Not an emergency. Save separately or politely decline.

    Weddings are planned events. If invited, you have time to save. Friendship doesn’t require financial hardship.


    Scenario: Appliance breaks but 0% financing available for 18 months

    Recommended approach:

    • Take the 0% financing
    • Set up auto-payment from emergency fund monthly
    • Keeps emergency fund intact for true emergencies
    • No interest cost
    • Better financial flexibility

    When in Doubt

    Ask yourself: “If I use this money, will I be vulnerable if a true emergency happens next month?”

    If yes → Find alternative solution

    Your emergency fund’s primary job is keeping you safe. Preserve it fiercely.


    What to Do After Using Your Emergency Fund {#after-using}

    You’ve had a legitimate emergency and used your emergency fund. Now what?
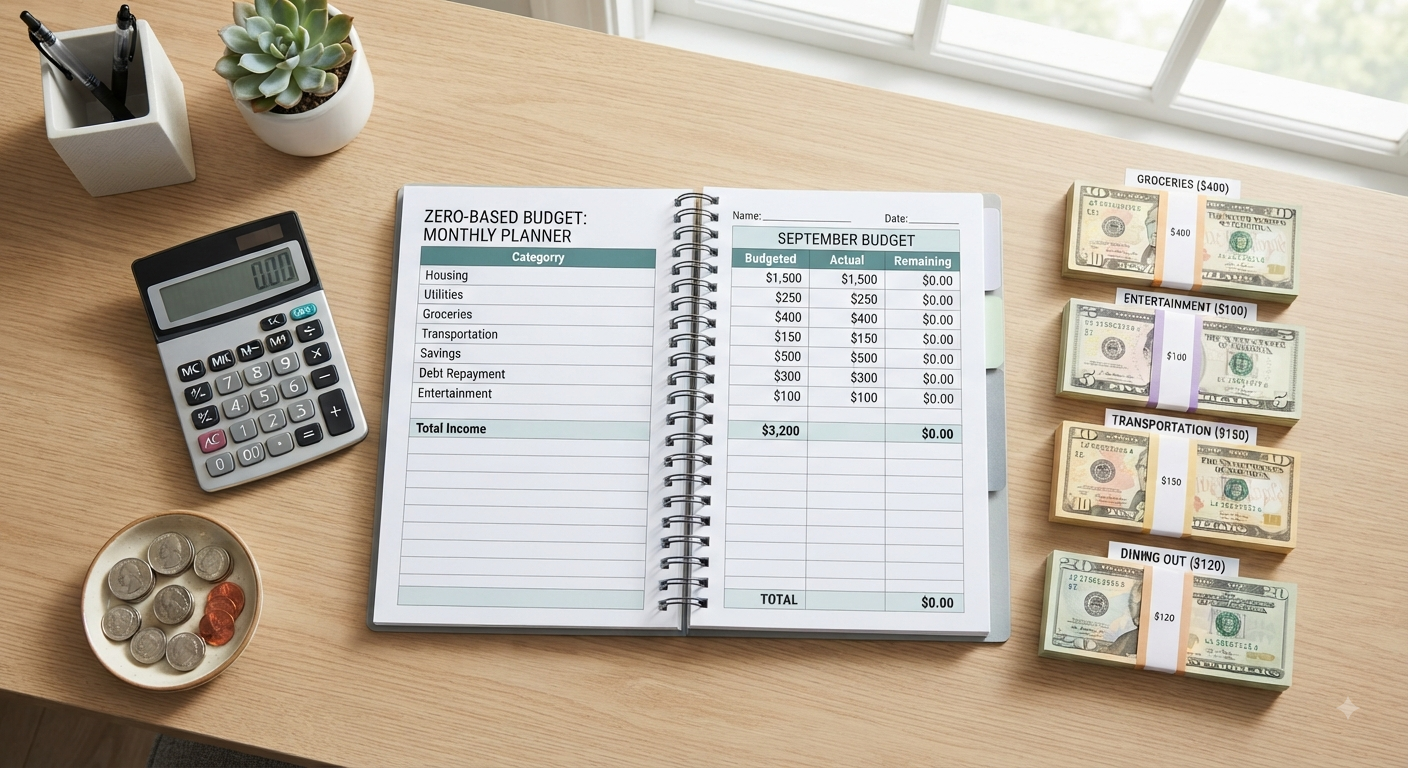
    Step 1: Acknowledge Success (Yes, Success!)

    Your emergency fund did its job. This is exactly why you built it.

    Many people feel defeated after using their emergency fund. Reframe this:

    ❌ “I failed—I had to use my emergency fund”
    ✅ “My emergency fund protected me from debt and financial disaster”

    You didn’t go into debt. You didn’t borrow at high interest. You didn’t raid your retirement. You didn’t panic.

    That’s financial success.

    Step 2: Assess the Damage

    Calculate exactly how much you withdrew:

    Example:

    • Emergency fund before: $8,000
    • Emergency expense: $2,500
    • Remaining: $5,500
    • Need to rebuild: $2,500

    Be specific. Write it down.

    Step 3: Immediate Adjustment

    Until your emergency fund is fully rebuilt:

    Pause or reduce:

    • Extra debt payments (pay minimums only)
    • Retirement contributions (except employer match)
    • Other savings goals
    • Discretionary spending

    Redirect to emergency fund:

    • Every dollar that was going to those areas
    • Focus intensity on rebuilding

    Why: You’re temporarily vulnerable. Prioritize regaining protection.

    Example budget shift:

    Before emergency:

    • Emergency fund: $200/month
    • Extra debt payment: $300/month
    • Vacation fund: $150/month

    After emergency (rebuilding):

    • Emergency fund: $650/month
    • Extra debt payment: $0
    • Vacation fund: $0

    Step 4: Create Rebuilding Timeline

    Be realistic but aggressive:

    Amount to rebuild: $2,500
    Monthly allocation: $500
    Timeline: 5 months

    Set milestone dates:

    • Month 1: $500 rebuilt
    • Month 2: $1,000 rebuilt
    • Month 3: $1,500 rebuilt (60% restored)
    • Month 4: $2,000 rebuilt (80% restored)
    • Month 5: $2,500 rebuilt ✓ FULLY RESTORED

    Track progress visibly.

    Step 5: Identify Rebuilding Sources

    Where will the money come from?

    Option 1: Cut discretionary spending temporarily

    • Reduce dining out
    • Pause subscriptions
    • Free entertainment
    • Delay purchases

    Option 2: Increase income temporarily

    • Overtime
    • Side gig
    • Sell items
    • Freelance project

    Option 3: Redirect other savings

    • Pause non-emergency savings temporarily
    • Reduce (don’t eliminate) retirement contributions temporarily

    Option 4: Combination approach (most effective)

    • 30% from spending cuts ($150)
    • 30% from redirected savings ($150)
    • 40% from income increase ($200)
    • Total: $500/month

    Step 6: Analyze What Happened

    Learning opportunity:

    Ask yourself:

    1. Was this truly unforeseeable?
    2. Could I have prevented it?
    3. Should I budget for this differently going forward?

    Examples:

    Car repair emergency:

    • Reflection: “Car is 12 years old, more repairs likely”
    • Adjustment: Create monthly “car repair sinking fund” ($75/month)
    • Result: Future car repairs don’t deplete emergency fund

    Medical emergency:

    • Reflection: “High deductible caused $3,000 out-of-pocket”
    • Adjustment: Consider health plan change during next enrollment
    • Result: Might lower deductible to reduce emergency fund impact

    Job loss:

    • Reflection: “6 months saved, only needed 3 months”
    • Confirmation: 6-month target was correct
    • Action: Rebuild to 6 months again

    Step 7: Celebrate Milestones

    As you rebuild, celebrate progress:

    • 25% restored: Small treat
    • 50% restored: Acknowledge achievement
    • 75% restored: Favorite meal
    • 100% restored: Meaningful celebration

    Why: Positive reinforcement makes financial discipline sustainable.

    Step 8: Prevent Future Same Emergencies

    If your emergency was preventable:

    Example: HVAC died after 20 years

    Prevention strategy:

    • HVAC systems last 15-20 years
    • Create “home system replacement fund”
    • Set aside $100/month
    • In 3 years, have $3,600 for next replacement
    • Reduces emergency fund impact

    Example: Medical emergency due to deferred care

    Prevention strategy:

    • Keep up with preventive care
    • Address small issues before they become emergencies
    • Maintain health insurance
    • Know your coverage

    Not all emergencies are preventable, but some are.

    Step 9: Resist New Risks Until Rebuilt

    While rebuilding, be extra conservative:

    Avoid:

    • Taking on new debt
    • Making large purchases
    • Risky decisions
    • Reducing insurance coverage to save money

    You’re temporarily vulnerable. Act accordingly.

    Step 10: Resume Normal Priorities After Restoration

    Once fully rebuilt:

    ✓ Resume extra debt payments
    ✓ Return retirement contributions to previous level
    ✓ Restart other savings goals
    ✓ Relax spending slightly

    Your financial plan can return to normal.


    Real-Life Rebuilding Example

    Sarah’s Story:

    Situation:

    • Had $7,500 emergency fund (5 months expenses)
    • Car transmission died: $3,200 repair
    • Remaining: $4,300 (less than 3 months)

    Rebuilding Plan:

    1. Paused extra student loan payment ($250/month)
    2. Reduced discretionary spending ($150/month)
    3. Took on 4-hour/week side gig ($400/month)
    4. Total monthly rebuilding: $800

    Timeline:

    • Target to rebuild: $3,200
    • Monthly contribution: $800
    • Time to full restoration: 4 months

    Adjustments made:

    • Created “car replacement fund” ($150/month) for future car expenses
    • Result: Next car issue won’t fully deplete emergency fund

    Outcome:

    • Emergency fund restored in 4 months
    • Created better system for future
    • Avoided debt completely
    • Maintained financial security

    Common Emergency Fund Mistakes to Avoid {#mistakes}

    Learning from others’ mistakes saves you time, money, and stress.

    Mistake #1: Keeping It Too Accessible

    The Problem:
    Emergency fund in regular checking account or easily accessible credit card.

    Why it’s bad:

    • Too tempting to use for non-emergencies
    • Mental accounting fails
    • “Emergency” becomes anything you want
    • Fund never grows

    Real example: Kevin kept emergency fund in checking. Over 12 months, used it for:

    • Black Friday deals ($400)
    • Friend’s bachelor party trip ($600)
    • New TV when old one worked fine ($800)
    • “Emergency” dinner out multiple times ($300)

    Result: $2,100 of $3,000 gone on non-emergencies.

    Solution:
    Separate high-yield savings account at different bank. 1-2 day transfer time provides “pause” to assess if truly emergency.

    Mistake #2: Investing It in the Stock Market

    The Problem:
    “I’ll earn more if I invest my emergency fund in index funds!”

    Why it’s bad:

    • Markets drop exactly when you need money (recessions = job losses)
    • Selling in down market locks in losses
    • Defeats entire purpose of emergency fund (stability)

    Real example: Jennifer had $15,000 emergency fund in S&P 500 index fund.

    • February 2020: $15,000
    • March 2020 (pandemic): Dropped to $9,500
    • Laid off in April 2020
    • Had to sell at loss for living expenses
    • Lost $5,500 when she needed it most

    Solution:
    Emergency funds belong in FDIC-insured savings, not market investments. Stability > returns.

    Mistake #3: Building It Too Slowly While Carrying High-Interest Debt

    The Problem:
    Saving for 12-month emergency fund while paying 22% on credit cards.

    The Math:

    • Saving $500/month at 5% interest
    • Paying 22% on $10,000 credit card debt
    • You’re losing money overall

    Why it’s bad:

    • Paying more in interest than earning in savings
    • Mathematically irrational
    • Could pay off debt faster with blended approach

    Better approach:

    1. Build $1,000-$2,000 starter emergency fund
    2. Attack high-interest debt aggressively
    3. After debt-free, build full emergency fund

    Exception: If job security is very uncertain, prioritize emergency fund even with debt.

    [Internal Link: Learn debt payoff strategies in our upcoming “Debt Snowball vs Debt Avalanche: Best Payoff Strategy” guide]

    Mistake #4: Never Actually Using It for Real Emergencies

    The Problem:
    $10,000 emergency fund sits unused while putting actual emergencies on credit cards.

    Why people do this:

    • “Saving it for something worse”
    • Fear of depleting it
    • Don’t want to rebuild
    • Misunderstand its purpose

    Real example: Marcus had $8,000 emergency fund. Car needed $1,800 repair. Put it on credit card instead “to preserve emergency fund.”

    Result: Paid $2,340 total (with interest) instead of $1,800. Made emergency fund pointless.

    Solution:
    Use emergency fund for actual emergencies. That’s why it exists. Then rebuild it.

    Mistake #5: Treating Target as Finish Line

    The Problem:
    “I hit $10,000, I’m done forever!”

    Why it’s bad:

    • Income increases (need more in emergency fund)
    • Lifestyle expenses increase
    • Family situation changes
    • Job changes
    • Healthcare needs change

    Example: Built 6-month emergency fund in 2019: $12,000

    • 2024: Same $12,000, but expenses now $3,000/month instead of $2,000
    • Actually only has 4 months saved
    • Falsely secure

    Solution:
    Review emergency fund target annually. Adjust for:

    • Income changes
    • Expense changes
    • Life situation changes
    • Inflation

    Mistake #6: Keeping It All in One Account

    The Problem:
    All $30,000 in single savings account.

    Why it’s bad:

    • FDIC insurance only covers $250,000 per depositor per bank
    • Single point of failure (bank issues)
    • Less optimal returns (could ladder some)

    Better approach for large emergency funds ($50,000+):

    • Split across multiple banks (FDIC protection)
    • Consider short-term CD ladder for portion
    • Keep most liquid portion in high-yield savings

    Mistake #7: Not Telling Your Partner

    The Problem:
    One partner builds emergency fund without other’s knowledge.

    Why it’s bad:

    • Secrets damage relationships
    • Partner might have different emergency threshold
    • Causes conflict when discovered
    • Missed opportunity for teamwork

    Solution:
    Financial transparency. Build emergency fund together, discuss what constitutes emergency, agree on target amount.

    Mistake #8: Using It for Planned Expenses

    The Problem:
    “I’ll use my emergency fund for Christmas shopping and rebuild next year.”

    Why it’s bad:

    • Christmas happens every year (not emergency)
    • Creates cycle of depletion and rebuilding
    • Leaves you vulnerable during rebuilding
    • Misunderstands emergency fund purpose

    Solution:
    Create sinking funds for predictable irregular expenses:

    • Holiday fund: $100/month
    • Annual insurance: $150/month
    • Car registration: $30/month

    Mistake #9: Building It Last

    The Problem:
    “I’ll build emergency fund after I:

    • Pay off all debt
    • Max out retirement
    • Save for house
    • [other goals]”

    Why it’s bad:

    • Emergency doesn’t wait for your timeline
    • Without protection, debt happens
    • Creates vulnerability
    • Backwards priority order

    Correct priority order:

    1. $1,000-$2,000 starter emergency fund
    2. Employer 401(k) match (free money)
    3. Pay off high-interest debt
    4. Build full emergency fund (3-12 months)
    5. Other financial goals

    Mistake #10: Letting It Languish in Zero-Interest Checking

    The Problem:
    $15,000 emergency fund earning 0.01% in checking account.

    Opportunity cost:

    • 0.01% = $1.50/year
    • 5.00% = $750/year
    • Difference: $748.50 per year lost

    Over 10 years: $7,485 left on the table

    Solution:
    Move to high-yield savings account (takes 20 minutes, earns $750/year on $15,000).


    Emergency Fund for Different Life Situations {#life-situations}

    Your emergency fund needs change as your life situation changes. Here’s how to adjust:

    Single, Entry-Level Income ($30,000-$45,000/year)

    Recommended emergency fund: 3-6 months expenses

    Typical monthly expenses: $2,000-$2,500
    Target emergency fund: $6,000-$15,000

    Priorities:

    1. $1,000 starter fund (achievable quickly)
    2. Pay off credit card debt
    3. Build to 3 months ($6,000-$7,500)
    4. Increase to 6 months if job security uncertain

    Building strategy:

    • Start with $100-$150/month
    • Use tax refund for boost
    • Side gig income → emergency fund
    • Reach starter fund in 6-10 months

    Challenges:

    • Lower income makes saving harder
    • May have student loan debt
    • Building career (less job security)

    Advantages:

    • Lower expenses (fewer dependents)
    • Flexibility to increase income
    • Can live with roommates to reduce costs

    Married Dual Income, No Kids ($80,000-$120,000 combined)

    Recommended emergency fund: 3-4 months expenses

    Typical monthly expenses: $4,500-$6,000
    Target emergency fund: $13,500-$24,000

    Priorities:

    1. $2,000 starter fund
    2. Pay off high-interest debt
    3. Build to 3 months
    4. Consider 4-6 months if one income is variable

    Building strategy:

    • Each partner contributes $200-300/month
    • Allocate bonuses 50% to emergency fund
    • Can build relatively quickly with two incomes
    • Reach full fund in 12-18 months

    Advantages:

    • Two incomes (if one loses job, other continues)
    • Statistical redundancy
    • Higher combined income

    Risks:

    • Two people = two potential job losses
    • May be accumulating debt (home, cars)
    • Lifestyle inflation

    Special consideration: If planning to have children soon, build larger fund (6 months) to prepare for potential single-income period.


    Single Parent ($45,000-$65,000)

    Recommended emergency fund: 6-9 months expenses

    Typical monthly expenses: $3,000-$4,000
    Target emergency fund: $18,000-$36,000

    Why larger fund needed:

    • Single income (no backup)
    • Dependents relying on you
    • Childcare costs are significant
    • Less flexibility to increase hours or take second job
    • Medical needs for children

    Building strategy:

    • Start with $1,500 starter fund
    • Build slowly but consistently ($150-250/month)
    • Use child tax credit for major boost
    • Don’t feel discouraged by high target
    • Focus on $5,000 first, then $10,000, then full amount

    Challenges:

    • Childcare costs
    • Less income flexibility
    • Higher stress
    • Time constraints

    Support resources:

    • TANF (Temporary Assistance for Needy Families)
    • SNAP (food assistance)
    • Childcare subsidies
    • Tax credits (EITC, Child Tax Credit)
    • Every bit helps toward emergency fund

    Family with Children (2 parents, $100,000-$150,000)

    Recommended emergency fund: 4-6 months expenses

    Typical monthly expenses: $6,000-$8,500
    Target emergency fund: $24,000-$51,000

    Priorities:

    1. $2,000-$3,000 starter fund
    2. If debt-free, build aggressively
    3. Target middle range first (4 months)
    4. Expand to 6 months as income allows

    Building strategy:

    • $500-750/month allocation
    • Tax refund toward fund
    • One bonus per year → emergency fund
    • Reach starter fund in 3-4 months
    • Reach 4 months in 2-3 years
    • Reach 6 months in 3-5 years

    Unique considerations:

    • Kids’ medical needs
    • School expenses (not emergencies, but need separate fund)
    • Older home might need more repair money
    • Cars with higher mileage

    Risk factors:

    • Daycare costs (may decrease if job loss)
    • Higher fixed costs (larger home, multiple cars)
    • More people = more potential emergencies

    Self-Employed/Freelancer ($50,000-$100,000 variable)

    Recommended emergency fund: 9-12 months expenses

    Typical monthly expenses: $3,500-$6,000
    Target emergency fund: $31,500-$72,000

    Why much larger fund needed:

    • Highly variable income
    • No unemployment benefits
    • Client payment delays
    • Industry downturns
    • No employer benefits
    • Must cover own health insurance

    Building strategy:

    • Save 30-40% of good months
    • Don’t increase lifestyle with income increases
    • Build over 3-5 years
    • High-income months → emergency fund
    • Starter fund: $3,000 (one month)

    Additional considerations:

    • Separate “business emergency fund” for business expenses
    • “Tax fund” (30% of income set aside)
    • “Irregular income buffer” (smooths cash flow)
    • Health insurance emergency fund (if not included in regular expenses)

    Advantages:

    • Income upside potential
    • Tax deductions
    • Control over hours (can increase income)

    Challenges:

    • No safety net
    • Cash flow gaps
    • Difficult to predict income

    Timeline:

    • Year 1: Build to $10,000
    • Year 2: Build to $20,000
    • Year 3: Build to $30,000+
    • Year 4-5: Reach full 12 months

    Retiree (Pre-Medicare, 60-65 years old)

    Recommended emergency fund: 12-24 months expenses

    Typical monthly expenses: $4,000-$6,000
    Target emergency fund: $48,000-$144,000

    Why such large fund:

    • No employment income
    • Health insurance very expensive before Medicare
    • Medical emergencies more likely
    • Can’t easily “just get a job”
    • May be supporting adult children
    • Stock market volatility matters more

    Building strategy:

    • Build during working years
    • Don’t reduce when retiring (increase it)
    • Keep replenishing from Social Security/pension
    • Separate from retirement investments

    Additional considerations:

    • Medical emergency fund separate from general emergency
    • Long-term care considerations
    • Home maintenance fund (aging home)
    • Medicare gap coverage costs

    High-Income Earner ($200,000+)

    Recommended emergency fund: 6-12 months expenses OR $100,000, whichever is higher

    Typical monthly expenses: $10,000-$20,000+
    Target emergency fund: $60,000-$240,000

    Why larger absolute amount:

    • Lifestyle expenses are higher
    • Replacement job may be harder to find
    • May have expensive obligations
    • More to lose in emergency

    Building strategy:

    • Should be able to build quickly

    now 4


    claude-sonnet-4-5-20250929

    ARTICLE #3: Zero-Based Budgeting Explained

    Meta Information

    Meta Title: Zero-Based Budgeting: Complete Guide to Manage Every Dollar in 2024

    Meta Description: Master zero-based budgeting with our step-by-step guide. Learn how to allocate every dollar, eliminate waste, and build wealth faster with this powerful budgeting method.

    Primary Keyword: Zero-based budgeting

    Secondary Keywords:

    • Zero-based budget method
    • How to do zero-based budgeting
    • Zero-based budgeting for beginners
    • Monthly zero-based budget
    • Zero-sum budgeting
    • Every dollar budget method

    URL Slug: /zero-based-budgeting-guide-every-dollar

    Article Category: Savings & Budgeting (Cluster 4)


  • Zero-Based Budgeting Explained: Take Control of Every Dollar

    Zero-Based Budgeting Explained: Take Control of Every Dollar

    Table of Contents

    1. Introduction
    2. What is Zero-Based Budgeting?
    3. How Zero-Based Budgeting Works
    4. Zero-Based Budget vs Traditional Budgeting
    5. Benefits of Zero-Based Budgeting
    6. Step-by-Step Guide to Creating Your Zero-Based Budget
    7. Zero-Based Budgeting Categories to Include
    8. Common Challenges and How to Overcome Them
    9. Best Tools and Apps for Zero-Based Budgeting
    10. Real-Life Zero-Based Budget Examples
    11. Frequently Asked Questions
    12. Conclusion

    Introduction {#introduction}

    Do you ever reach the end of the month wondering where all your money went? You’re not alone. According to a 2024 survey by the National Foundation for Credit Counseling, 64% of Americans don’t know where their money goes each month. This financial fog can keep you stuck in a cycle of paycheck-to-paycheck living, preventing you from building the wealth you deserve.

    Enter zero-based budgeting—a powerful money management method that gives every single dollar a job before the month even begins.

    Unlike traditional budgeting methods that leave room for ambiguity, zero-based budgeting ensures that your income minus your expenses equals exactly zero. This doesn’t mean you spend everything—it means you’ve intentionally allocated every dollar to a specific purpose, including savings and investments.

    In this comprehensive guide, you’ll discover everything you need to know about zero-based budgeting, from the fundamental principles to practical implementation strategies. Whether you’re struggling to save money, trying to pay off debt, or simply want more control over your finances, this budgeting method could be the game-changer you’ve been looking for.

    By the end of this article, you’ll have the knowledge and tools to create your first zero-based budget and start your journey toward complete financial control.


    What is Zero-Based Budgeting?

    Zero-based budgeting (ZBB) is a budgeting method where you allocate every dollar of your income to specific expense categories, savings, or debt payments until you reach zero. The fundamental equation is simple:
    Income – Expenses – Savings – Debt Payments = $0

    This doesn’t mean you have zero dollars left in your bank account. Instead, it means that before the month begins, you’ve given every dollar a specific assignment. Nothing is left unaccounted for or available for mindless spending.

    The Core Principle

    Traditional budgeting often follows this pattern:

    • Earn money
    • Pay bills
    • Spend what’s left
    • Maybe save something at the end

    Zero-based budgeting flips this model:

    • Know exactly how much you’ll earn
    • Assign every dollar to a specific purpose (including savings)
    • Execute your plan
    • Adjust as needed throughout the month

    Origins of Zero-Based Budgeting

    While popularized in personal finance circles by financial expert Dave Ramsey and the team at YNAB (You Need A Budget), zero-based budgeting actually originated in the corporate world. Texas Instruments developed this method in the 1970s, and it was later adopted by major corporations and government agencies to eliminate wasteful spending.

    The beauty of this system is that it works just as effectively for household finances as it does for billion-dollar corporations.

    Who Should Use Zero-Based Budgeting?

    This budgeting method is particularly effective for:

    Variable Income Earners

    • Freelancers
    • Commission-based salespeople
    • Small business owners
    • Gig economy workers

    People Struggling with Overspending
    If you constantly find yourself wondering where your money went, ZBB provides clarity and control.

    Aggressive Debt Payers
    When every dollar has a job, you can maximize debt payments while still covering all necessities.

    Wealth Builders
    People serious about building wealth use ZBB to ensure saving and investing happen first, not last.

    Financial Turnaround Seekers
    If you’re trying to get your finances back on track after a setback, ZBB gives you the structure you need.


    How Zero-Based Budgeting Works {#how-it-works}

    Let’s break down the mechanics of zero-based budgeting with a practical approach that anyone can follow.

    The Basic Formula

    Here’s a simplified example:

    Monthly Income: $4,500

    Allocations:

    • Housing: $1,200
    • Utilities: $200
    • Groceries: $500
    • Transportation: $400
    • Insurance: $300
    • Debt Payments: $600
    • Savings: $450
    • Personal Spending: $300
    • Entertainment: $150
    • Miscellaneous: $200
    • Emergency Fund: $200

    Total Allocated: $4,500

    Income – Allocations = $4,500 – $4,500 = $0 ✓

    Notice that the equation reaches zero, but you’ve allocated $650 toward savings and building wealth ($450 + $200 emergency fund).

    The Monthly Cycle

    Zero-based budgeting operates on a monthly cycle:

    Before Month Starts (Days 25-30 of Previous Month):

    1. Project your income for the upcoming month
    2. List all known expenses
    3. Allocate remaining dollars to variable categories
    4. Ensure total allocations equal total income
    5. Review and finalize budget

    During the Month (Days 1-28/30/31):

    1. Track all spending against budgeted amounts
    2. Adjust categories as needed (staying at zero)
    3. Make spending decisions based on remaining category funds
    4. Document any unexpected expenses

    End of Month (Last 2-3 Days):

    1. Review actual vs. budgeted spending
    2. Identify areas of overspending or underspending
    3. Learn from patterns
    4. Prepare for next month’s budget with insights gained

    Key Principles That Make It Work

    1. Intentionality
    Every dollar is assigned a purpose before you spend it. This prevents impulse purchases and mindless spending.

    2. Flexibility Within Structure
    While you plan before the month, you can adjust categories mid-month—as long as the total still equals zero.

    3. Prioritization
    You must decide what’s most important because you can’t allocate more than you earn.

    4. Accountability
    The system forces you to confront exactly how you’re using your money.

    5. Proactive Planning
    You make spending decisions in advance when you’re thinking clearly, not in the moment when emotions might override logic.


    Zero-Based Budget vs Traditional Budgeting {#comparison}

    Understanding how zero-based budgeting differs from other popular methods helps you appreciate its unique advantages.

    Zero-Based Budget vs. Traditional Budget

    Traditional Budgeting Approach:

    • Set spending limits for categories
    • Track expenses throughout month
    • Whatever’s left over gets saved (maybe)
    • Often leaves “unassigned” money
    • Focuses on not overspending

    Zero-Based Budgeting Approach:

    • Assign every dollar before month begins
    • Savings happens first (not last)
    • No unassigned money exists
    • Zero balance by design
    • Focuses on intentional allocation

    Key Difference: Traditional budgeting asks “How much can I spend?” Zero-based budgeting asks “What job should every dollar perform?”

    Zero-Based Budget vs. 50/30/20 Budget

    The 50/30/20 rule suggests:

    • 50% for needs
    • 30% for wants
    • 20% for savings and debt

    Comparison:

    Aspect Zero-Based 50/30/20
    Specificity Exact dollar assignments Percentage ranges
    Flexibility High (adjust categories) Moderate
    Complexity Medium Low
    Effectiveness for debt payoff Excellent Good
    Best for Detail-oriented people Budgeting beginners

    Internal Link: Want to compare budgeting methods? Read our “Complete Guide to Budgeting: Build Wealth on Any Income”

    Zero-Based Budget vs. Envelope System

    The envelope system involves putting cash for each category into physical envelopes.

    Similarities:

    • Both assign specific amounts to categories
    • Both prevent overspending
    • Both require planning ahead

    Differences:

    • Zero-based budgeting can be digital or paper
    • Envelope system requires using cash
    • ZBB handles all transactions; envelopes typically only for variable expenses

    Internal Link: Learn more about cash-based systems in our article “Envelope Budgeting System: Cash-Based Money Management That Works”

    Which Method is Best?

    There’s no universal “best” budgeting method—only the best method for YOU. Zero-based budgeting excels when:

    ✓ You want maximum control over your money
    ✓ You’re paying off debt aggressively
    ✓ You have variable income that changes monthly
    ✓ You’ve struggled with traditional budgeting
    ✓ You’re detail-oriented and enjoy tracking
    ✓ You want to maximize savings and investing


    Benefits of Zero-Based Budgeting {#benefits}

    The zero-based budgeting method offers numerous advantages that can transform your financial life.

    1. Complete Financial Awareness

    Before Zero-Based Budgeting:
    “I think we spend about $600 on groceries… maybe $700? I’m not really sure.”

    After Zero-Based Budgeting:
    “We budgeted $550 for groceries this month and have $127 remaining with one week to go.”

    This level of awareness is powerful. A 2023 study published in the Journal of Consumer Research found that people who knew exactly how much remained in specific budget categories were 67% less likely to overspend.

    2. Eliminates Wasteful Spending

    When you must justify every dollar’s purpose before the month begins, wasteful spending becomes obvious. Common areas where people discover waste include:

    • Unused subscriptions ($20-$200/month average)
    • Duplicate services
    • Convenience purchases
    • Forgotten automatic charges
    • “Just because” shopping

    According to research by West Monroe Partners, the average American wastes $348 per month on unused subscriptions and services. Zero-based budgeting helps you identify and eliminate these money drains.

    3. Accelerates Debt Payoff

    Zero-based budgeting is incredibly effective for debt elimination because:

    Maximizes Debt Payments
    After covering necessities, you can see exactly how much extra money you can direct toward debt.

    Prevents New Debt
    You can’t spend money you’ve already assigned to another category.

    Creates Motivation
    Watching your debt allocation shrink month by month provides psychological wins.

    Real Example:
    Sarah, a teacher from Ohio, used zero-based budgeting to pay off $43,000 in student loans in 33 months instead of the planned 10 years. By allocating every dollar intentionally, she found an extra $1,100 per month for debt payments—money that had previously “disappeared” into untracked spending.

    4. Increases Savings Rate

    Statistical Impact:

    • Traditional budgeters save an average of 3-5% of income
    • Zero-based budgeters save an average of 15-25% of income
    • The difference: intentionality and pre-allocation

    When you pay yourself first by allocating to savings before you assign spending money, saving becomes automatic rather than aspirational.

    5. Reduces Financial Stress and Anxiety

    Financial psychologist Dr. Brad Klontz notes: “Financial stress often stems from uncertainty, not from actual lack of money. When people know exactly where they stand financially, anxiety decreases significantly.”

    Zero-based budgeting provides:

    • Clear spending boundaries
    • Predictable financial outcomes
    • Confidence in financial decisions
    • Reduced money-related arguments in relationships

    6. Enables Better Financial Goal Achievement

    Whether your goal is:

    • Building a 6-month emergency fund
    • Saving for a home down payment
    • Funding a dream vacation
    • Starting a business
    • Retiring early

    Zero-based budgeting lets you assign specific dollar amounts toward these goals each month, turning vague wishes into concrete progress.

    7. Works with Variable Income

    This is where zero-based budgeting truly shines. If your income varies month to month:

    Month 1 Income: $3,500

    • Cover necessities first
    • Allocate rest to priorities
    • Total allocated: $3,500

    Month 2 Income: $5,200

    • Cover same necessities
    • Allocate extra to savings/debt/goals
    • Total allocated: $5,200

    You create a new budget each month based on actual income, ensuring you never spend more than you earn while maximizing high-income months.

    8. Prevents “Lifestyle Creep”

    Lifestyle creep (or lifestyle inflation) happens when your spending rises proportionally with your income, preventing wealth building.

    Zero-based budgeting combats this by forcing you to intentionally decide what to do with extra income rather than automatically spending it.

    Example:
    You get a $500/month raise. With ZBB, you must decide: Will this $500 go to retirement, debt payoff, vacation fund, or lifestyle upgrades? The decision is conscious, not automatic.


    Step-by-Step Guide to Creating Your Zero-Based Budget {#step-by-step}

    Ready to create your first zero-based budget? Follow this detailed, actionable process.

    Step 1: Determine Your Monthly Income

    For Fixed Income Earners:
    Simply use your consistent monthly take-home pay (after taxes and deductions).

    Example: $4,200/month after taxes

    For Variable Income Earners:

    Option A: Conservative Estimate
    Use your lowest monthly income from the past 6 months. Any extra becomes “extra money” to allocate.

    Option B: Average Method
    Calculate average income from previous 3-6 months.

    Option C: Last Month’s Actual
    Budget based on what you actually earned last month.

    Multiple Income Sources:
    Add together:

    • Primary job(s)
    • Side hustles
    • Investment income
    • Any other regular income

    Important: Only include income you’re certain you’ll receive. Don’t budget money you hope to make.

    Step 2: List All Fixed Expenses

    Fixed expenses are the same amount each month and include:

    Housing:

    • Rent or mortgage
    • HOA fees
    • Property taxes (if not in mortgage)

    Utilities:

    • Some utilities are fixed (internet, phone)
    • Others vary but you can use averages

    Insurance:

    • Health insurance
    • Auto insurance
    • Life insurance
    • Renters/homeowners insurance

    Debt Payments:

    • Minimum credit card payments
    • Student loan payments
    • Car payments
    • Personal loan payments

    Subscriptions:

    • Streaming services
    • Software subscriptions
    • Gym memberships
    • Other monthly subscriptions

    Pro Tip: Review bank statements from the past 2-3 months to ensure you don’t miss any automatic payments.

    Step 3: Budget for Variable Expenses

    Variable expenses change from month to month:

    Food:

    • Groceries
    • Dining out
    • Coffee shops
    • Work lunches

    Transportation:

    • Gas
    • Public transportation
    • Parking
    • Vehicle maintenance
    • Rideshares

    Personal Care:

    • Haircuts
    • Toiletries
    • Clothing
    • Dry cleaning

    Healthcare:

    • Copays
    • Medications
    • Medical appointments

    Entertainment:

    • Movies
    • Concerts
    • Hobbies
    • Events

    Household:

    • Cleaning supplies
    • Home maintenance
    • Household items

    For variable categories:

    1. Check spending from last 2-3 months
    2. Calculate average
    3. Budget that amount
    4. Adjust up or down based on this month’s specific needs

    Step 4: Include Periodic Expenses

    Periodic expenses don’t occur monthly but you should budget for them monthly:

    Common periodic expenses:

    • Annual insurance premiums
    • Car registration
    • Holiday gifts
    • Birthday gifts
    • Annual subscriptions
    • Property taxes
    • HOA fees (if not monthly)
    • Vehicle maintenance
    • Medical deductibles
    • Vacation

    How to budget for periodic expenses:

    Example: Car Insurance

    • Annual premium: $1,200
    • Monthly allocation: $1,200 ÷ 12 = $100

    Set aside $100 each month in a separate savings category. When the bill comes due, the money is already there.

    Gift Budget Example:

    • Estimate annual gift spending: $1,500
    • Monthly allocation: $1,500 ÷ 12 = $125

    This prevents the December budget panic when holiday shopping hits.

    Internal Link: For more ways to save on common expenses, check out “How to Save Money Fast: 50+ Proven Ways to Cut Expenses”

    Step 5: Allocate to Savings Goals

    Now comes the exciting part—allocating money toward your financial goals:

    Emergency Fund
    If you don’t have 3-6 months of expenses saved, this should be a top priority.

    Internal Link: Learn exactly how much you need in our “Emergency Fund Guide: How Much to Save and Where to Keep It”

    Retirement

    • 401(k) contributions (often deducted pre-budget)
    • IRA contributions
    • Other retirement savings

    Short-term Goals (0-2 years):

    • Vacation fund
    • Vehicle down payment
    • Wedding
    • Home improvements

    Medium-term Goals (2-5 years):

    • Home down payment
    • Start a business
    • Career transition fund

    Long-term Goals (5+ years):

    • Children’s education
    • Early retirement
    • Rental property

    Recommended minimum allocation: 20% of income to savings/goals, but adjust based on your situation.

    Step 6: Assign Remaining Dollars

    After covering expenses and savings, assign any remaining money to:

    Option 1: Extra Debt Payment
    Accelerate your debt-free journey.

    Option 2: Additional Savings
    Boost emergency fund or other savings goals.

    Option 3: Specific Purpose
    Create a category for something specific you want or need.

    Option 4: Fun Money
    Personal spending without guilt.

    The key is that every dollar gets assigned. Nothing remains “unallocated.”

    Step 7: Review and Balance to Zero

    Your budget equation should look like this:

    text


    Total Income:                    $4,500
    
    Fixed Expenses:                  $2,100
    Variable Expenses:               $1,200
    Periodic Expenses (monthly):       $300
    Savings/Goals:                     $600
    Debt Extra Payment:                $300
                                    -------
    Total Allocated:                 $4,500
    
    Income - Allocated = $4,500 - $4,500 = $0 ✓

    If your number doesn’t equal zero:

    Positive number (money left over):
    Assign it to a category until you reach zero.

    Negative number (allocated more than income):
    Cut expenses or adjust allocations until you reach zero.

    Step 8: Track Throughout the Month

    Your budget is only effective if you track actual spending against it:
    Daily or Weekly:

    • Record all transactions
    • Update category balances
    • Check remaining amounts before purchases

    Best Tracking Methods:

    • Budgeting apps (YNAB, EveryDollar, Mint)
    • Spreadsheets (Google Sheets, Excel)
    • Paper budget planner
    • Hybrid (app + weekly paper review)

    Important Rule: Before making a purchase, check if money remains in that category. If not, you either:

    1. Don’t make the purchase
    2. Move money from another category (keeping total at zero)

    Step 9: Adjust as Needed

    Life doesn’t always follow your budget perfectly. Unexpected expenses happen:

    How to handle budget-busters:

    Option 1: Use buffer category
    Create a “Miscellaneous” or “Buffer” category with $100-200 for small unexpected items.

    Option 2: Move money between categories
    If car repair costs $300 and you budgeted $100:

    • Take $200 from another category (dining out, entertainment, etc.)
    • Keep total at zero

    Option 3: Use emergency fund
    For true emergencies only (job loss, medical emergency, urgent home/car repair).

    The golden rule: You can adjust categories mid-month, but income minus all allocations must still equal zero.

    Step 10: Review and Improve for Next Month

    Last few days of the month:

    Review questions:

    1. Which categories were spot-on?
    2. Where did we overspend?
    3. Where did we underspend?
    4. What unexpected expenses occurred?
    5. What can we do better next month?

    Use insights to improve:

    • Adjust category amounts for next month
    • Add new categories if needed
    • Remove unused categories
    • Refine your budget based on reality

    The first month won’t be perfect—and that’s okay. Most people need 3-4 months to dial in their zero-based budget. Each month gets easier and more accurate.


    Zero-Based Budgeting Categories to Include {#categories}

    A comprehensive zero-based budget includes all areas where money flows out. Here’s a detailed category structure:

    Housing & Utilities

    • Rent/Mortgage
    • Property tax (if not in mortgage)
    • HOA fees
    • Home insurance (if not in mortgage)
    • Electricity
    • Gas/Heating
    • Water/Sewer
    • Trash service
    • Internet
    • Cable/Streaming
    • Home phone (if applicable)
    • Home maintenance/repairs
    • Lawn care/Snow removal

    Transportation

    • Car payment(s)
    • Auto insurance
    • Gas/Fuel
    • Oil changes
    • Car maintenance/repairs
    • Car registration
    • Public transportation
    • Parking fees
    • Tolls
    • Rideshare (Uber/Lyft)

    Food

    • Groceries
    • Restaurants/Dining out
    • Coffee shops
    • Work lunches
    • Food delivery
    • Meal kit services

    Personal & Healthcare

    • Health insurance (if not payroll deducted)
    • Medical copays
    • Prescriptions
    • Dental care
    • Vision care
    • Gym membership
    • Haircuts/Salon
    • Toiletries
    • Cosmetics
    • Clothing
    • Shoes
    • Dry cleaning/Laundry

    Insurance

    • Life insurance
    • Disability insurance
    • Umbrella policy
    • Pet insurance
    • Any other insurance

    Debt Payments

    • Credit card minimums
    • Student loan payments
    • Personal loan payments
    • Medical debt payments
    • Any other debt
    • Extra debt payment (snowball/avalanche)

    Children/Pets (if applicable)

    • Childcare/Daycare
    • School tuition
    • School supplies
    • Children’s activities
    • Child support/Alimony
    • Pet food
    • Vet visits
    • Pet grooming
    • Pet supplies

    Entertainment & Recreation

    • Subscriptions (Netflix, Spotify, etc.)
    • Movies/Concerts
    • Hobbies
    • Sports/Activities
    • Books/Magazines
    • Gaming
    • Events/Experiences

    Giving & Donations

    • Charitable giving
    • Tithing/Religious offerings
    • Gifts (birthday, holiday)
    • Cards

    Savings & Investments

    • Emergency fund
    • Retirement (401k, IRA)
    • General savings
    • House down payment
    • Vacation fund
    • Vehicle replacement fund
    • Wedding fund
    • Education savings
    • Investment account contributions

    Miscellaneous/Buffer

    • Personal spending money (his)
    • Personal spending money (hers)
    • Miscellaneous/Buffer
    • Bank fees
    • Postage
    • Professional dues
    • Computer/Technology

    Periodic Expenses (Monthly Allocation)

    • Annual subscriptions
    • Amazon Prime
    • Costco membership
    • Professional licenses
    • Vehicle registration
    • Property taxes
    • Homeowner’s insurance
    • Vacation/Travel
    • Holiday gifts
    • Home repairs
    • Vehicle maintenance

    Customization is Key: Not every category applies to everyone. Create categories that reflect YOUR actual spending patterns.


    Common Challenges and How to Overcome Them {#challenges}

    Even the best budgeting method comes with challenges. Here’s how to overcome the most common obstacles.

    Challenge #1: The First Month is Overwhelming

    The Problem:
    Creating your first zero-based budget takes time and mental energy. You might feel overwhelmed by all the categories, calculations, and decisions.

    The Solution:

    Start Simple:

    • Week 1: Just track spending without budgeting
    • Week 2: Create basic categories (housing, food, transportation, savings)
    • Week 3: Add more detailed categories
    • Week 4: Refine and adjust

    Use Templates:
    Download zero-based budget templates to start with pre-made categories.

    Give Yourself Grace:
    Your first budget won’t be perfect. Expect to adjust significantly in months 2 and 3.

    Time Investment:

    • First budget: 2-4 hours
    • Second month: 1-2 hours
    • Third month onward: 30-60 minutes

    Challenge #2: Variable Income Makes Planning Difficult

    The Problem:
    If your income varies significantly month to month, creating a budget before the month begins feels impossible.

    The Solution:

    Strategy 1: Budget to Your Minimum
    Use your lowest monthly income from the past 6 months as your budget baseline. Anything above that becomes “extra” to allocate to priorities.

    Strategy 2: Priority-Based Budgeting
    Create a prioritized list:

    1. Housing
    2. Utilities
    3. Food
    4. Transportation
    5. Insurance
    6. Minimum debt payments
    7. Basic necessities
    8. Emergency fund
    9. Extra debt payment
    10. Savings goals
    11. Discretionary spending

    Budget in priority order. If you earn less than expected, you know exactly what to cut (from the bottom up).

    Strategy 3: Two-Budget System

    • Create a “minimum budget” for low-income months
    • Create a “full budget” for normal months
    • Use whichever applies based on actual income

    Challenge #3: Unexpected Expenses Break the Budget

    The Problem:
    The car needs a $600 repair, but you only budgeted $100 for car maintenance this month.

    The Solution:

    Prevention:
    Build a realistic “Miscellaneous” or “Buffer” category ($100-300/month) for smaller unexpected items.

    Create sinking funds for predictable irregular expenses:

    • Car maintenance: $100/month
    • Medical expenses: $75/month
    • Home repairs: $100/month

    When Unexpected Expenses Hit:

    Option 1: Adjust Other Categories
    Move money from flexible categories (entertainment, dining out, personal spending) to cover the emergency.

    Example:

    • Car repair needed: $600
    • Budgeted: $100
    • Need: $500 more
    • Take $200 from dining out
    • Take $150 from entertainment
    • Take $100 from clothing
    • Take $50 from miscellaneous

    Option 2: Use Emergency Fund
    For true emergencies, this is exactly what your emergency fund is for. Use it, then rebuild it.

    Option 3: Split Across Months
    If possible, pay part now and part next month (though be cautious with this approach).

    Challenge #4: Budget Doesn’t Match Reality

    The Problem:
    You keep going over in certain categories no matter how carefully you plan.

    The Solution:

    Track First, Then Budget:
    If your grocery budget never works:

    1. Track actual spending for 2-3 months
    2. Calculate real average
    3. Budget that amount (not wishful thinking)

    Face Reality:
    Your budget should reflect reality, not punishment. If you realistically spend $600 on groceries, budget $600 (then look for ways to reduce if desired).

    Adjust Other Areas:
    If groceries need more, reduce in areas that matter less to you.

    One Category at a Time:
    Don’t try to cut spending in every category simultaneously. Focus on one area per month.

    Challenge #5: Partner Doesn’t Want to Budget

    The Problem:
    You’re excited about zero-based budgeting, but your partner sees it as restrictive or controlling.

    The Solution:

    Reframe the Conversation:

    • Don’t present it as restriction—present it as achieving shared goals faster
    • Focus on what you both WANT (vacation, new car, financial security)
    • Show how budgeting helps you get there

    Include Personal Spending:
    Budget “fun money” for each partner—no questions asked about how it’s spent. This preserves autonomy within the structure.

    Start with Small Wins:
    Begin with one or two categories you both agree need work, not a complete financial overhaul.

    Make It Collaborative:

    • Schedule monthly “budget dates” (with wine/coffee)
    • Ask for input on categories and amounts
    • Share decision-making equally
    • Celebrate progress together

    Lead by Example:
    If your partner isn’t ready, start budgeting your portion of shared expenses. Results often speak louder than words.

    Challenge #6: Keeping Up with Tracking

    The Problem:
    You start strong but lose steam mid-month. Transactions pile up unrecorded.

    The Solution:

    Daily Micro-Habits:

    • Record transactions immediately (in line at store, in car after shopping)
    • Set phone reminder: “Log spending” at 8 PM daily
    • Make it take less than 2 minutes

    Automate What You Can:

    • Link bank accounts to budgeting app
    • Use apps that auto-categorize transactions
    • Review and adjust rather than manual entry

    Weekly Money Dates:
    Set a recurring 15-minute appointment with yourself to review the week’s spending.

    Simplify Categories:
    If you have too many categories, consolidate. Better to track 10 categories consistently than 30 sporadically.

    Accountability Partner:
    Share weekly updates with a friend also budgeting, or join online budgeting communities.

    Challenge #7: Feeling Restricted or Deprived

    The Problem:
    The budget feels like a financial diet—restrictive and joyless.

    The Solution:

    Mindset Shift:
    A budget isn’t a restriction—it’s permission to spend on what you’ve deemed important.

    Build in Fun:

    • Always include entertainment category
    • Budget for small luxuries that matter to you
    • Don’t cut everything you enjoy

    Focus on Values:
    You’re not restricting spending—you’re aligning spending with what you truly value.

    Example:
    Instead of “I can’t afford to eat out,” try “I’m choosing to allocate this money to my vacation fund because travel matters more to me than restaurant meals.”

    Celebrate Wins:
    When you reach a savings milestone or pay off a debt, celebrate (within budget)!

    Freedom Through Boundaries:
    Paradoxically, having spending boundaries creates freedom because you know exactly what you can spend guilt-free.


    Best Tools and Apps for Zero-Based Budgeting {#tools}

    The right tool makes zero-based budgeting significantly easier. Here are the top options:

    Digital Apps

    1. YNAB (You Need A Budget)

    Best for: Serious budgeters committed to the zero-based method

    Features:

    • Built specifically for zero-based budgeting
    • “Give every dollar a job” philosophy
    • Real-time syncing across devices
    • Goal tracking
    • Detailed reports
    • Educational resources

    Pros:

    • Gold standard for zero-based budgeting
    • Excellent mobile app
    • Strong community support
    • Regular updates and improvements

    Cons:

    • Subscription cost: $14.99/month or $99/year
    • Steeper learning curve
    • May be overkill for simple budgets

    Best for: People serious about budgeting who want sophisticated features


    2. EveryDollar

    Best for: Dave Ramsey followers and budgeting beginners

    Features:

    • Clean, simple interface
    • Free version available
    • Zero-based budgeting methodology
    • Bank connection (paid version)
    • Debt payoff tracking

    Pros:

    • Very intuitive and easy to learn
    • Free version is functional
    • Great for beginners
    • Aligns with Baby Steps method

    Cons:

    • Free version requires manual entry
    • Paid version needed for bank syncing ($79.99/year)
    • Fewer features than YNAB

    Best for: Budgeting newcomers or those following Dave Ramsey’s plan


    3. Goodbudget

    Best for: Envelope budgeting fans who want digital version

    Features:

    • Digital envelope system
    • Zero-based approach
    • Syncs across devices
    • Debt tracking
    • Free version available

    Pros:

    • Free version includes 10 envelopes
    • No bank connection required (privacy benefit)
    • Great for couples (syncs across devices)
    • Simple envelope concept

    Cons:

    • Manual transaction entry
    • Limited envelopes on free version
    • Less sophisticated than YNAB

    Best for: People who like the envelope concept but want digital convenience


    4. Mint

    Best for: People wanting free automatic tracking (can be adapted for ZBB)

    Features:

    • Completely free
    • Automatic transaction import
    • Budget creation
    • Bill tracking
    • Credit score monitoring

    Pros:

    • Free forever
    • Easy setup
    • Automatic categorization
    • Comprehensive financial overview

    Cons:

    • Not specifically designed for zero-based budgeting
    • Ads and product recommendations
    • Less control than dedicated ZBB apps

    Best for: Budget-conscious users who want free, automated tracking


    Spreadsheet Templates

    Google Sheets/Excel Options:

    Pros:

    • Completely customizable
    • Free (if using Google Sheets)
    • Full control over categories and format
    • Can create your perfect system

    Cons:

    • Requires setup time
    • Manual entry and calculation
    • No automatic bank sync
    • No mobile app (unless using Google Sheets)

    Where to find templates:

    • Vertex42.com (free Excel templates)
    • Google Sheets template gallery
    • Personal finance blogs
    • Create your own from scratch

    Paper-Based Systems

    Best for: Tactile learners who process better with pen and paper
    Options:

    • Budget Mom’s Budget By Paycheck workbook
    • Clever Fox Budget Planner
    • DIY bullet journal budget
    • Printable templates

    Pros:

    • No screen time required
    • Concrete, tangible tracking
    • Customizable to your style
    • Studies show writing aids retention

    Cons:

    • No automatic calculations
    • Can’t sync across devices
    • Must keep paper secure
    • Risk of loss

    Best for: People who prefer analog systems or want to reduce screen time


    Real-Life Zero-Based Budget Examples {#examples}

    Seeing real budgets helps clarify how zero-based budgeting works in practice. Here are three detailed examples:

    Example 1: Single Person, Entry-Level Income

    Monthly Take-Home Income: $2,800

    HOUSING & UTILITIES

    • Rent: $800
    • Renters insurance: $15
    • Electricity: $60
    • Internet: $50
      Subtotal: $925

    TRANSPORTATION

    • Car payment: $250
    • Auto insurance: $120
    • Gas: $150
    • Car maintenance fund: $50
      Subtotal: $570

    FOOD

    • Groceries: $280
    • Restaurants/Eating out: $100
      Subtotal: $380

    PERSONAL & HEALTH

    • Health insurance: $150 (after employer contribution)
    • Gym membership: $30
    • Haircuts: $25
    • Toiletries/Personal care: $40
    • Clothing: $50
      Subtotal: $295

    DEBT PAYMENTS

    • Student loan minimum: $180
    • Credit card minimum: $50
    • Extra debt payment: $100
      Subtotal: $330

    SAVINGS

    • Emergency fund: $100
    • Retirement (Roth IRA): $100
      Subtotal: $200

    ENTERTAINMENT & MISC

    • Subscriptions (Netflix, Spotify): $25
    • Entertainment/Fun: $50
    • Personal spending money: $40
    • Miscellaneous/Buffer: $35
      Subtotal: $150

    PERIODIC EXPENSES (Monthly Allocation)

    • Annual expenses fund: $50
      Subtotal: $50

    TOTAL ALLOCATED: $2,900

    Wait—that’s $100 over budget!

    Adjustments needed:

    • Reduce eating out to $75 (-$25)
    • Reduce entertainment to $35 (-$15)
    • Reduce clothing to $30 (-$20)
    • Reduce personal spending to $25 (-$15)
    • Reduce extra debt payment to $65 (-$35)

    ADJUSTED TOTAL: $2,800
    Income – Expenses = $2,800 – $2,800 = $0 ✓


    Example 2: Married Couple with Children

    Monthly Combined Take-Home Income: $6,500
    HOUSING & UTILITIES

    • Mortgage: $1,400
    • Property tax: $250
    • Homeowners insurance: $100
    • HOA fees: $75
    • Electricity: $140
    • Gas/Heating: $80
    • Water/Sewer: $60
    • Trash: $25
    • Internet: $70
    • Streaming services: $35
      Subtotal: $2,235

    TRANSPORTATION

    • Car payment 1: $320
    • Car payment 2: $0 (paid off)
    • Auto insurance (2 cars): $180
    • Gas (combined): $300
    • Car maintenance fund: $150
      Subtotal: $950

    FOOD

    • Groceries: $750
    • Restaurants/Date nights: $150
      Subtotal: $900

    CHILDREN

    • Daycare: $800
    • Kids’ activities: $100
    • School supplies/fees: $40
    • Children’s clothing: $80
      Subtotal: $1,020

    PERSONAL & HEALTH

    • Health insurance: $300 (family plan, after employer)
    • Medical copays/prescriptions: $100
    • Gym membership: $45
    • Haircuts (family): $60
    • Toiletries/Personal care: $80
    • Adult clothing: $70
      Subtotal: $655

    DEBT PAYMENTS

    • Credit card minimum: $75
    • Student loan payment: $250
    • Extra debt payment: $200
      Subtotal: $525

    SAVINGS & INVESTMENTS

    • Emergency fund: $200
    • Retirement (401k already deducted from paycheck)
    • Kids’ college fund: $150
    • House repair fund: $100
    • Vacation fund: $150
      Subtotal: $600

    INSURANCE

    • Life insurance (2 policies): $80
      Subtotal: $80

    ENTERTAINMENT & MISC

    • Entertainment/Family fun: $100
    • Hobbies: $50
    • His personal spending: $75
    • Her personal spending: $75
    • Miscellaneous/Buffer: $100
      Subtotal: $400

    GIVING

    • Charitable giving/Tithing: $100
    • Gifts (birthdays, holidays): $35
      Subtotal: $135

    TOTAL ALLOCATED: $6,500
    Income – Expenses = $6,500 – $6,500 = $0 ✓

    Notes on this budget:

    • 401(k) contributions already deducted from paycheck (additional $500/month)
    • Effective savings rate: 23% ($600 + $500 retirement + $200 debt extra = $1,300)
    • Emergency fund target: $20,000 (reached in Month 3, now contributing to other goals)

    Example 3: Freelancer with Variable Income

    This Month’s Projected Income: $4,200
    (Last month was $5,800; month before was $3,400)

    Strategy: Budget based on lowest recent income ($3,400), then allocate extra.

    ESSENTIAL BUDGET (Based on $3,400 minimum)

    HOUSING & UTILITIES

    • Rent: $950
    • Renters insurance: $18
    • Electricity: $70
    • Internet (business expense): $80
      Subtotal: $1,118

    TRANSPORTATION

    • Car payment: $0 (paid off)
    • Auto insurance: $110
    • Gas: $120
    • Car maintenance fund: $80
      Subtotal: $310

    FOOD

    • Groceries: $350
    • Eating out: $80
      Subtotal: $430

    BUSINESS EXPENSES

    • Software subscriptions: $85
    • Professional development: $50
    • Business supplies: $40
    • Quarterly tax savings (1/3 of income): $1,133
      Subtotal: $1,308

    PERSONAL & HEALTH

    • Health insurance: $320 (self-employed)
    • Medical/Dental: $75
    • Gym: $35
    • Personal care: $60
      Subtotal: $490

    DEBT PAYMENTS

    • Credit card minimum: $45
      Subtotal: $45

    SAVINGS (Minimum)

    • Emergency fund: $50
    • Irregular income buffer: $100
      Subtotal: $150

    ENTERTAINMENT & MISC

    • Entertainment: $40
    • Personal spending: $50
    • Miscellaneous: $59
      Subtotal: $149

    MINIMUM BUDGET TOTAL: $3,400


    ADDITIONAL INCOME ALLOCATION ($4,200 – $3,400 = $800)

    Priority 1: Extra quarterly tax savings = $267
    Priority 2: Boost emergency fund = $200
    Priority 3: Extra debt payment = $150
    Priority 4: Retirement (IRA) = $100
    Priority 5: Vacation fund = $50
    Priority 6: Extra fun money = $33

    TOTAL ALLOCATED: $4,200
    Income – Expenses = $4,200 – $4,200 = $0 ✓

    Notes on variable income approach:

    • Essential budget covers all needs even in lowest-income month
    • Extra income gets allocated by priority
    • Irregular income buffer smooths cash flow between payments
    • Quarterly tax savings critical for self-employed (roughly 30% of gross)

    Frequently Asked Questions {#faq}

    Q: What if I can’t get to zero—I’m always in the negative?

    A: If your income minus necessary expenses equals a negative number, you have three options:

    1. Increase income (side hustle, second job, freelancing)
    2. Decrease expenses (find roommate, downsize housing, reduce discretionary spending)
    3. Both (most effective approach)

    This situation means you’re spending more than you earn—unsustainable long-term. Zero-based budgeting reveals this reality so you can address it.


    Q: How do I budget for irregular income like freelance work?

    A: Three strategies:

    1. Budget to your minimum: Use lowest monthly income from past 6 months as your baseline.

    2. Average method: Calculate 3-6 month average and budget to that.

    3. Priority-based: Create prioritized expense list and fund in order based on actual income.

    Also maintain an “irregular income buffer” category—extra savings to smooth cash flow gaps.


    Q: Can I use zero-based budgeting if I’m paid biweekly?

    A: Absolutely! Two approaches:

    Method 1: Monthly budget, track by paycheck

    • Create monthly budget totaling all income
    • Track which expenses come from which paycheck
    • Some months you’ll have 3 paychecks—allocate extra to priorities

    Method 2: Budget by paycheck

    • Create separate budget for each paycheck
    • Assign expenses to specific paycheck
    • Requires more planning but provides clarity

    Q: What’s the difference between zero-based budgeting and zero-sum budgeting?

    A: These terms are essentially synonymous. Both mean:

    • Every dollar is assigned a purpose
    • Income minus all allocations equals zero
    • Nothing is left unassigned

    Different personal finance educators use different terminology, but the concept is identical.


    Q: Do I need to use an app, or can I do this with paper and pen?

    A: You absolutely can use paper! Zero-based budgeting existed long before apps. Paper budgeting works well if you:

    • Prefer tangible tracking
    • Want to avoid screen time
    • Enjoy the act of writing
    • Process information better on paper

    The key is consistency, not the medium.


    Q: How do I handle months where income is higher than normal (bonuses, tax refunds, etc.)?

    A: Create a budget specifically for that extra money, just like you would regular income:

    Example: $2,000 bonus

    • Extra debt payment: $800
    • Emergency fund boost: $600
    • Vacation fund: $300
    • Home improvement: $200
    • Fun/Celebration: $100
      Total: $2,000 (equals zero)

    Don’t let “extra” money disappear into regular spending without a plan.


    Q: Should I include my retirement contributions in my zero-based budget?

    A: Yes! Include all money movement:

    If deducted from paycheck before you receive it:

    • Note it at top of budget
    • Budget with take-home amount
    • Example: “$5,000 gross – $500 401k – $800 taxes = $3,700 to budget”

    If you contribute from take-home pay:

    • Include as regular budget category
    • Allocate specific amount monthly
    • Treat like any other “expense”

    Q: How often should I update my budget?

    A:
    Before each month: Create next month’s budget
    Throughout month: Track spending daily or weekly
    End of month: Review and learn for next month

    Your budget is a living document. Adjust categories mid-month as needed while keeping total at zero.


    Q: What if my partner/spouse doesn’t want to budget?

    A:

    • Start by budgeting your personal portion
    • Show results over 2-3 months
    • Frame as “spending plan” not “budget”
    • Emphasize what you CAN do, not restrictions
    • Include generous “fun money” category for each person
    • Make budget meetings short and positive
    • Focus on shared goals you both want

    Often, seeing results converts skeptics better than conversations.


    Conclusion {#conclusion}

    Zero-based budgeting is more than just a financial technique—it’s a complete mindset shift about how you relate to money. By giving every single dollar a specific job before the month begins, you transform from passive money manager to intentional wealth builder.

    The core principles that make zero-based budgeting so effective:

    ✓ Complete visibility into where every dollar goes
    ✓ Intentional allocation rather than reactionary spending
    ✓ Flexibility to adjust while maintaining control
    ✓ Accountability that prevents money from “disappearing”
    ✓ Goal achievement through specific, regular allocations

    Yes, zero-based budgeting requires more effort than simply hoping things work out. The first month takes time. You’ll need to track diligently. You’ll make mistakes and adjustments.

    But the payoff is extraordinary:

    • Financial stress decreases dramatically
    • Savings increase without feeling restrictive
    • Debt disappears faster
    • Financial goals become achievable rather than aspirational
    • You gain complete confidence about your financial situation

    Remember these key implementation points:

    1. Your first budget won’t be perfect—give yourself 3-4 months to dial it in
    2. Track actual spending against your plan—the budget is only effective if you follow it
    3. Adjust as needed mid-month, but always keep the total at zero
    4. Include fun money—budgeting isn’t punishment, it’s permission
    5. Review and improve each month based on what you learn

    The difference between your current financial reality and the financial future you dream about isn’t complicated—it’s simply giving every dollar a job and following through.

    Your action steps for this week:

    1. Calculate your exact monthly take-home income
    2. List all your fixed expenses
    3. Review last month’s bank statements to identify variable spending
    4. Choose your tracking method (app, spreadsheet, or paper)
    5. Create your first zero-based budget for next month

    The journey to complete financial control begins with a single month, a single budget, and a single commitment: that every dollar you earn will have a purpose.

    You now have the knowledge. You have the tools. You have real-life examples.

    The only thing left is to take action.

    Your financial transformation starts the moment you give your first dollar a job. Make that moment now.

  • Complete Guide to Budgeting: Build Wealth on Any Income

    Complete Guide to Budgeting: Build Wealth on Any Income

    A budget is the foundation of all financial success. It’s the difference between wondering where your money went and telling your money where to go. Yet despite its critical importance, over 60% of Americans don’t use a budget, operating their financial lives without a clear plan—like trying to build a house without blueprints or navigate to a destination without a map.

    The consequences of living without a budget are costly. Americans who don’t budget are three times more likely to carry credit card debt, twice as likely to have insufficient emergency savings, and significantly less likely to achieve major financial goals like homeownership or comfortable retirement. The lack of a budget creates financial stress, missed opportunities, and a perpetual feeling of being behind financially regardless of income level.

    Here’s the powerful truth: budgeting isn’t about restriction—it’s about permission and freedom. A well-designed budget doesn’t tell you what you can’t do; it shows you what you can do. It gives you permission to spend on things that matter while eliminating waste on things that don’t. It transforms vague financial anxiety into concrete action plans. Most importantly, budgeting creates wealth regardless of your income level.

    You don’t need a six-figure salary to build wealth through budgeting. People earning $40,000 with disciplined budgets often accumulate more wealth than people earning $120,000 who let money slip through their fingers. The key isn’t how much you earn—it’s how intentionally you manage what you earn.

    This comprehensive guide provides everything you need to create, implement, and maintain a budget that works for your unique life. You’ll learn why budgets fail and how to avoid those pitfalls, explore multiple budgeting methods to find your perfect fit, discover how to budget on any income level, master the psychology of spending, and build wealth-creating habits that compound over time.

    Whether you’re living paycheck to paycheck and need immediate cash flow relief, earning comfortably but wondering where it all goes, or already financially stable but want to optimize and accelerate wealth building, this guide provides the roadmap to transform your relationship with money through intentional budgeting.

    Why Most Budgets Fail (And How to Succeed)

    Understanding why budgets typically fail is the first step to creating one that actually works.

    The Seven Deadly Budget Sins

    Sin 1: Making It Too Complicated

    The mistake:

    • Tracking every penny across 40+ categories
    • Complex spreadsheets requiring hours monthly
    • Micromanaging insignificant expenses
    • Analysis paralysis preventing action

    Why it fails:
    Complexity creates friction. The more complicated your budget, the less likely you’ll maintain it. Life gets busy, and the 2-hour monthly budget review gets skipped, then the whole system collapses.

    The solution:
    Start simple with 5-10 major categories. You can always add detail later, but simplicity ensures consistency.

    Sin 2: Being Unrealistically Restrictive

    The mistake:

    • Cutting all enjoyment spending to $0
    • Allowing no margin for life’s pleasures
    • Creating punishment-based budget
    • Expecting perfection from day one

    Why it fails:
    Extreme restriction triggers rebellion. Just like crash diets, overly restrictive budgets lead to “budget binges” where you give up and overspend dramatically.

    The solution:
    Include guilt-free spending money. Budget for entertainment, hobbies, dining out—the things that make life enjoyable. Sustainable budgets balance today’s quality of life with tomorrow’s financial goals.

    Sin 3: Forgetting Irregular Expenses

    The mistake:

    • Only budgeting monthly recurring bills
    • Forgetting annual or quarterly expenses
    • Being surprised by predictable costs
    • Using credit cards for “unexpected” regular expenses

    Why it fails:
    Car insurance due twice yearly, holiday gifts, annual subscriptions, and car maintenance are predictable but irregular. When these aren’t budgeted, they feel like emergencies and derail your budget.

    The solution:
    Create sinking funds—monthly savings for irregular expenses. Divide annual costs by 12 and save that amount monthly.

    Example:

    • Car insurance: $1,200/year ÷ 12 = $100/month
    • Holiday gifts: $600/year ÷ 12 = $50/month
    • Car maintenance: $1,200/year ÷ 12 = $100/month

    Sin 4: Not Involving Your Partner

    The mistake:

    • Creating budget alone in dual-income household
    • Imposing budget on partner without input
    • Not communicating about money regularly
    • Having different financial priorities

    Why it fails:
    Budgets require household alignment. One person budgeting while the other spends freely creates resentment and failure.

    The solution:
    Monthly budget meetings with your partner. Both contribute to creating the budget. Both understand and agree to the plan. Both share the goal of financial success.

    Sin 5: Setting It and Forgetting It

    The mistake:

    • Creating budget in January, never reviewing
    • Not tracking actual spending against budget
    • Failing to adjust when life changes
    • No accountability or monitoring

    Why it fails:
    Life is dynamic—income changes, expenses shift, goals evolve. Static budgets become irrelevant quickly.

    The solution:
    Weekly quick-checks (15 minutes) and monthly detailed reviews (30-60 minutes). Adjust categories as needed. Budget is living document, not one-time exercise.

    Sin 6: Not Planning for Fun

    The mistake:

    • All savings, no spending
    • Depriving present self completely for future self
    • Making budget feel like punishment
    • No rewards for budget wins

    Why it fails:
    Humans need positive reinforcement. All delayed gratification and no immediate reward leads to abandonment.

    The solution:
    Budget for fun, entertainment, hobbies, and rewards. Celebrate budget milestones. Balance is key—some now, some later.

    Sin 7: Giving Up After First Slip-Up

    The mistake:

    • Perfect execution expected
    • Single overspending “ruins” entire budget
    • All-or-nothing mentality
    • Starting over constantly instead of adjusting

    Why it fails:
    Perfectionism is the enemy of progress. No one executes perfectly, especially early on.

    The solution:
    Expect imperfection. Overspent dining out this month? Adjust next month. Missed tracking for a week? Resume where you are. Progress beats perfection.

    The Psychology of Successful Budgeting

    Mindset shift required:

    From: “Budget restricts my freedom”
    To: “Budget creates my freedom by aligning spending with values”

    From: “Budget is punishment for past mistakes”
    To: “Budget is plan for future success”

    From: “Budget means I can’t have what I want”
    To: “Budget shows me how to get what I truly want”

    From: “Budgeting is deprivation”
    To: “Budgeting is optimization”

    The truth about budgets and freedom:

    Without budget: Money controls you (react to bills, stress about spending, wonder where it went)

    With budget: You control money (proactive decisions, confidence in spending, direct money toward goals)

    Paradox: The more structured your budget, the more freedom you actually have. When every dollar has a purpose, you can spend guilt-free within those purposes.

    Understanding Your Money: Income and Expenses Audit

    Before creating a budget, you need clear understanding of your current financial reality.

    Calculating Your True Income

    Gross vs Net Income:

    Gross income: Total earnings before deductions
    Net income (take-home): What actually hits your bank account after taxes and deductions

    Budget with net income only. You can’t spend money that never reaches you.

    All income sources:

    Primary employment:

    • Salary/wages (use net after-tax amount)
    • Bonuses and commissions (average if irregular)
    • Overtime (only if consistent and reliable)

    Side income:

    • Freelance work
    • Gig economy earnings (Uber, DoorDash, etc.)
    • Side business revenue (minus expenses)

    Passive income:

    • Rental property (net after expenses)
    • Dividends and interest
    • Royalties or residual income

    Other income:

    • Alimony or child support
    • Social Security or pension
    • Regular gifts or family support

    Irregular income:

    • Tax refunds (average over year)
    • Annual bonuses (average if history exists)
    • Quarterly commissions

    Calculate monthly average:

    For salaried workers: Simple—divide annual salary by 12

    For variable income:

    • Add last 12 months total income
    • Divide by 12 for monthly average
    • Use conservative estimate (better to underestimate than overestimate)

    Example variable income calculation:

    Last 12 months freelance income:
    Jan: $3,200, Feb: $2,800, Mar: $4,100, Apr: $3,600, May: $2,900, Jun: $3,800, Jul: $4,200, Aug: $3,400, Sep: $3,100, Oct: $4,500, Nov: $3,800, Dec: $5,200

    Total: $44,600
    Monthly average: $3,717
    Conservative budget amount: $3,500 (slightly under average for safety)

    Tracking Current Spending: The 30-Day Challenge

    You can’t manage what you don’t measure. Before creating a budget, track every dollar for 30 days.

    How to track:

    Manual method:

    • Notebook or notes app
    • Write down every expense immediately
    • Categorize weekly
    • Total monthly

    App method:

    • Mint, YNAB, EveryDollar, Personal Capital
    • Connect bank accounts for automatic tracking
    • Review and categorize regularly
    • Analyze patterns monthly

    Hybrid method:

    • Apps for regular bills and card purchases
    • Manual logging for cash spending
    • Weekly reconciliation

    What to track:

    Fixed expenses (same every month):

    • Rent/mortgage
    • Car payment
    • Insurance premiums
    • Subscriptions and memberships
    • Loan payments

    Variable expenses (change monthly):

    • Utilities
    • Groceries
    • Gas/transportation
    • Dining out
    • Entertainment
    • Shopping/personal care

    Irregular expenses (not every month):

    • Car maintenance
    • Medical expenses
    • Gifts
    • Travel
    • Home repairs

    During 30-day tracking period:

    Don’t change spending behavior yet—track normal patterns
    Categorize everything—even small purchases
    Include cash spending—often the invisible money
    Note emotional spending—what triggered purchases

    Analyzing Spending Patterns

    After 30 days, analyze your data:

    Calculate totals by category:

    Housing: $______
    Transportation: $______
    Food (groceries + dining): $______
    Utilities: $______
    Insurance: $______
    Debt payments: $______
    Entertainment: $______
    Personal care: $______
    Shopping: $______
    Subscriptions: $______
    Miscellaneous: $______

    Total monthly spending: $______

    Critical questions to ask:

    Where is money going that surprises you?
    Most people discover “invisible” spending—$300/month on coffee, $200 on subscriptions they don’t use, $400 on impulse Amazon purchases.

    What percentage goes to needs vs wants?
    Needs: Housing, food, utilities, transportation, insurance, debt minimums
    Wants: Entertainment, dining out, hobbies, luxuries

    Which expenses align with your values and which don’t?
    You might spend $200/month on streaming services you rarely watch but only $50/month on hobbies you love. Budgeting realigns spending with actual values.

    Which expenses could be reduced or eliminated without impacting quality of life?
    Often you’ll find spending that provides little satisfaction but significant cost—prime candidates for cutting.

    Example analysis revelation:

    Sarah tracked spending for 30 days and discovered:

    • $340/month dining out (mostly fast food from exhaustion)
    • $180/month on subscriptions (gym she never uses, streaming services overlapping)
    • $120/month on convenience store purchases
    • Total waste: $640/month = $7,680/year

    These weren’t conscious choices—just money slipping away. Awareness created opportunity to redirect $640/month toward goals that actually mattered to her.

    Creating Spending Categories That Work

    Major categories (most budgets need 8-15 total):

    Housing:

    • Rent/mortgage
    • Property taxes
    • HOA fees
    • Home maintenance
    • Renter’s/homeowner’s insurance

    Transportation:

    • Car payment
    • Auto insurance
    • Gas
    • Maintenance and repairs
    • Public transit
    • Parking

    Food:

    • Groceries
    • Dining out
    • Coffee shops
    • Work lunches

    Utilities:

    • Electric
    • Gas/heat
    • Water/sewer
    • Internet
    • Phone
    • Trash

    Insurance:

    • Health insurance
    • Life insurance
    • Disability insurance
    • Other insurance

    Debt Payments:

    • Credit cards
    • Student loans
    • Personal loans
    • Other debt

    Savings:

    • Emergency fund
    • Retirement contributions
    • Other savings goals

    Personal:

    • Clothing
    • Personal care (haircuts, etc.)
    • Medical copays and medications
    • Gym/fitness

    Entertainment:

    • Subscriptions (streaming, etc.)
    • Hobbies
    • Movies, concerts, events
    • Books, games

    Giving:

    • Charitable donations
    • Gifts for others
    • Religious contributions

    Miscellaneous:

    • Everything else
    • Buffer category
    • Unexpected expenses

    Customize for your life:

    Parents add: Childcare, kids’ activities, school expenses
    Pet owners add: Pet food, vet, grooming
    Students add: Tuition, books, supplies
    Business owners add: Business expenses (separate from personal)

    Category granularity decision:

    Too broad: “Spending” = $3,000 (not useful)
    Too granular: 40+ categories including “fast food,” “sit-down restaurants,” “coffee,” “work lunches” separately (too complex)
    Just right: “Food” with subcategories “Groceries” and “Dining Out” (manageable and informative)

    The 50/30/20 Budget Method: Simple and Effective

    Perfect for beginners and those who want straightforward approach without complexity.

    How 50/30/20 Works

    Divide after-tax income into three buckets:

    50% to Needs (Essential Expenses)

    Required for basic living. If you stopped paying, you’d face serious consequences.

    Includes:

    • Housing (rent/mortgage, utilities, insurance)
    • Transportation (car payment, insurance, gas, maintenance)
    • Groceries
    • Minimum debt payments
    • Essential insurance (health, auto, life)
    • Basic clothing
    • Essential personal care

    Does NOT include:

    • Premium cable/streaming packages
    • Dining out
    • New clothes beyond essentials
    • Luxury transportation

    30% to Wants (Discretionary Spending)

    Things that enhance life but aren’t required for basic functioning.

    Includes:

    • Dining out and entertainment
    • Hobbies and recreation
    • Subscriptions (streaming, gym, etc.)
    • Vacations and travel
    • Shopping beyond essentials
    • Upgraded phone or tech
    • Premium versions of necessities

    Key distinction: Groceries = need. Dining out = want. Basic phone = need. Latest iPhone = want.

    20% to Savings and Extra Debt Payments

    Building financial security and eliminating debt beyond minimums.

    Includes:

    • Emergency fund contributions
    • Retirement savings (beyond employer match)
    • Other savings goals
    • Extra principal payments on debt
    • Investments

    Example 50/30/20 budget:

    Monthly net income: $5,000

    Needs (50% = $2,500):

    • Rent: $1,200
    • Utilities: $150
    • Car payment: $300
    • Car insurance: $100
    • Gas: $150
    • Groceries: $400
    • Health insurance: $200
      Total: $2,500

    Wants (30% = $1,500):

    • Dining out: $400
    • Entertainment: $200
    • Gym membership: $50
    • Streaming services: $45
    • Shopping/personal: $300
    • Hobbies: $200
    • Fun/miscellaneous: $305
      Total: $1,500

    Savings/Debt (20% = $1,000):

    • Emergency fund: $400
    • Retirement (401k): $300
    • Extra credit card payment: $200
    • Savings for vacation: $100
      Total: $1,000

    Advantages of 50/30/20

    Simplicity:
    Only three categories to manage
    Easy to calculate and implement
    No complex spreadsheets required
    Can start immediately

    Flexibility within structure:
    Provides guardrails without micromanaging
    Discretion within each bucket
    Adaptable to different life situations
    Scales to any income level

    Automatic balance:
    Forces mindful spending on wants
    Ensures sufficient savings
    Prevents need-creep (needs expanding to fill income)
    Maintains quality of life while building wealth

    Easy to communicate:
    Partners quickly understand
    No arguments about details
    Clear agreed-upon framework
    Objective spending limits

    Adjusting 50/30/20 for Your Situation

    50/30/20 is guideline, not law. Adjust based on reality:

    High cost-of-living areas:

    Housing alone might be 35-40% of income in expensive cities
    Adjust to 60/20/20 or 55/25/20
    Maintain 20% savings minimum if possible

    Example: San Francisco on $6,000/month:

    • 60% needs ($3,600): Rent $2,400, other $1,200
    • 20% wants ($1,200): Scaled back but present
    • 20% savings ($1,200): Maintained

    Aggressive debt payoff mode:

    Temporarily shift to 50/20/30
    30% to debt elimination instead of savings
    Reduce wants to accelerate debt freedom

    Example: Focused debt elimination:

    • 50% needs ($2,500)
    • 20% wants ($1,000): Reduced temporarily
    • 30% savings/debt ($1,500): Extra $500 to debt

    High earners:

    Often needs are well under 50%
    Shift to 40/30/30 or even 35/25/40
    More to savings accelerates wealth building

    Example: $10,000/month income:

    • 35% needs ($3,500): Housing and essentials
    • 25% wants ($2,500): Comfortable lifestyle
    • 40% savings ($4,000): Aggressive wealth building

    Very low income:

    May need 60-70% for needs
    Reduce wants temporarily
    Maintain minimum savings (even 10%)

    Example: $2,500/month income:

    • 65% needs ($1,625): Tight but covers essentials
    • 25% wants ($625): Modest but present
    • 10% savings ($250): Foundation for future

    The key: Adjust percentages to fit reality while maintaining the principle of balanced allocation between present needs, present enjoyment, and future security.

    Implementing 50/30/20

    Step 1: Calculate your three bucket amounts

    Monthly net income: $______
    50% (Needs): $______ × 0.50 = $______
    30% (Wants): $______ × 0.30 = $______
    20% (Savings/Debt): $______ × 0.20 = $______

    Step 2: Categorize your current expenses

    Review your 30-day tracking
    Assign each expense to Need, Want, or Savings/Debt
    Calculate totals in each category
    Compare to your target percentages

    Step 3: Identify gaps and adjustments

    If needs exceed 50%:

    • Can you reduce housing (roommate, smaller place)?
    • Can you reduce transportation (cheaper car, public transit)?
    • Can you reduce utilities (conservation, cheaper plans)?
    • If truly unavoidable, adjust percentages proportionally

    If wants exceed 30%:

    • Which wants provide least satisfaction? (Cut these)
    • Which wants could be reduced without elimination?
    • Which wants are actually mis-categorized needs?
    • Be honest about true necessities vs luxuries

    If savings below 20%:

    • This is the most important bucket to protect
    • Cut wants before cutting savings
    • Increase income if expenses truly can’t be reduced
    • Even 10% is better than 0% while working toward 20%

    Step 4: Set up tracking system

    Simple approach:
    Three separate bank accounts or tracking categories
    Manually allocate each paycheck into three buckets
    Spend only from designated bucket

    Advanced approach:
    Budgeting app with 50/30/20 categories
    Automatic categorization of transactions
    Real-time tracking of bucket spending
    Alerts when approaching limits

    Step 5: Review and adjust monthly

    First week of month: Review previous month spending
    Categorize any uncategorized expenses
    Calculate actual percentages achieved
    Adjust current month if needed
    Celebrate successes, learn from overspending

    Zero-Based Budgeting: Every Dollar Has a Job
    Most detailed budgeting method—every dollar of income assigned to specific category before the month begins.

    How Zero-Based Budgeting Works

    The core principle:

    Income – Expenses – Savings = Zero

    Not “spend everything to zero” but rather “assign everything to a category” (including savings categories).

    The process:

    Before the month begins:

    1. List expected income for upcoming month
    2. List all expenses and savings goals
    3. Assign every dollar to specific category
    4. Ensure total assignments equal total income
    5. Result: Zero dollars “unassigned”

    Example zero-based budget:

    Income for March:

    • Salary (after-tax): $4,500
    • Freelance income: $800
    • Total income: $5,300

    Assignments:

    Housing ($1,450):

    • Rent: $1,200
    • Renter’s insurance: $25
    • Utilities: $150
    • Internet: $75

    Transportation ($525):

    • Car payment: $275
    • Car insurance: $95
    • Gas: $120
    • Parking: $35

    Food ($650):

    • Groceries: $450
    • Dining out: $200

    Personal ($280):

    • Phone: $80
    • Gym: $45
    • Haircut: $40
    • Clothing: $65
    • Personal care: $50

    Debt ($600):

    • Student loan minimum: $250
    • Credit card minimum: $150
    • Extra credit card payment: $200

    Savings ($800):

    • Emergency fund: $400
    • Vacation fund: $150
    • Car replacement fund: $100
    • Retirement (Roth IRA): $150

    Entertainment ($350):

    • Streaming services: $35
    • Hobbies: $100
    • Social activities: $150
    • Books/media: $65

    Giving ($150):

    • Charitable donation: $100
    • Friend’s birthday gift: $50

    Irregular expenses ($245):

    • Car maintenance fund: $100
    • Medical copay fund: $75
    • Annual subscription (divided by 12): $70

    Miscellaneous/Buffer ($250):

    • Unplanned expenses: $250

    Total assigned: $5,300
    Income: $5,300
    Remaining: $0 ✓

    Advantages of Zero-Based Budgeting

    Maximum intentionality:

    Every dollar has specific purpose
    No money “leftover” to slip away
    Conscious decisions about all spending
    Forces prioritization

    Proactive planning:

    Budget created before month begins
    Prepared for upcoming expenses
    No reactive scrambling when bills due
    Aligns spending with priorities in advance

    Flexibility within structure:

    Can adjust categories mid-month
    Money can be moved between categories as needed
    Not rigid if properly implemented
    Responds to life’s changes

    Goal acceleration:

    Clear visibility into savings and goals
    Easy to see impact of spending trade-offs
    “If I reduce dining out $100, I can increase vacation fund $100”
    Motivates conscious choices

    Debt elimination power:

    Every extra dollar assigned to purpose
    Debt payoff is budgeted line item, not afterthought
    Clear tracking of debt reduction progress
    Snowball/avalanche methods easily implemented

    Zero-Based Budget Challenges

    Time intensive initially:

    First budget takes 2-3 hours to create
    Requires detail orientation
    Learning curve with tools
    May feel overwhelming at first

    Requires monthly planning:

    Can’t set-and-forget
    Must budget each month before it begins
    Income or expense changes require adjustments
    Ongoing time commitment (1 hour monthly after initial setup)

    Can be too rigid:

    Some people feel micromanaged
    Category perfectionism creates stress
    May miss forest for trees
    Potential for analysis paralysis

    Variable income complexity:

    Harder to assign every dollar when income fluctuates
    May need to budget in waves as income arrives
    Requires conservative income estimates
    More complexity than steady-salary situations

    Making Zero-Based Budgeting Work

    Start simple:

    Begin with 10-12 major categories
    Add detail as you become comfortable
    Don’t try to track every tiny category initially
    Master the basics before advancing

    Use the right tool:

    YNAB (You Need A Budget):

    • Designed specifically for zero-based budgeting
    • “Give every dollar a job” philosophy
    • Real-time tracking and adjustments
    • Mobile app for on-the-go budgeting
    • Cost: $14.99/month or $99/year

    EveryDollar:

    • Dave Ramsey’s zero-based budget app
    • Free basic version available
    • Premium version with bank connection: $79.99/year
    • Simple, user-friendly interface
    • Ramsey Baby Steps integration

    Spreadsheet (free):

    • Google Sheets or Excel templates
    • Complete customization
    • No ongoing cost
    • Requires more manual work
    • Many free templates available online

    Build buffer into budget:

    Always include “miscellaneous” or “buffer” category:

    • 3-5% of income for truly unexpected items
    • Prevents budget failure from small surprises
    • Reduces stress about perfect categorization

    Example:
    $5,000 income
    Buffer category: $200 (4%)
    Provides cushion for imperfect predictions

    Review and adjust weekly:

    Weekly 15-minute check-in:

    • Review spending so far this month
    • Adjust remaining budget if needed
    • Move money between categories as necessary
    • Stay on track before end of month

    Monthly 60-minute planning session:

    • Create next month’s budget
    • Review previous month’s results
    • Analyze patterns and trends
    • Adjust categories based on learning

    Accept imperfection:

    First 3 months are learning period
    You will mis-estimate categories
    You will need to adjust mid-month
    This is normal and expected

    The goal is progress, not perfection.

    Who Zero-Based Budgeting Suits Best

    Ideal for:

    Detail-oriented people who enjoy tracking and analysis
    Aggressive debt payers who want maximum debt elimination
    Variable income earners who need tight control
    Those who love their budgeting tool (YNAB enthusiasts, spreadsheet lovers)
    People recovering from financial crisis who need intensive structure
    Savers building toward specific goals who want clear goal tracking

    Not ideal for:

    People who hate detail and find it overwhelming
    Those wanting simple approach (50/30/20 better)
    Extremely busy individuals without time for weekly check-ins
    Casual budgeters wanting basic guidelines only
    Those triggered by “restriction” (may need different framing)

    Success story:

    Michael and Jennifer had $78,000 in debt and felt out of control.

    Implemented zero-based budgeting:

    • Spent 3 hours creating first budget together
    • Weekly 15-minute check-ins
    • Monthly planning dates
    • Used YNAB app
    • Every dollar assigned including “fun money”

    Results after 18 months:

    • Paid off $42,000 debt
    • Built $8,000 emergency fund
    • Stopped arguing about money
    • Felt in control for first time in marriage
    • “The weekly check-ins transformed our communication and our finances”

    The Envelope Budgeting System: Cash-Based Control

    Tactile, cash-based method providing physical and psychological control over spending.

    How Envelope Budgeting Works

    The classic system:

    Step 1: Determine budget categories (usually 8-15)

    Common envelope categories:

    • Groceries
    • Dining out
    • Gas
    • Entertainment
    • Personal spending
    • Clothing
    • Gifts
    • Miscellaneous

    Step 2: Calculate monthly amount for each category

    Based on your budget and tracking:

    • Groceries: $400
    • Dining out: $200
    • Gas: $120
    • Entertainment: $150
    • Personal (each spouse): $100
    • Clothing: $75
    • Gifts: $60
    • Miscellaneous: $95

    Step 3: Get cash for the month

    Total envelope spending: $1,200
    Visit bank and withdraw $1,200 cash
    Get mix of bills (twenties, tens, fives, ones)

    Step 4: Stuff envelopes

    Physical envelopes or envelope wallet
    Label each envelope with category
    Put designated cash in each envelope
    Store securely at home

    Step 5: Spend only from envelopes

    Going to grocery store? Take groceries envelope
    At restaurant? Use dining out envelope
    Getting gas? Take gas envelope
    Buying gift? Use gifts envelope

    Step 6: When envelope is empty, stop spending in that category

    Out of dining out money? Cook at home rest of month
    Groceries running low? Shop carefully, use pantry items
    Entertainment spent? Find free activities

    Step 7: Anything left over rolls to next month or goes to goals

    Groceries left $40? Add to next month or move to savings
    Consistent overfunding? Reduce category next month
    Consistent underfunding? Increase category next month

    Modern Digital Envelope Systems

    Digital envelope apps provide envelope concept without cash:

    Goodbudget:

    • Digital envelope budgeting app
    • Sync across devices with partner
    • Free version (10 envelopes)
    • Plus version ($8/month or $70/year for unlimited)
    • Visual envelope representation

    Mvelopes:

    • Comprehensive digital envelope system
    • Connects to bank accounts
    • Automatic transaction categorization
    • Premier version $6/month
    • More expensive but full-featured

    YNAB (You Need A Budget):

    • While zero-based, functions similarly to envelopes
    • “Categories” are essentially digital envelopes
    • Most popular digital envelope-style app
    • $14.99/month or $99/year

    Qube Money:

    • Digital debit card with envelope system
    • Create “qubes” (envelopes) for each category
    • Activate specific qube for each purchase
    • Real-time envelope tracking
    • Free basic version, premium $8/month

    Hybrid approach:

    Use cash envelopes for categories where you overspend:

    • Dining out (common overspending category)
    • Entertainment
    • Personal shopping

    Use digital/automatic for fixed bills:

    • Rent/mortgage
    • Utilities
    • Insurance
    • Subscriptions

    Best of both worlds—control where needed, convenience where possible.

    Why Envelope Budgeting Works (The Psychology)

    Psychological principle: Tangibility increases consciousness

    Cash is physically real:
    Watching cash leave wallet creates awareness
    Seeing envelope empty provides concrete limit
    Cannot overspend (unlike credit card)
    Physical act of handing over money makes spending “real”

    Study findings:

    People spend 12-18% less when using cash vs cards
    Cash creates psychological “pain of paying”
    Digital payments abstract spending, reducing awareness
    Envelopes make abstract budget concept tangible

    Visual progress tracking:

    See envelope fill up at month start (satisfying)
    Watch it decrease with spending (awareness)
    See what’s left at a glance (no calculation needed)
    Full envelopes at month-end feel like winning

    Natural spending limits:

    Credit cards have artificial limits ($10,000+)
    Envelopes have real limits (what’s physically there)
    Cannot overspend without conscious decision to rob another envelope
    Creates accountability partner (the empty envelope)

    Gamification element:

    Challenge: Make it to month end with money left
    Reward: Leftover money goes to goal or rolls over
    Competition: Couples can compare who stayed in budget
    Achievement: Mastering a category feels like leveling up

    Envelope System Challenges and Solutions

    Challenge 1: Requires using cash

    Modern problem:
    Many people rarely use cash
    Online shopping impossible with cash
    Some vendors don’t accept cash
    Carrying large amounts feels unsafe

    Solutions:

    • Hybrid approach (cash for temptation categories, digital for others)
    • Digital envelope apps
    • Envelope budgeting concept with debit card categories
    • Cash for in-person, card for online with manual envelope deduction

    Challenge 2: Inconvenient

    Reality:
    Must remember to bring correct envelope
    May need to go home if brought wrong envelope
    Cannot spontaneously spend if envelope is home
    Requires planning ahead

    Solutions:

    • Small envelope wallet carried always
    • Keep car envelope in car, grocery envelope in purse
    • Partner carries different envelopes (division of responsibility)
    • Relaxed enforcement (emergency borrowing from another envelope allowed occasionally)

    Challenge 3: Safety and security

    Concern:
    Carrying significant cash feels risky
    Loss or theft means lost budget
    Not all neighborhoods/situations safe for cash

    Solutions:

    • Don’t carry all envelopes at once (only take what you need)
    • Keep main envelope storage secure at home
    • Use digital for unsafe situations
    • Smaller amounts in each envelope

    Challenge 4: Doesn’t work for all categories

    Fixed bills paid automatically:
    Mortgage/rent, insurance, subscriptions
    These aren’t envelope-appropriate
    Must be handled separately

    Solutions:

    • Envelopes only for variable, discretionary spending
    • Pay fixed bills automatically
    • Hybrid system (envelopes + auto-payments)
    • Envelopes for areas needing most control

    Challenge 5: Hard to buy gifts or split purchases

    Scenarios:
    Buying $100 gift but gifts envelope only has $60
    Splitting restaurant bill with friend
    Buying both groceries and household items at same store

    Solutions:

    • “Borrow” from another envelope and note it
    • Plan gift purchases across months
    • Split transaction into correct envelopes at home
    • Miscellaneous envelope as overflow category

    Who Envelope Budgeting Suits Best

    Ideal for:

    Chronic overspeenders in specific categories (dining out, shopping, entertainment)
    Visual, tactile learners who need to see and touch
    Cash-preferring individuals comfortable with bills and coins
    Couples wanting clear, visible accountability
    Those who struggled with abstract digital budgets
    People seeking tight control in problematic spending areas
    Debt payers who need spending guardrails

    Success story:

    Amanda struggled with $400-600/month dining out despite $200 budget.

    Switched to envelope system:

    • $200 cash in dining out envelope at month start
    • When envelope empty, no more restaurants
    • First month: Envelope empty on day 18
    • Had to cook for 12 days
    • Difficult but empowering

    After 6 months:

    • Consistently stayed in $200 budget
    • Actually had money left over several months
    • Saved $2,400+ vs previous habits
    • Redirected to debt payoff
    • “Physical cash made it real. I finally had control.”

    For detailed explanation of [envelope budgeting implementation]( Envelope Budgeting System), including specific category recommendations and troubleshooting, our comprehensive guide provides step-by-step instructions.