Category: Banking & Financial Tools

  • Online Banks vs Traditional Banks: Which Is Right for You?

    Online Banks vs Traditional Banks: Which Is Right for You?

    The way Americans bank has fundamentally changed. In 2024, over 78% of banking customers primarily use digital channels, and online-only banks now hold more than $450 billion in deposits—a 300% increase from just five years ago.

    But does this mean traditional banks with physical branches are obsolete? Not quite.

    The truth is more nuanced. Online banks offer dramatically higher interest rates and lower fees, but traditional banks provide in-person service and broader product offerings. Some people thrive with purely digital banking, while others need the security of walking into a physical branch.

    Choosing between online and traditional banking isn’t about which is objectively “better”—it’s about which aligns with your financial needs, habits, and lifestyle.

    In this comprehensive guide, you’ll discover the real differences between online and traditional banks, the advantages and disadvantages of each, who should choose which option, and whether a hybrid approach might be your best solution. We’ll examine interest rates, fees, customer service, security, and every other factor that matters.

    By the end, you’ll know exactly which banking model suits your situation—or whether using both together gives you the best of both worlds.

    Let’s dive into the great banking debate.


    Understanding the Two Banking Models

    Before comparing them, let’s clearly define what we mean by each type.

    What Are Traditional Banks?

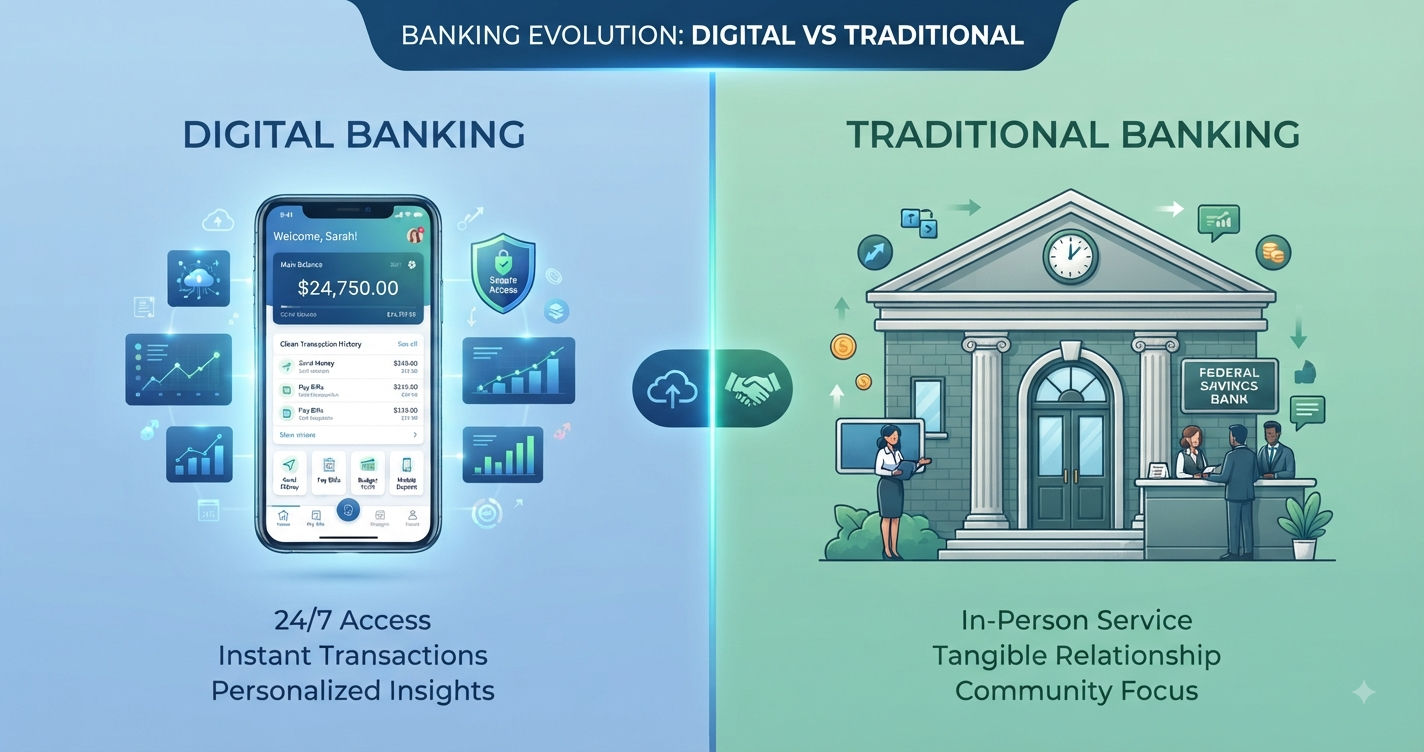
    Traditional banks—also called brick-and-mortar or conventional banks—are financial institutions with physical branch locations where customers can conduct in-person transactions.

    Key Characteristics:

    • Physical branches in multiple locations
    • In-person tellers and customer service
    • ATM networks (often proprietary)
    • Full range of financial products (checking, savings, loans, mortgages, investment services)
    • Established brand recognition (often decades or centuries old)
    • FDIC insured up to $250,000 per depositor

    Examples: Chase, Bank of America, Wells Fargo, PNC, U.S. Bank, regional banks, and credit unions with branches.

    Primary Value Proposition: Convenience of in-person service, comprehensive financial services under one roof, and the comfort of face-to-face banking relationships.

    What Are Online Banks?

    Online banks—sometimes called digital banks, internet banks, or neobanks—operate primarily or exclusively through digital channels without physical branch locations.

    Key Characteristics:

    • No physical branches (or very limited locations)
    • All transactions conducted via app, website, or phone
    • Higher interest rates on deposits
    • Lower or zero fees
    • ATM fee reimbursements common
    • Limited product offerings (primarily deposit accounts)
    • FDIC insured through partner banks

    Examples: Ally Bank, Marcus by Goldman Sachs, Discover Bank, Capital One 360, SoFi, Chime, Current.

    Primary Value Proposition: Superior interest rates, minimal fees, cutting-edge technology, and 24/7 access from anywhere.

    The Hybrid Model

    Some banks operate a hybrid model, combining physical branches with robust digital platforms:

    Examples: Capital One (has cafes/branches but emphasizes digital), Discover (limited branches), USAA (military-focused with few branches).

    These institutions attempt to capture advantages of both models, though they may not excel at either compared to pure-play competitors.


    The Complete Comparison: Online vs Traditional Banks

    Let’s examine every critical factor side-by-side.

    Interest Rates: The Biggest Difference

    Online Banks WIN decisively

    This is where online banks shine brightest—and the difference is substantial.

    Current Average Rates (2025):

    Account Type Online Banks Traditional Banks Difference
    Savings Account 4.00% – 5.00% APY 0.01% – 0.10% APY 40-500x higher
    Money Market 4.25% – 5.25% APY 0.05% – 0.25% APY 20-100x higher
    Checking Account 0.10% – 0.50% APY 0.00% – 0.01% APY Often 50x+ higher
    CD (1-year) 4.50% – 5.50% APY 0.50% – 2.00% APY 2-10x higher

    Real-World Impact:

    On a $10,000 savings balance:

    • Online bank at 4.50% APY: Earn $450/year
    • Traditional bank at 0.05% APY: Earn $5/year
    • Difference: $445 annually—just for parking your money differently

    Over 10 years, this compounds to thousands of dollars in free money simply from choosing the right bank type.

    Why the Huge Gap?

    Online banks can offer dramatically higher rates because:

    1. No Branch Costs: No rent, utilities, or maintenance for hundreds of locations
    2. Fewer Employees: Automation reduces staffing needs by 60-80%
    3. Lower Marketing Costs: Digital advertising is cheaper than traditional campaigns
    4. Competitive Strategy: Use high rates to attract customers from traditional banks

    Traditional banks can afford to pay minimal interest because most customers prioritize convenience over returns, giving them little competitive pressure to increase rates.

    Learn more: Check our high-yield savings accounts guide for current top rates.


    Fees: Online Banks Usually Win

    Online Banks WIN, but not universally

    Online banks typically charge significantly fewer and lower fees across the board.

    Common Fee Comparison:

    Fee Type Online Banks Traditional Banks
    Monthly Maintenance $0 (98% of online banks) $10-$25/month (waivable with conditions)
    Overdraft Fees $0-$15 (many eliminated entirely) $30-$35 per occurrence
    ATM Fees $0 (often reimburse all fees) $2.50-$5.00 out-of-network
    Minimum Balance Usually $0 $500-$5,000 to avoid fees
    Wire Transfers $0-$15 outgoing $25-$45 outgoing
    Paper Statements Usually free $2-$5/month
    Cashier’s Checks Often free $8-$15 each

    Annual Fee Impact:

    Typical customer with traditional bank:

    • Monthly maintenance: $180/year ($15 × 12)
    • Overdraft fees: $70/year (2 incidents)
    • ATM fees: $60/year (out-of-network usage)
    • Total: $310/year

    Same customer with online bank:

    • All fees: $0-$30/year
    • Savings: $280-$310/year

    Combined with higher interest rates, online banks save the average customer $700-$1,000 annually.

    Exception: Traditional banks may waive all fees for premium account holders (typically requiring $25,000-$100,000 in combined deposits and investments).

    Read more: Our banking fees guide shows how to avoid hundreds in unnecessary charges.


    ATM Access: Traditional Banks Edge Ahead

    Traditional Banks WIN for proprietary ATMs, but Online Banks compete well

    Traditional Banks:

    • Large banks operate 15,000-40,000 proprietary ATMs
    • No fees at own-bank ATMs
    • Extensive coverage in urban and suburban areas
    • May charge $2.50-$5.00 at out-of-network ATMs

    Examples:

    • Chase: 16,000 ATMs
    • Bank of America: 16,000 ATMs
    • Wells Fargo: 12,000 ATMs

    Online Banks:

    • No proprietary ATMs (with rare exceptions)
    • Access to large shared networks (Allpoint, MoneyPass, etc.)
    • Many reimburse ALL ATM fees (even out-of-network)
    • Combined network often exceeds 60,000-80,000 ATMs

    Examples:

    • Ally Bank: Reimburses up to $10/month in ATM fees
    • Charles Schwab: Unlimited worldwide ATM fee reimbursement
    • Discover: 60,000+ fee-free ATMs through Allpoint network
    • SoFi: 55,000+ fee-free ATMs

    Winner Depends on Your Situation:

    • Urban/suburban residents: Online banks’ massive shared networks work great
    • Rural residents: Traditional bank’s local branches may have only ATMs for miles
    • International travelers: Online banks with unlimited reimbursement (Schwab) are unbeatable
    • Cash-heavy users: Traditional banks with nearby branches offer easier deposits

    Alternative Solution: Use cash-back at grocery stores and pharmacies (free with debit cards) to reduce ATM dependency entirely.


    Customer Service: Quality vs Availability

    MIXED RESULTS—depends on what you value

    Both bank types offer customer service, but with different strengths.

    Traditional Banks Customer Service

    Strengths:
    ✅ Face-to-face assistance available
    ✅ Can bring complex issues to branch
    ✅ Relationship banking (same banker over time)
    ✅ Immediate help for urgent needs
    ✅ Physical documents and notary services

    Weaknesses:
    ❌ Limited to branch hours (typically 9am-5pm weekdays)
    ❌ May require appointments for specialists
    ❌ Inconsistent service quality between branches
    ❌ Long wait times during peak hours
    ❌ Phone support often routes to call centers anyway

    Customer Satisfaction: 73% (American Customer Satisfaction Index 2024)

    Online Banks Customer Service

    Strengths:
    ✅ 24/7/365 phone support
    ✅ Live chat available anytime
    ✅ Faster response times (no branch congestion)
    ✅ Consistent service quality (centralized training)
    ✅ Screen sharing for complex issues
    ✅ Comprehensive FAQ and video tutorials

    Weaknesses:
    ❌ No in-person option for complex problems
    ❌ Can’t hand someone physical checks or documents
    ❌ May struggle with elderly or tech-averse customers
    ❌ Relationship building harder without face-to-face contact

    Customer Satisfaction: 81% (American Customer Satisfaction Index 2024)

    Surprisingly, online banks score higher in customer satisfaction despite lacking physical presence. Customers appreciate the convenience of 24/7 access and faster resolution times.

    The Verdict

    Choose Traditional if: You value face-to-face relationships, need frequent in-person assistance, or feel more secure with physical presence.

    Choose Online if: You prefer resolving issues from home, need help outside business hours, or rarely visit branches anyway.

    Reality Check: Even traditional bank customers now resolve 85% of issues digitally (app, phone, or website), rarely visiting branches.


    Product Offerings: Traditional Banks Win Breadth

    Traditional Banks WIN for product variety

    Traditional banks typically offer comprehensive financial services under one roof.

    Traditional Bank Product Suite

    Deposit Accounts:

    • Multiple checking account tiers
    • Savings accounts
    • Money market accounts
    • Certificates of deposit (CDs)
    • Individual Retirement Accounts (IRAs)

    Lending Products:

    • Mortgages (purchase and refinance)
    • Home equity loans and lines of credit
    • Auto loans
    • Personal loans
    • Student loans
    • Small business loans
    • Credit cards

    Investment Services:

    • Brokerage accounts
    • Wealth management
    • Financial planning
    • Trust services
    • Estate planning

    Business Banking:

    • Business checking and savings
    • Merchant services
    • Commercial loans
    • Payroll services
    • Business credit cards

    Other Services:

    • Safe deposit boxes
    • Notary services
    • Foreign currency exchange
    • Wire transfers and cashier’s checks

    Online Bank Product Suite

    Typically Offered:

    • High-yield savings accounts
    • Checking accounts (sometimes)
    • CDs
    • Money market accounts
    • Credit cards (some banks)
    • Personal loans (some banks)

    Limited or Not Offered:

    • Mortgages (few online banks offer these)
    • Physical safe deposit boxes
    • In-person wealth management
    • Extensive business banking
    • Foreign currency exchange
    • In-person notary services

    The Cross-Shopping Solution

    Many people maintain accounts at both:

    • Online bank: Primary savings for highest interest rates
    • Traditional bank: Checking for everyday transactions and occasional branch needs

    This hybrid approach captures advantages of both models.

    For comprehensive banking: Our best bank accounts guide compares top options across both categories.


    Mobile Apps and Technology: Online Banks Lead

    Online Banks WIN for technology innovation

    Since online banks exist purely through digital channels, they invest heavily in technology.

    Online Bank Technology Advantages

    Superior Features:

    • Intuitive, streamlined app design
    • Faster updates and new features
    • Better budgeting tools integrated
    • Instant mobile check deposit (higher limits)
    • Advanced security features (biometric, alerts)
    • Seamless digital account opening
    • Real-time balance updates
    • Superior search and filtering

    Innovation Leaders:

    • Person-to-person payments (Zelle, Venmo integration)
    • Early direct deposit (2 days early)
    • Roundup savings features
    • Spending analytics and insights
    • Virtual card numbers for online shopping
    • Freeze/unfreeze cards instantly

    User Experience:
    Online bank apps average 4.6/5 stars in app stores, vs 3.9/5 for traditional bank apps.

    Traditional Bank Technology

    Improving But Lagging:

    • Most now offer solid mobile apps
    • Often feel clunky compared to online-only competitors
    • Legacy systems slow down innovation
    • Multiple acquisitions create inconsistent experiences
    • Branch and digital systems sometimes disconnect

    Advantages:

    • Integration with in-branch services
    • Ability to schedule appointments
    • Branch ATM locators
    • More comprehensive transaction history (decades of data)

    The Gap Is Closing

    Major traditional banks have invested billions in digital transformation:

    • Chase has competitive mobile app
    • Bank of America’s Erica AI assistant
    • Wells Fargo improving digital experience

    However, online banks maintain a 2-3 year technology lead on average, as they can innovate without legacy system constraints.


    Security: Both Are Safe, Different Approaches

    TIE—both are very secure when done properly

    Concerns about online bank security are largely outdated. Both types use similar security measures.

    Universal Security Features (Both Bank Types)

    ✅ FDIC Insurance: Up to $250,000 per depositor, per bank
    ✅ 256-bit Encryption: Military-grade data protection
    ✅ Multi-Factor Authentication: Additional login verification
    ✅ Zero Liability Protection: Not responsible for unauthorized transactions
    ✅ Regular Security Audits: Third-party verification
    ✅ Fraud Monitoring: AI-powered transaction monitoring

    Traditional Bank Security Advantages

    • Physical locations for in-person identity verification
    • Safe deposit boxes for valuables
    • In-person fraud resolution
    • Established decades-long security track record

    Online Bank Security Advantages

    • Often more advanced biometric authentication
    • Real-time transaction alerts (more common)
    • Faster fraud detection through AI
    • No physical branch robbery risk
    • Cutting-edge authentication methods

    The Real Security Risks (Same for Both)

    The biggest security threats come from user behavior, not bank systems:

    ❌ Weak passwords
    ❌ Falling for phishing scams
    ❌ Using public WiFi without VPN
    ❌ Sharing login credentials
    ❌ Not enabling two-factor authentication

    Security Best Practices (Any Bank Type)

    1. Use unique, strong passwords (password manager recommended)
    2. Enable two-factor authentication on all accounts
    3. Monitor accounts weekly for unauthorized transactions
    4. Set up transaction alerts for all purchases
    5. Never click links in emails claiming to be from your bank
    6. Use bank’s official app not web browser on mobile devices
    7. Enable biometric login (fingerprint/face recognition)

    Both bank types are equally secure when you follow proper security practices. Choose based on other factors, not security concerns.


    Cash Deposits: Traditional Banks Win Clearly

    Traditional Banks WIN decisively

    This is the biggest practical limitation of online banks.

    Traditional Banks: Easy Cash Deposits

    • Deposit cash at any branch teller
    • Insert cash into ATMs immediately
    • No limits on deposit amounts
    • Funds typically available same day
    • No fees for cash deposits (at own bank)

    Online Banks: Cash Deposit Challenges

    Limited Options:

    1. ATM Deposits (if available)

    • Some online banks partner with ATM networks allowing deposits
    • Availability varies significantly
    • Often have lower deposit limits
    • Not all online banks offer this

    2. Money Orders

    • Purchase money order with cash
    • Deposit via mobile app
    • Adds cost ($1-2 per money order)
    • Two-step process

    3. Cash-to-Digital Services

    • Services like PayPal, Venmo, Cash App
    • Deposit cash at retailers (CVS, Walgreens, etc.)
    • Transfer to bank account
    • Fees apply ($1-$5 per transaction)

    4. Retail Partnerships

    • Some online banks partner with retailers
    • Examples: Chime at Walgreens, Green Dot at Walmart
    • Fees typically $0-$4.95 per deposit

    5. Keep Traditional Account

    • Maintain fee-free traditional checking
    • Deposit cash there
    • Transfer to online savings
    • Adds complexity but works well

    The Cash Deposit Workaround

    For most people who rarely handle cash, this isn’t a dealbreaker. Solutions:

    • Use credit cards for purchases (cash back benefits)
    • Deposit gift money or side hustle cash at traditional bank
    • Transfer to online bank for higher interest
    • Keep small traditional account specifically for cash needs

    Who Needs Easy Cash Deposits?

    • Service industry workers (tips)
    • Small business owners (cash-heavy businesses)
    • Freelancers paid in cash
    • People receiving frequent cash gifts
    • Those who prefer using cash for budgeting

    If you handle cash regularly, either keep a traditional account or choose an online bank with cash deposit partnerships.
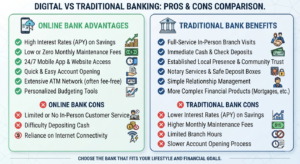


    Account Opening Process: Online Banks Win Speed

    Online Banks WIN for convenience and speed

    Online Banks: Fast Digital Opening

    Process:

    1. Visit website or download app
    2. Enter personal information (5-10 minutes)
    3. Verify identity (Social Security number, driver’s license photo)
    4. Fund initial deposit (electronic transfer or check)
    5. Account approved in minutes to hours

    Timeline: Often approved instantly, sometimes within 24 hours

    Requirements:

    • Government-issued ID
    • Social Security number
    • Residential address
    • Initial deposit (often $0 minimum)
    • Email and phone number

    Advantages:
    ✅ Complete from home in under 15 minutes
    ✅ 24/7 availability
    ✅ Instant approval common
    ✅ All digital—no printing or branch visits
    ✅ Easy to compare multiple banks quickly

    Traditional Banks: Branch or Digital Opening

    In-Branch Process:

    1. Visit branch during business hours
    2. Wait for available representative
    3. Provide identification
    4. Sign physical documents
    5. Make initial deposit (cash or check)

    Timeline: 30-60 minutes in branch, immediate account access

    Online Process (most traditional banks now offer):

    1. Similar to online bank process
    2. May require branch visit for verification
    3. Takes 2-5 business days typically
    4. More paperwork than online-only banks

    Advantages:
    ✅ In-person identity verification (helpful for complex situations)
    ✅ Immediate access to branch services
    ✅ Can ask questions face-to-face
    ✅ Easier for people uncomfortable with technology

    Special Situations

    Bad Credit/ChexSystems:

    • Online banks often more lenient
    • Some specifically cater to second-chance banking
    • Traditional banks may deny based on history

    Non-US Citizens/Residents:

    • Traditional banks sometimes easier for immigrants
    • In-person verification more accommodating
    • Some online banks don’t accept foreign addresses

    Business Accounts:

    • Traditional banks offer more business options
    • May require EIN and business documents
    • Online business banking more limited

    Interest Payment Frequency: Usually Similar

    TIE—most banks pay monthly

    Both online and traditional banks typically pay interest monthly, though specifics vary:

    Standard Practice (Both Types):

    • Interest calculated daily
    • Paid monthly
    • Compounds monthly

    Some Variations:

    • High-yield savings: Monthly
    • CDs: Quarterly or at maturity
    • Checking accounts: Monthly (if any interest paid)

    This rarely factors into bank choice, as the rate matters far more than payment frequency. A 4.50% APY paid monthly vastly outperforms a 0.10% APY paid daily.


    Minimum Balance Requirements: Online Banks Win

    Online Banks WIN for accessibility

    Online Banks

    • Typical minimums: $0-$100 to open
    • To avoid fees: Usually no minimum (fees are already $0)
    • To earn highest APY: Usually $0-$1 minimum

    Examples:

    • Ally Bank: $0 minimum, no fees ever
    • Marcus by Goldman Sachs: $0 minimum
    • Discover Bank: $0 minimum
    • Capital One 360: $0 minimum

    Traditional Banks

    • Typical minimums: $25-$100 to open
    • To avoid fees: $500-$5,000 average daily balance
    • Alternative: Direct deposit of $500-$2,000/month

    Examples:

    • Chase: $1,500 minimum OR $500/month direct deposit
    • Bank of America: $500 minimum OR $250/month direct deposit
    • Wells Fargo: $500 minimum OR 10 debit card transactions/month

    Impact:

    For someone who maintains a $2,000 average balance:

    • Online bank: Earns 4.50% = $90/year
    • Traditional bank: Pays $0 fee but earns 0.05% = $1/year
    • Difference: $89/year just for choosing online

    For someone who can’t maintain minimums:

    • Online bank: $0 fees
    • Traditional bank: $180/year in monthly fees ($15 × 12)

    Online banks remove the barrier to entry and the penalty for low balances, making them more accessible to people building emergency funds or living paycheck to paycheck.


    Check Writing and Bill Pay: Similar Features

    TIE—both offer comparable services

    Both bank types provide checking accounts with similar features:

    Check Writing

    • Traditional banks: Free checks (sometimes) or $20-30 for order
    • Online banks: Usually free first box, then similar pricing
    • Reality: Check usage declining 7% annually; most bills paid electronically

    Bill Pay Services

    • Traditional banks: Free online bill pay with most checking accounts
    • Online banks: Free online bill pay standard
    • Both offer: Scheduled payments, recurring bills, payee management

    Mobile Check Deposit

    • Traditional banks: Available in most apps, $1,000-$5,000 daily limits
    • Online banks: Often higher limits ($10,000-$25,000), faster processing
    • Winner: Online banks slightly better (higher limits, faster deposits)

    Direct Deposit

    • Both types: Full support for direct deposit
    • Online banks edge: Some offer early direct deposit (2 days before payday)
    • Examples: Chime, Current, Varo offer early access to paychecks

    Overdraft Protection: Online Banks Improving

    Online Banks WINNING the innovation race

    Traditional banks generate billions from overdraft fees—online banks are disrupting this.

    Traditional Banks

    • Standard overdraft fee: $30-$35 per transaction
    • Multiple fees per day: Can charge 3-4 times daily (up to $140 in one day)
    • NSF fees: $35 even when transaction declines
    • Protection options: Link to savings (often still charges fee)

    2024 Changes: Many traditional banks reduced fees to $10-15 or eliminated NSF fees due to regulatory pressure.

    Online Banks

    • Many charge $0: Ally, Discover, Capital One 360, Chime, SoFi
    • Low fees if charged: $15-25 maximum
    • Innovative features:
      • Chime SpotMe: Free overdraft up to $200
      • SoFi: No fees, plus APY on overdraft protection
      • Ally: No overdraft fees period
      • Current: $200 instant overdraft coverage

    Annual Savings:

    Average customer with occasional overdrafts:

    • Traditional bank: 3 overdrafts × $35 = $105/year
    • Online bank: $0/year

    Read our comprehensive guide on avoiding banking fees for more strategies.


    International Services: Mixed Results

    Traditional Banks WIN for comprehensive international services

    Traditional Banks Advantages

    Currency Exchange:

    • Physical locations offer foreign currency
    • Can order currency for pickup
    • Exchange rates (though not best available)

    International Wires:

    • In-person wire transfer setup
    • Staff familiar with international requirements
    • Troubleshooting with banker support

    Worldwide Presence:

    • Major banks have international branches
    • Easier if relocating abroad
    • In-person service when traveling

    Online Banks Advantages

    Lower Fees:

    • Many charge $0 foreign transaction fees
    • Better currency conversion rates
    • No international ATM fees (with reimbursement)

    Best for Travelers:

    • Charles Schwab: Unlimited worldwide ATM fee reimbursement + $0 foreign transaction fees
    • Capital One 360: No foreign transaction fees
    • Discover: No foreign transaction fees

    Digital Convenience:

    • Manage international transactions from anywhere
    • 24/7 customer service across time zones

    Best Solution

    • Frequent international travelers: Online bank with no foreign fees + traditional bank for currency exchange if needed
    • Expatriates: Traditional bank with international presence
    • Occasional travelers: Online bank with fee reimbursement (Charles Schwab, Discover)
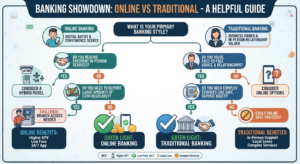

    Who Should Choose Online Banks?

    Online banks are ideal if you:

    ✅ Rarely need to deposit cash (less than monthly)
    ✅ Want to maximize savings interest (every percentage point matters)
    ✅ Prefer managing finances digitally (comfortable with apps and websites)
    ✅ Want to minimize banking fees (every dollar saved counts)
    ✅ Don’t need in-person service (comfortable with phone/chat support)
    ✅ Travel internationally frequently (ATM fee reimbursement valuable)
    ✅ Are building emergency fund (high APY accelerates progress)
    ✅ Live in urban/suburban area (good ATM network access)
    ✅ Use direct deposit (funds arrive electronically)
    ✅ Bank primarily through mobile app (already use digital banking)

    Ideal Online Bank Customer Profiles

    Young Professional:

    • Age 25-40
    • Tech-savvy
    • Salary direct deposited
    • Minimal cash handling
    • Focused on building savings
    • Values high interest rates

    Digital Nomad/Remote Worker:

    • Works from anywhere
    • Needs 24/7 banking access
    • No loyalty to local branches
    • International ATM access important
    • Appreciates technology

    Serious Saver:

    • Building emergency fund or down payment
    • Every 0.1% APY matters
    • Minimal fees important
    • Doesn’t need extensive services
    • Focused purely on deposit accounts

    Who Should Choose Traditional Banks?

    Traditional banks are ideal if you:

    ✅ Frequently deposit cash (weekly or more)
    ✅ Value in-person relationships (prefer face-to-face banking)
    ✅ Need complex financial services (mortgages, wealth management, business banking)
    ✅ Live in rural areas (limited ATM network access)
    ✅ Prefer branch convenience (ATMs, safe deposit boxes, notary)
    ✅ Are uncomfortable with technology (prefer human assistance)
    ✅ Have complex financial situations (multiple businesses, trusts, estates)
    ✅ Need multiple products (prefer one institution for everything)
    ✅ Value established institutions (decades of stability and reputation)
    ✅ Require safe deposit box (store valuables physically)

    Ideal Traditional Bank Customer Profiles

    Small Business Owner:

    • Handles cash regularly
    • Needs business loans and merchant services
    • Values banker relationships
    • Requires in-person deposit capabilities
    • Uses multiple financial products

    Older Adult:

    • Less comfortable with technology
    • Values personal relationships
    • Prefers in-person problem solving
    • Long-time customer of institution
    • Appreciates branch convenience

    Complex Financial Situation:

    • Multiple income streams
    • Real estate investments
    • Needs wealth management
    • Trusts and estate planning
    • Prefers one institution for all services

    Rural Resident:

    • Limited high-speed internet access
    • Few ATM options besides local branch
    • Values community banking
    • Knows local branch staff
    • Limited online bank ATM networks

    The Hybrid Approach: Best of Both Worlds

    Many financially savvy people use both bank types strategically:

    Common Hybrid Strategies

    Strategy 1: Online Savings + Traditional Checking

    Setup:

    • High-yield online savings for emergency fund (4-5% APY)
    • Traditional checking for daily transactions
    • Link accounts for easy transfers

    Benefits:

    • Maximum interest on savings
    • Easy cash deposits when needed
    • Branch access for occasional needs
    • Best rates without sacrificing convenience

    Best For: Most people seeking optimal combination of rates and convenience


    Strategy 2: Online Primary + Traditional Backup

    Setup:

    • Online bank for primary checking and savings
    • Local credit union or small bank (fee-free) as backup
    • Minimal balance at traditional bank

    Benefits:

    • High rates and low fees on primary accounts
    • Cash deposit capability when needed
    • Emergency branch access
    • Essentially free (no minimum balance fees at many credit unions)

    Best For: People who rarely need branches but want occasional access


    Strategy 3: Traditional Relationship + Online Savings

    Setup:

    • Traditional bank for checking, loans, credit cards
    • Online bank purely for highest-yield savings
    • Keep majority of liquid savings at online bank

    Benefits:

    • Relationship benefits at traditional bank (loan rates, fee waivers)
    • Maximum interest on savings
    • Full service availability
    • Convenient primary banking

    Best For: People with complex banking needs who want to optimize savings returns


    Strategy 4: Multiple Online Banks

    Setup:

    • Different online banks for different purposes
    • One for emergency fund (highest APY)
    • Another for spending money (best checking features)
    • Third for specific savings goals

    Benefits:

    • Optimize each account type
    • FDIC insurance across multiple banks ($250K × number of banks)
    • Psychological separation of funds
    • Take advantage of sign-up bonuses

    Best For: Financial enthusiasts comfortable managing multiple accounts


    Making the Hybrid Approach Work

    Tips for Success:

    1. Link all accounts in one app (Mint, Personal Capital, YNAB) for unified view
    2. Automate transfers between banks on payday
    3. Keep systems simple (2-3 banks maximum for most people)
    4. Document account purposes (which bank for what)
    5. Review quarterly to ensure strategy still makes sense

    Common Pitfall to Avoid:

    Don’t open so many accounts that you lose track. More than 3-4 banks becomes unnecessarily complex for most people.


    How to Switch Banks Successfully

    If you’re ready to switch from traditional to online (or vice versa), follow this process:

    Phase 1: Research and Choose (Week 1)

    •  Compare banks using our best bank accounts guide
    •  Read current customer reviews
    •  Verify FDIC insurance
    •  Confirm ATM access in your area
    •  Check current interest rates and fees

    Phase 2: Open New Account (Week 2)

    •  Apply online (10-15 minutes)
    •  Fund with initial deposit
    •  Download mobile app
    •  Set up online account access
    •  Verify identity if required
    •  Order debit card and checks

    Phase 3: Parallel Operation (Weeks 3-6)

    DO NOT close old account yet

    •  Set up direct deposit to new account
    •  Redirect automatic bill payments (one at a time)
    •  Update payment information with merchants
    •  Keep old account open with minimal balance
    •  Monitor both accounts for missed transfers

    Update One Bill Per Day Strategy:

    • Day 1: Electric company
    • Day 2: Water/sewer
    • Day 3: Internet/cable
    • Day 4: Phone bill
    • Day 5: Insurance
    • Continue until all transferred

    Phase 4: Close Old Account (Week 7+)

    Only after everything has transferred successfully:

    •  Verify zero pending transactions
    •  Ensure all direct deposits redirected
    •  Confirm all automatic payments switched
    •  Transfer remaining balance to new account
    •  Call old bank to close account
    •  Request confirmation letter
    •  Destroy old debit cards and checks

    Common Switching Mistakes to Avoid

    ❌ Closing old account too quickly (wait at least 30 days after final transfer)
    ❌ Forgetting annual bills (check last 12 months of statements)
    ❌ Not keeping records (save all confirmation numbers)
    ❌ Switching everything at once (transfer one payment at a time)
    ❌ Insufficient buffer (keep $100-200 extra during transition)


    Frequently Asked Questions

    Are online banks as safe as traditional banks?

    Yes, when FDIC insured. Online banks offer identical $250,000 FDIC insurance protection. They use the same 256-bit encryption and security protocols. The difference is access method (digital vs physical), not security level. Always verify FDIC insurance at FDIC.gov before opening any account.

    Can I deposit cash into an online bank account?

    Options are limited but available: some online banks partner with retail locations (Chime at Walgreens, Chime at CVS), you can purchase money orders and mobile deposit them, use cash-to-digital services like PayPal at retailers, or maintain a traditional account for cash deposits and transfer to online bank. Most online bank customers rarely deposit cash, so this isn’t a dealbreaker.

    Do online banks have better interest rates than traditional banks?

    Dramatically better. Online banks typically offer 40-500x higher interest rates on savings accounts. As of 2025, online savings accounts pay 4-5% APY while traditional banks average 0.01-0.10% APY. This difference translates to hundreds or thousands of dollars annually on typical savings balances.

    What happens if an online bank goes out of business?

    Same as traditional banks: FDIC insurance protects up to $250,000 per depositor. If the bank fails, FDIC either transfers accounts to another institution or mails you a check within a few days. You won’t lose insured deposits. This is why verifying FDIC insurance is critical before opening any account.

    Can I get a mortgage or car loan from an online bank?

    Some online banks offer these products, but options are more limited than traditional banks. Many online banks focus exclusively on deposit accounts. If you need loans, either choose an online bank that offers them (SoFi, Ally, Discover) or maintain a relationship with a traditional bank for lending needs while keeping savings at an online bank for better rates.

    Do online banks charge monthly fees?

    Most don’t. Approximately 98% of online banks charge $0 monthly maintenance fees with no minimum balance requirements. This is a major advantage over traditional banks, which typically charge $10-25/month unless you maintain $500-$5,000 minimum balances or meet other conditions like direct deposit.

    How long does it take to transfer money between online and traditional banks?

    ACH transfers typically take 1-3 business days. Some banks offer same-day or next-day transfers for a fee. Wire transfers are same-day but cost $15-45. Most online banks allow you to link external accounts and transfer freely. For emergencies, keep enough buffer in your spending account to cover 3-5 days of transfers.

    Can I have both an online bank and traditional bank?

    Absolutely, and many people do. This hybrid approach captures advantages of both: high interest rates from online banks and occasional branch access from traditional banks. Link the accounts for easy transfers and use each for its strengths—traditional for cash deposits, online for savings growth.

    Are traditional banks going away?

    No, but they’re evolving. Branch count has declined 30% since 2010, but traditional banks still serve millions who value in-person service. They’re investing heavily in digital capabilities while maintaining physical presence. The future likely includes fewer branches but not elimination—especially for complex services like wealth management and business banking.


    The Future of Banking: What’s Coming

    Understanding emerging trends helps you make forward-looking decisions.

    Trend 1: Branch Consolidation

    Traditional banks closing 3,000-4,000 branches annually, focusing on:

    • Flagship locations in high-traffic areas
    • Smaller “express” branches
    • Appointment-based specialty branches
    • Hybrid models with digital kiosks

    Impact: Less convenient branch access even for traditional bank customers

    Trend 2: Enhanced Digital Experiences

    Both bank types investing billions in:

    • AI-powered financial guidance
    • Predictive analytics for spending
    • Voice-activated banking
    • Instant person-to-person payments
    • Integrated budgeting tools

    Impact: Gap between online and traditional narrowing on technology

    Trend 3: Fee Elimination

    Regulatory pressure and competition driving:

    • Overdraft fee reductions or eliminations
    • Free checking becoming standard
    • Transparent pricing requirements
    • Elimination of “junk fees”

    Impact: Traditional banks becoming more price-competitive with online banks

    Trend 4: Banking-as-a-Service

    Non-banks offering banking through partnerships:

    • Apple Card (via Goldman Sachs)
    • Google partnership with Citibank
    • Amazon exploring banking services
    • Walmart financial services

    Impact: More choices, more specialization, potentially better features

    Trend 5: Cryptocurrency Integration

    Some banks exploring:

    • Crypto custody services
    • Bitcoin/Ethereum purchases
    • Blockchain-based transfers
    • Stablecoin accounts

    Impact: Uncertain, but banking will adapt to include digital currencies


    Take Action: Your Banking Decision Checklist

    Use this worksheet to determine your best banking solution:

    Your Banking Needs Assessment

    Rate each factor 1-5 (1 = unimportant, 5 = critical):

    •  Highest possible interest rates: ____
    •  Minimal fees: ____
    •  In-person customer service: ____
    •  Easy cash deposit access: ____
    •  Branch/ATM proximity: ____
    •  Advanced mobile app: ____
    •  Comprehensive product offerings: ____
    •  Established brand reputation: ____
    •  24/7 customer service: ____
    •  Safe deposit box access: ____

    Scoring:

    Online Bank If:

    • You rated “highest interest rates” as 4-5
    • You rated “minimal fees” as 4-5
    • You rated “advanced mobile app” as 4-5
    • You rated “in-person service” as 1-2
    • You rated “cash deposits” as 1-2

    Traditional Bank If:

    • You rated “in-person service” as 4-5
    • You rated “cash deposits” as 4-5
    • You rated “branch proximity” as 4-5
    • You rated “comprehensive products” as 4-5
    • You rated “interest rates” as 1-2

    Hybrid Approach If:

    • You have mix of high ratings across both categories
    • You rated “interest rates” AND “in-person service” both 4-5
    • You want to optimize multiple factors

    Conclusion: The Right Choice Is Personal

    There’s no universally “better” option between online and traditional banks—only the better option for your specific situation.

    Choose online banks if you prioritize financial optimization, rarely handle cash, embrace technology, and want every dollar working hardest for you through high interest and zero fees.

    Choose traditional banks if you value personal relationships, need frequent cash deposits, require comprehensive services under one roof, or prefer the comfort of physical branches.

    Choose both if you want to optimize savings returns while maintaining occasional branch access—the hybrid approach works beautifully for many people.

    The key insights to remember:

    ✅ Interest rate difference is substantial: 4.50% vs 0.05% means $445 annually on $10,000
    ✅ Fee difference adds up: Average customer saves $280-310 yearly at online banks
    ✅ Security is equivalent: Both have FDIC insurance and bank-level security
    ✅ Technology gap exists: Online banks innovate faster
    ✅ Cash deposits remain challenging: Biggest practical limitation of online banks
    ✅ Hybrid approach works: Many people successfully use both types

    The banking landscape has fundamentally changed. The traditional model of one bank for all services no longer makes financial sense for many consumers. Strategic use of multiple banks—taking the best of each—often delivers superior results.

    Start by honestly assessing your actual banking behavior (not what you think you should do, but what you really do). If you haven’t visited a branch in six months, paying hundreds annually in lost interest and fees for that “convenience” makes little sense.

    Make your banking work for you, not the other way around.

    Ready to optimize your complete banking strategy?

  • Banking Fees to Avoid: Save Hundreds on Hidden Charges

    Banking Fees to Avoid: Save Hundreds on Hidden Charges

    Did you know the average American pays over $329 per year in banking fees? That’s money disappearing from your account for things you might not even realize you’re being charged for.

    Banks collected a staggering $8.4 billion in overdraft fees alone in 2023, according to the Consumer Financial Protection Bureau. Add monthly maintenance fees, ATM charges, wire transfer costs, and dozens of other “convenience” fees, and you’re looking at hundreds—sometimes thousands—of dollars annually.

    The worst part? Most of these fees are completely avoidable.

    Banks count on customers not reading the fine print or understanding their fee schedules. They design complex fee structures that catch even financially savvy people off guard. A single oversight—like letting your account dip $5 below the minimum balance—can trigger a cascade of charges.

    But here’s the good news: once you understand the most common banking fees and how they work, you can easily sidestep them and keep that money where it belongs—in your pocket.

    In this comprehensive guide, you’ll discover the 15 most common banking fees, exactly how to avoid each one, and which banks offer truly fee-free alternatives.

    Let’s stop giving away your hard-earned money.


    The True Cost of Banking Fees

    Before diving into specific fees, let’s understand the bigger picture.

    How Much Are Banking Fees Really Costing You?

    According to a 2024 Bankrate study, here’s what the average consumer pays annually:

    • Monthly maintenance fees: $180 ($15/month × 12 months)
    • Overdraft fees: $105 (3 incidents × $35)
    • ATM fees: $72 (out-of-network usage)
    • Minimum balance fees: $60
    • Wire transfer fees: $45
    • Miscellaneous charges: $67

    Total Average Annual Banking Fees: $529

    That’s more than most Americans have in their savings account! Over 10 years, these fees could cost you $5,290—money that could be earning interest instead.

    Why Banks Charge So Many Fees

    Banks aren’t just providing services—they’re profit-driven businesses. Fee income represents a significant revenue stream:

    1. Predictable Revenue: Unlike interest rates that fluctuate, fees provide consistent income
    2. Low Customer Awareness: Many people don’t monitor small charges closely
    3. Competitive Pressure: Low interest rates forced banks to find alternative revenue sources
    4. Psychological Pricing: Small monthly fees seem less painful than higher interest rates

    Understanding this helps you realize: banks design fee structures to maximize their profits, not your financial health.


    The 15 Most Common Banking Fees (And How to Avoid Them)

    1. Monthly Maintenance Fees ($10-$35/month)

    What It Is:
    A recurring charge simply for keeping your account open, regardless of whether you use it.

    Average Cost: $15/month = $180/year

    How to Avoid It:

    ✅ Choose fee-free banks: Many online banks like Ally, Discover, and Capital One 360 charge zero monthly fees

    ✅ Meet minimum balance requirements: Traditional banks often waive fees if you maintain $1,500-$5,000 balance

    ✅ Set up direct deposit: Most banks waive fees with regular direct deposits ($500-$1,500/month)

    ✅ Link multiple accounts: Some banks waive fees when you have checking, savings, and credit cards together

    ✅ Student/senior accounts: Many banks offer fee-free accounts for students under 24 or seniors over 62

    Pro Tip: If you’re paying monthly fees, call your bank and ask them to waive them. Many will—especially if you threaten to switch banks. Read our guide to the best fee-free bank accounts for 2025 for alternatives.


    2. Overdraft Fees ($25-$38 per transaction)

    What It Is:
    A charge when you spend more money than you have in your account and the bank covers the transaction.

    Average Cost: $35 per occurrence (some people get hit multiple times in one day)

    The Hidden Trap: Banks process largest transactions first, maximizing the number of overdrafts. Example:

    • You have $100 in your account
    • You make three $20 purchases and one $80 purchase
    • Bank processes the $80 first, then each $20 triggers a separate $35 fee
    • Result: 3 overdraft fees = $105 in charges for spending $40 over your limit

    How to Avoid It:

    ✅ Opt out of overdraft protection: This prevents charges from going through if you lack funds (better a declined card than $35 fee)

    ✅ Link to savings account: Most banks offer free transfers from savings to cover overdrafts

    ✅ Set up low balance alerts: Get text/email when balance drops below your threshold

    ✅ Use budgeting apps: Apps like Mint or YNAB help track spending in real-time

    ✅ Keep a buffer: Mentally treat $100 as your “zero” balance

    ✅ Choose banks with no overdraft fees: Ally Bank, Discover, and Chime don’t charge overdraft fees at all

    Recent Changes: As of 2024, many major banks reduced overdraft fees or eliminated them entirely due to regulatory pressure. Check if your bank has updated policies.


    3. Non-Sufficient Funds (NSF) Fees ($25-$38)

    What It Is:
    Similar to overdraft, but the bank declines the transaction and still charges you.

    Average Cost: $34 per occurrence

    How to Avoid It:

    ✅ Same strategies as overdraft fees

    ✅ Monitor your account daily: Set up mobile banking and check each morning

    ✅ Use real-time banking apps: Many apps show pending transactions immediately

    ✅ Build an emergency buffer: Keep an extra $100-300 you don’t touch

    Important Note: As of 2024, the CFPB has proposed limiting NSF fees to $8. Check if your bank has adopted these changes.


    4. ATM Fees ($2.50-$5.00 per transaction)

    What It Is:
    Two-part charge when using out-of-network ATMs:

    1. Your bank charges you ($2-3)
    2. The ATM owner charges you ($2-3)

    Average Cost: $4.73 per out-of-network withdrawal

    How to Avoid It:

    ✅ Use only in-network ATMs: Check your bank’s ATM locator app

    ✅ Get cash back at stores: Free with debit card purchases at grocery stores, pharmacies

    ✅ Choose banks with ATM reimbursement: Schwab Bank, Ally, and some credit unions refund ALL ATM fees worldwide

    ✅ Plan cash needs: Withdraw larger amounts less frequently from in-network ATMs

    ✅ Use digital payments: Apple Pay, Google Pay, Venmo reduce cash needs

    Best for Frequent Travelers: If you travel internationally, Schwab Bank’s checking account reimburses ALL worldwide ATM fees and charges no foreign transaction fees. Learn more about high-yield savings accounts with great checking features.


    5. Minimum Balance Fees ($5-$15/month)

    What It Is:
    A monthly charge if your average daily balance falls below the required minimum (typically $500-$5,000).

    Average Cost: $12/month = $144/year

    How to Avoid It:

    ✅ Switch to no-minimum banks: Online banks rarely have minimum balance requirements

    ✅ Link accounts: Transfer money from savings before the monthly calculation

    ✅ Understand calculation periods: Know if your bank uses daily average, monthly average, or end-of-month balance

    ✅ Set up alerts: Get notified when approaching minimum threshold

    Reality Check: If maintaining a $5,000 minimum balance to avoid a $15 fee, you’re essentially earning 0.3% annual return on that money. A high-yield savings account at 4-5% would earn you $200-250 annually instead.


    6. Wire Transfer Fees ($15-$50 per transfer)

    What It Is:
    Charges for sending or receiving money electronically, especially internationally.

    Typical Costs:

    • Domestic outgoing: $25-35
    • International outgoing: $35-50
    • Incoming wires: $10-15

    How to Avoid It:

    ✅ Use ACH transfers instead: Free and only take 1-3 days (vs instant wires)

    ✅ Use Zelle, Venmo, or Cash App: Free for domestic transfers

    ✅ Use Wise (formerly TransferWise): Much cheaper for international transfers ($5-15 vs $45)

    ✅ Ask the sender to use alternatives: If receiving money, suggest fee-free methods

    ✅ Negotiate with your bank: Some will waive fees for premium account holders

    When You Might Need Wires: Real estate closings, large business transactions, or urgent international transfers. For everything else, free alternatives work fine.


    7. Paper Statement Fees ($2-$5/month)

    What It Is:
    Monthly charge for receiving paper statements by mail instead of electronic delivery.

    Average Cost: $3/month = $36/year

    How to Avoid It:

    ✅ Go paperless: Sign up for e-statements (better for environment too!)

    ✅ Download PDFs monthly: Save statements to your computer for records

    ✅ Use account aggregators: Apps like Mint store transaction history

    Bonus: Many banks offer small bonuses ($25-50) for switching to paperless statements.


    8. Excessive Transaction Fees ($5-$10 per transaction)

    What It Is:
    Federal Regulation D previously limited savings account withdrawals to 6 per month. While the rule was suspended in 2020, some banks still charge fees for “excessive” transactions.

    Average Cost: $10 per transaction over the limit

    How to Avoid It:

    ✅ Know your bank’s policy: Check if they still enforce transaction limits

    ✅ Use checking for frequent transactions: Keep spending money in checking, savings for… saving

    ✅ Plan transfers strategically: Move money in fewer, larger transfers

    ✅ Automate wisely: Set up automatic transfers that don’t count toward limits


    9. Foreign Transaction Fees (1-3% of purchase)

    What It Is:
    A percentage charged when you use your debit card for purchases in foreign currencies or from international merchants.

    Average Cost: 3% of every international purchase

    Example: $2,000 vacation spending = $60 in fees

    How to Avoid It:

    ✅ Use fee-free debit cards: Schwab, Capital One 360, and Discover charge no foreign transaction fees

    ✅ Use credit cards instead: Many travel credit cards have no foreign transaction fees and offer better fraud protection

    ✅ Withdraw local currency smartly: Use ATMs over currency exchange kiosks (better rates)

    ✅ Notify your bank: Prevents your card being frozen for “suspicious” international activity

    For Frequent Travelers: The Schwab Bank Investor Checking account has zero foreign transaction fees AND reimburses all ATM fees worldwide.


    10. Account Closure Fees ($25-$50)

    What It Is:
    A fee charged when closing your account, especially if you close it within 90-180 days of opening.

    Average Cost: $25-50

    How to Avoid It:

    ✅ Keep accounts open for 6+ months: Most fees only apply to early closures

    ✅ Ask before closing: Some banks will waive fees if you ask

    ✅ Transfer to zero-balance: Some banks allow you to leave account dormant instead

    ✅ Read terms when opening: Know the early closure policy upfront

    Tip: If you opened an account for a bonus, check the fine print for minimum holding periods.


    11. Replacement Card Fees ($5-$25)

    What It Is:
    Charge for replacing lost, stolen, or damaged debit cards, especially expedited delivery.

    Typical Costs:

    • Standard replacement: Often free
    • Expedited shipping: $15-25

    How to Avoid It:

    ✅ Use standard shipping: Free but takes 7-10 days

    ✅ Use digital wallets: Apple Pay/Google Pay work even without physical card

    ✅ Keep card secure: Prevention is best—use card holder, regularly check wallet

    ✅ Ask for fee waiver: If it’s your first replacement, many banks won’t charge


    12. Cashier’s Check or Money Order Fees ($5-$15)

    What It Is:
    Fee for issuing certified bank checks, often required for large purchases or deposits.

    Average Cost: $10 per check

    How to Avoid It:

    ✅ Use personal checks: Free for everyday use

    ✅ Premium accounts: Often include free cashier’s checks

    ✅ Credit unions: Typically charge less ($3-5) than big banks

    ✅ Electronic transfers: ACH or wire transfers may be cheaper for some purposes

    When You Need Them: Real estate deposits, car purchases, or when a recipient requires guaranteed funds.


    13. Stop Payment Fees ($20-$35)

    What It Is:
    Fee charged to stop a check you’ve written from being cashed.

    Average Cost: $30 per stop payment order

    How to Avoid It:

    ✅ Use electronic payments: Can be cancelled before processing

    ✅ Be careful with checks: Only write them when certain

    ✅ Close account if necessary: Sometimes cheaper than multiple stop payments (though creates other issues)

    ✅ Negotiate: Banks sometimes waive fees for fraud situations


    14. Dormant Account Fees ($5-$20/month)

    What It Is:
    Monthly fee charged on accounts with no activity for 6-12 months.

    Average Cost: $10/month (can drain entire account!)

    How to Avoid It:

    ✅ Make small transactions: Even $1 deposit/withdrawal resets the clock

    ✅ Set up automatic transfers: $10 monthly transfer between accounts

    ✅ Close unused accounts: Better to close than let fees accumulate

    ✅ Set calendar reminders: Check all accounts quarterly

    Warning: Some states have “abandoned property” laws where dormant accounts get turned over to the state. Keep accounts active!


    15. Account Research or Statement Copy Fees ($5-$25 per request)

    What It Is:
    Fee for requesting old statements, transaction histories, or account research beyond normal timeframes.

    Average Cost: $5 per statement, $25 for detailed research

    How to Avoid It:

    ✅ Download statements regularly: Save monthly PDFs to your computer

    ✅ Use bank’s online history: Most banks provide 12-24 months free online

    ✅ Keep tax-related records: Save relevant statements during tax season

    ✅ Screenshot important transactions: Quick reference without formal requests


    Special Fee Considerations for Different Account Types

    Business Account Fees

    Business accounts typically have MORE fees than personal accounts:

    • Monthly maintenance: $15-30
    • Transaction fees: $0.30-0.50 per transaction over limit
    • Cash deposit fees: $5-10 per deposit
    • Check deposits: $0.10-0.30 per check

    How to Minimize:

    • Use business accounts designed for small businesses (lower limits)
    • Consider online business banking (fewer fees)
    • Bundle services for fee waivers

    Student Account Fees

    Student accounts usually have FEWER fees:

    • Often no monthly maintenance until age 24-25
    • Lower minimum balances
    • Free checks sometimes included

    What to Watch:

    • Automatic conversion to regular account when you graduate
    • Fee schedule changes after age limit

    Senior Account Fees

    Senior accounts (typically 55-65+) often feature:

    • Waived monthly fees
    • Free checks
    • Free cashier’s checks
    • Lower minimum balances

    Best Banks for Seniors:

    • Credit unions often have best senior programs
    • Regional banks may offer better terms than national banks

    How to Negotiate Banking Fees

    Banks often waive fees if you simply ask. Here’s how:

    The Fee Waiver Script

    For one-time fees (overdraft, NSF):

    “Hello, I’m a loyal customer and this is my first [fee type] in [timeframe]. I’ve already taken steps to prevent this happening again. Would you be willing to waive this fee as a courtesy?”

    Success rate: 60-70% for first offense

    For recurring fees (monthly maintenance):

    “I’m reviewing my banking costs and noticed I’m paying $[amount] monthly in maintenance fees. I see [competitor bank] offers similar accounts with no fees. I’d prefer to stay with you—can you match their offer or suggest a fee-free option?”

    Success rate: 40-50% depending on your relationship and bank policies

    When to Escalate

    If the first representative says no:

    1. Politely ask to speak with a supervisor or retention specialist
    2. Mention specific competitor offers by name
    3. Reference your account history (years as customer, total deposits, etc.)
    4. Be prepared to actually switch if they won’t budge

    Best Time to Call: Mid-week mornings (Tuesday-Thursday, 10am-2pm) when call volume is lower and representatives are less rushed.


    The Best Fee-Free Banking Alternatives

    If you’re tired of fighting fees, consider these genuinely fee-free options:

    Top Online Banks with No Fees

    1. Ally Bank

    2. Capital One 360

    • No monthly fees
    • No minimum balance
    • Free overdraft protection
    • 70,000+ fee-free ATMs

    3. Discover Bank

    • No monthly fees on checking or savings
    • Rebates all ATM fees nationwide
    • $0 stop payment fees
    • $0 cashier’s checks

    4. Chime

    • Zero fees across the board
    • No overdraft fees (SpotMe feature covers up to $200)
    • Get paid 2 days early with direct deposit
    • 60,000+ fee-free ATMs

    5. SoFi

    • No account fees
    • Up to 4.00% APY on checking with direct deposit
    • Fee-free ATMs worldwide
    • $0 overdraft fees

    Credit Union Advantages

    Credit unions typically charge 30-40% lower fees than traditional banks:

    • Lower or no monthly maintenance fees
    • Smaller overdraft fees ($20-28 vs $35)
    • Free cashier’s checks
    • Better loan rates

    How to Find One:
    Visit MyCreditUnion.gov to find credit unions you’re eligible to join based on location, employer, or affiliations.


    Creating Your Fee-Free Banking Strategy

    The 30-Day Fee Elimination Plan

    Week 1: Audit Current Fees

    • Download last 3 months of statements
    • Highlight every fee charged
    • Calculate annual cost
    • Identify your 3 biggest fee sources

    Week 2: Research Alternatives

    Week 3: Negotiate or Switch

    • Call current bank with specific requests
    • If unsuccessful, open new account (keep old one open initially)
    • Transfer direct deposits and automatic payments
    • Set up new account monitoring

    Week 4: Complete Transition

    • Ensure all transfers to new account are working
    • Verify no pending transactions on old account
    • Close old account (if switching)
    • Set up fee prevention systems (alerts, buffers, etc.)

    Essential Fee Prevention Systems

    1. Account Alerts
    Set up notifications for:

    • Balance drops below $100
    • Any fee charged
    • Large transactions over $X
    • Weekly account summaries

    2. Buffer Strategy

    • Keep $100-300 “invisible” buffer you never touch
    • Mentally treat this as your $0 balance
    • Reduces overdraft risk dramatically

    3. Automatic Monitoring

    • Link to Mint, Personal Capital, or YNAB
    • Review weekly (5-minute habit)
    • Reconcile monthly

    4. Calendar Reminders

    • Quarterly account review (check for new fees)
    • Annual bank shopping (ensure you still have best deal)
    • Review fee schedule changes (banks must notify you)

    Understanding Bank Fee Disclosures

    How to Read Fee Schedules

    Banks are legally required to disclose fees, but they don’t make it easy.

    Where to Find Full Fee Disclosures:

    1. “Fee Schedule” or “Pricing Information” on bank’s website
    2. “Terms and Conditions” document
    3. Account agreement paperwork
    4. Ask representative for “complete fee schedule”

    Red Flags to Watch For:

    • “Up to” language (fee could be higher)
    • “May charge” (discretionary fees)
    • Complex calculation methods
    • Fees for services that should be free

    Your Legal Rights Regarding Fees

    Regulation E (Electronic Fund Transfer Act):

    • Banks must disclose all fees before you open account
    • You must consent to overdraft coverage
    • Right to opt-out of overdraft protection
    • Banks must notify you of fee schedule changes

    Truth in Savings Act:

    • Banks must clearly disclose APY and fees
    • Can’t advertise “free checking” if monthly fees apply
    • Must provide annual percentage yield (APY) accurately

    Your Rights:
    ✅ Receive fee schedule before opening account
    ✅ Opt out of overdraft “protection”
    ✅ 60 days to dispute unauthorized charges
    ✅ Notification of fee increases


    Frequently Asked Questions About Banking Fees

    Can banks charge fees without warning?

    For existing accounts, banks must notify you 30 days before implementing new fees or increasing existing ones. However, they can bury this notice in your statement, so review carefully. For new accounts, all fees must be disclosed before you open the account.

    Are online banks safer than traditional banks?

    Yes, if they’re FDIC insured (look for FDIC logo and verify at FDIC.gov). Online banks are actually less likely to charge fees because they have lower overhead costs. Many online banks offer BETTER security features like 2-factor authentication and biometric login.

    What’s the difference between overdraft and NSF fees?

    Both occur when you don’t have enough money, but:

    • Overdraft fee: Bank covers the transaction and charges you ($35)
    • NSF fee: Bank declines the transaction and still charges you ($35)

    Same cost, different outcomes. Both are avoidable by opting out of overdraft coverage and monitoring your balance.

    Can I get past fees refunded?

    Sometimes! Banks typically refund:

    • First-time overdraft fees (60-80% success rate)
    • Fees caused by bank errors (always)
    • Multiple fees in one day (sometimes they’ll refund all but one)

    Call customer service, be polite, explain the situation, and ask specifically for a “courtesy refund.” The answer is always no unless you ask.

    Do credit unions have fewer fees than banks?

    Generally yes. Studies show credit unions charge:

    • 29% lower overdraft fees on average
    • 60% less likely to charge monthly maintenance fees
    • Lower or zero minimum balance requirements

    Because credit unions are member-owned nonprofits, they return profits to members through lower fees and better rates.

    How often do banking fees change?

    Banks review fee structures annually, with changes typically implemented in January or July. However, regulatory changes can trigger mid-year adjustments. Check your statements quarterly for “Important Changes to Your Account” notices.

    What should I do if charged an unfair fee?

    1. Call the bank first: Ask for a refund (often works for first occurrence)
    2. File a formal complaint: Use bank’s complaint process
    3. Report to CFPB: ConsumerFinance.gov for federal oversight
    4. Report to OCC: HelpWithMyBank.gov for national banks
    5. Switch banks: Vote with your wallet

    The Future of Banking Fees

    Regulatory Changes Coming in 2024-2025

    CFPB Proposed Rules:

    • Overdraft fees capped at $8 (down from $35 average)
    • NSF fees potentially eliminated entirely
    • Stricter disclosure requirements
    • Limits on “junk fees”

    What This Means for You:
    Major banks are already preemptively reducing or eliminating fees to avoid regulation. Good time to negotiate!

    The Rise of Fee-Free Banking

    Market trends show:

    • 67% increase in fee-free checking accounts since 2020
    • Online banks capturing more market share (14% in 2024, up from 8% in 2020)
    • Traditional banks creating fee-free tiers to compete
    • Fintech apps (Chime, SoFi) forcing industry changes

    Bottom Line: Banking is becoming more consumer-friendly, but you still need to be proactive. The best deals don’t automatically apply—you have to seek them out.


    Quick Reference: Banking Fee Cheat Sheet

    Fee Type Average Cost Easiest Avoidance Strategy
    Monthly Maintenance $15/month Switch to online bank
    Overdraft $35/occurrence Opt out + link to savings
    ATM (Out-of-network) $4.73/use Cash back at stores
    Wire Transfer $30/transfer Use Zelle or ACH instead
    Minimum Balance $12/month Choose no-minimum bank
    Paper Statements $3/month Go paperless
    Foreign Transaction 3% of purchase Use fee-free debit/credit card
    Stop Payment $30/request Use electronic payments

    Take Action Today: Your Fee Elimination Checklist

    Immediate Actions (Next 30 Minutes):

    •  Download your last 3 months of bank statements
    •  Calculate total fees paid
    •  Sign up for account balance alerts
    •  Go paperless to eliminate statement fees
    •  Bookmark best bank accounts comparison

    This Week:

    •  Review your bank’s complete fee schedule
    •  Compare with high-yield savings alternatives
    •  Opt out of overdraft coverage
    •  Link savings account as backup
    •  Set up account monitoring app

    This Month:

    •  Call bank to negotiate/waive recurring fees
    •  Open fee-free alternative account if needed
    •  Transfer direct deposit and automatic payments
    •  Close old account if switching
    •  Set up quarterly review reminder

    Quarterly:

    •  Review for any new fees
    •  Check if better accounts available
    •  Verify fee-free status maintained
    •  Adjust alerts and buffers as needed

    Conclusion: Stop Giving Away Your Money

    Banking fees are optional expenses that you can eliminate almost entirely with the right approach. The average American pays over $500 annually in avoidable bank charges—that’s money you could invest, save, or spend on things you actually value.

    The core strategies are simple:

    ✅ Choose the right bank: Fee-free options exist—use them
    ✅ Monitor actively: Check your accounts weekly
    ✅ Set up protections: Alerts, buffers, and automatic systems
    ✅ Negotiate boldly: Banks will waive fees if you ask
    ✅ Vote with your wallet: Switch if your bank won’t cooperate

    Remember: Banks profit when you’re passive. They count on fees slipping by unnoticed, on you not reading the fine print, on inertia keeping you from switching. Break that pattern.

    Take control today. Audit your fees, implement the prevention strategies in this guide, and consider switching to a truly fee-free bank. Your future self—with hundreds of extra dollars in the bank account—will thank you.

    Ready to optimize your entire banking strategy? Check out these related guides:

  • High-Yield Savings Accounts: Maximize Your Interest Earnings

    High-Yield Savings Accounts: Maximize Your Interest Earnings

    Table of Contents

    1. Introduction
    2. What is a High-Yield Savings Account?
    3. Why Traditional Savings Accounts Are Costing You Money
    4. How Much Can You Really Earn?
    5. Top High-Yield Savings Accounts (2025)
    6. How to Choose the Right HYSA
    7. HYSA vs. Other Savings Options
    8. Strategies to Maximize Your Earnings
    9. Understanding APY and How Interest is Calculated
    10. Are High-Yield Savings Accounts Safe?
    11. Tax Implications of High-Yield Savings
    12. When Rates Will Drop (And What to Do)
    13. Common High-Yield Savings Mistakes
    14. Advanced HYSA Tactics
    15. Frequently Asked Questions
    16. Conclusion

    Introduction {#introduction}

    If your savings account earned you less than $50 last year, you’re being robbed—not by a criminal, but by your own bank.

    The harsh reality of traditional savings:

    • Average savings account at big banks: 0.01% APY
    • $10,000 saved for one year: Earns $1
    • That’s not a typo. One dollar.

    Meanwhile, high-yield savings accounts in 2025:

    • Top rates: 5.00-5.50% APY
    • $10,000 saved for one year: Earns $500-550
    • 550x more than traditional savings

    The difference isn’t small—it’s life-changing:

    Your Savings Traditional Bank (0.01%) High-Yield Account (5.25%) Money Left Behind
    $5,000 $0.50/year $262.50/year $262
    $10,000 $1/year $525/year $524
    $25,000 $2.50/year $1,312.50/year $1,310
    $50,000 $5/year $2,625/year $2,620

    Over 10 years, $25,000 in savings:

    • Traditional: Earn $25, potential fees -$120 = -$95
    • High-yield: Earn $13,125+ (with compounding) = +$13,125
    • Difference: $13,220 for doing literally nothing except choosing the right account

    But here’s what most people don’t know:

    High-yield savings accounts aren’t just for rich people or financial experts. They’re:

    • Free to open (most require $0 minimum)
    • FDIC insured (just as safe as traditional banks)
    • Easy to access (transfer to checking in 1-3 days)
    • Available to anyone with a Social Security number

    The question isn’t “Should I get a high-yield savings account?”

    The question is “Why haven’t I done this already?”

    In this comprehensive guide, you’ll discover:

    ✅ The absolute best high-yield savings accounts in 2025 (verified rates, no hype)
    ✅ How to calculate exactly what you’re losing in your current account
    ✅ Step-by-step process to switch (takes 15 minutes)
    ✅ Strategies to earn even more (beyond just choosing the right account)
    ✅ What to watch out for (the fine print that matters)
    ✅ When rates will drop (and how to prepare)

    Whether you have $500 or $500,000 to save, this guide shows you how to make every dollar work harder.

    Your money should be earning you money. Let’s make that happen.


    What is a High-Yield Savings Account? {#what-is}

    Before diving into specific accounts, let’s understand what makes these accounts “high-yield.”
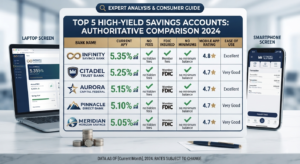
    The Basic Definition

    A high-yield savings account (HYSA) is a savings account that pays significantly higher interest than traditional savings accounts.

    Key characteristics:

    • Higher APY: 4.00-5.50% vs. 0.01% at traditional banks
    • Online banks: Usually offered by online banks (lower overhead = higher rates)
    • FDIC insured: Protected up to $250,000 per depositor (same as traditional)
    • Liquid: Access your money when needed (not locked like CDs)
    • No risk: Principal guaranteed, not subject to market volatility

    How They Work

    The process is simple:

    1. You open account (online application, 10-15 minutes)
    2. You deposit money (transfer from checking, direct deposit, etc.)
    3. Bank pays you interest (calculated daily, paid monthly typically)
    4. Interest compounds (you earn interest on your interest)
    5. You access money when needed (transfer to checking in 1-3 days)

    Example month:

    • January 1: Deposit $10,000
    • Bank calculates interest daily at 5.25% APY
    • Daily interest: $10,000 × (5.25% / 365) = $1.44/day
    • End of month: $43.89 interest earned
    • New balance: $10,043.89
    • February: Earn interest on $10,043.89 (compounding)

    What Makes Them “High-Yield”

    “High-yield” is relative to the market. In 2025:

    • 5.00%+ APY = High-yield (excellent)
    • 4.00-4.99% APY = Competitive
    • 2.00-3.99% APY = Moderate
    • 0.50-1.99% APY = Below average
    • 0.01-0.49% APY = Terrible (traditional banks)

    Historical context:

    • 2020-2021: 0.50% was “high-yield”
    • 2015-2019: 2.00% was excellent
    • 2007-2008: 5.00% was standard
    • 2025: 5.25% is exceptional (best in 15+ years)

    HYSA vs. Regular Savings: What’s Different?

    Feature Traditional Savings High-Yield Savings
    Interest rate 0.01-0.10% 5.00-5.50%
    Where offered Big banks, branches Online banks, some credit unions
    Monthly fees Often $5-15 Usually $0
    Minimum balance Often $500-2,500 Usually $0
    Branches Yes No (online only)
    FDIC insured Yes Yes
    Access to money Instant (branch/ATM) 1-3 days (transfer to checking)
    Annual earnings on $10k $1 $525

    Why Online Banks Can Pay More

    The economics are simple:

    Traditional banks:

    • Thousands of physical branches (rent, utilities, staff)
    • Legacy computer systems (expensive to maintain)
    • Massive overhead costs
    • Solution: Pay depositors almost nothing, charge fees

    Online banks:

    • No physical branches (massive savings)
    • Modern technology (efficient)
    • Minimal overhead
    • Solution: Pass savings to customers via higher rates and no fees

    Example cost structure:

    Big Bank Branch:

    • Rent: $8,000/month
    • Staff (4 people): $15,000/month
    • Utilities: $1,500/month
    • Maintenance: $1,000/month
    • Monthly cost per branch: $25,500
    • Across 4,000 branches = $102 million/month

    Online Bank:

    • No branches: $0
    • Smaller staff (customer service): Fraction of branch costs
    • Pass savings to depositors

    This is why online banks can offer 5.25% while Chase offers 0.01%

    Are They Really “Savings” Accounts?

    Yes, legally and functionally:

    • Federally regulated as savings accounts
    • Subject to Regulation D (historically limited to 6 withdrawals/month, though often unenforced now)
    • FDIC insured like traditional savings
    • Not for daily transactions (no debit card usually)

    Best uses:

    • Emergency fund (3-6 months expenses)
    • Short-term savings goals (vacation, down payment, large purchase)
    • Cash reserves you want accessible but not spending
    • Money earning interest while deciding what to do with it

    Not ideal for:

    • Daily spending (use checking)
    • Long-term investing (10+ years, use investment accounts)
    • Money you access weekly

    Why Traditional Savings Accounts Are Costing You Money {#traditional-cost}

    The opportunity cost of staying at a traditional bank is massive.

    The Real Cost of Convenience

    “But I like having my savings at the same bank as my checking!”

    Let’s calculate what that convenience costs:

    Scenario: $15,000 emergency fund

    Chase Savings (traditional):

    • Rate: 0.01% APY
    • Annual interest: $1.50
    • Monthly fee: $5 (unless $300 minimum daily balance)
    • Annual fees: $60
    • Net cost: -$58.50/year

    Marcus High-Yield Savings (online):

    • Rate: 5.30% APY
    • Annual interest: $795
    • Monthly fee: $0
    • Net benefit: +$795/year

    Difference: $853.50/year for the “convenience” of same-bank savings

    Over 10 years:

    • Chase: Lose $585 (fees exceed minimal interest)
    • Marcus: Earn $9,500+ (with compounding)
    • Cost of convenience: $10,085

    That’s not convenience. That’s expensive.

    The Inflation Reality

    Your money in traditional savings is losing value:

    With 3% inflation:

    • $10,000 today
    • 0.01% interest earned: $1
    • Inflation loss: -$300
    • Real loss: -$299 (2.99% purchasing power gone)

    With high-yield savings:

    • $10,000 today
    • 5.25% interest earned: $525
    • Inflation loss: -$300
    • Real gain: +$225 (2.25% purchasing power increase)

    Traditional savings = guaranteed loss to inflation
    High-yield savings = beat inflation by 2%+

    What You Could Have Earned

    Painful hindsight calculator:

    If you’ve had $10,000 sitting in 0.01% savings for 5 years:

    • What you earned: $5
    • What you could have earned (average 3% over 5 years): $1,593
    • Money left on table: $1,588

    If $25,000 for 10 years:

    • Actual earnings at 0.01%: $25
    • Potential earnings at 4% average: $12,189
    • Money left on table: $12,164

    Don’t let past mistakes compound. Switch now.

    The Psychological Cost

    Beyond dollars, traditional savings create:

    False security:

    • “I’m saving money” (but it’s losing value)
    • “I’m being responsible” (but missing opportunities)

    Learned helplessness:

    • “All banks pay nothing”
    • “There’s no point in comparing”
    • “It doesn’t matter where I save”

    Financial inertia:

    • Staying put despite better options
    • Loyalty to banks that don’t value you

    Breaking free from traditional banking psychology = first step to wealth building


    How Much Can You Really Earn? {#earnings}

    Let’s run the numbers with real scenarios.

    Simple Interest Calculator

    Formula: Principal × APY = Annual Interest

    At 5.25% APY:

    Starting Balance Daily Interest Monthly Interest Annual Interest
    $1,000 $0.14 $4.27 $52.50
    $5,000 $0.72 $21.88 $262.50
    $10,000 $1.44 $43.75 $525
    $15,000 $2.16 $65.63 $787.50
    $25,000 $3.60 $109.38 $1,312.50
    $50,000 $7.19 $218.75 $2,625
    $100,000 $14.38 $437.50 $5,250

    That daily interest column is key: Your money is working for you every single day.

    Compound Interest Reality

    Compound interest = earning interest on your interest

    Example: $10,000 at 5.25% APY for 10 years (no additional deposits)

    Year-by-year growth:

    • Year 1: $10,525
    • Year 2: $11,078
    • Year 3: $11,659
    • Year 4: $12,271
    • Year 5: $12,915
    • Year 6: $13,593
    • Year 7: $14,307
    • Year 8: $15,058
    • Year 9: $15,849
    • Year 10: $16,681

    Total earned: $6,681 (67% return on original $10,000)

    Compare to 0.01% traditional savings:

    • Year 10: $10,010
    • Total earned: $10
    • Difference: $6,671

    Adding Regular Contributions

    Most people save monthly. This amplifies returns.

    Scenario: Start with $5,000, add $300/month

    At 5.25% APY for 5 years:

    • Total contributed: $5,000 + ($300 × 60 months) = $23,000
    • Account balance after 5 years: $25,850
    • Interest earned: $2,850
    • Return on contributions: 12.4%

    At 0.01% traditional savings:

    • Total contributed: $23,000
    • Account balance: $23,006
    • Interest earned: $6
    • You literally earned enough for one coffee

    The $100/Month Challenge

    What if you saved just $100/month?

    In high-yield savings (5.25% APY):

    • Year 1: $1,233 (contributed $1,200)
    • Year 5: $6,776 (contributed $6,000)
    • Year 10: $15,582 (contributed $12,000)

    Interest earned over 10 years: $3,582

    In traditional savings (0.01%):

    • Year 10: $12,006
    • Interest earned: $6

    Difference: $3,576 for doing the exact same thing (saving $100/month) in a different account

    Real-Life Earning Examples

    Example 1: Emergency Fund Builder

    • Sarah, age 28
    • Goal: 6-month emergency fund ($18,000)
    • Starting point: $3,000
    • Monthly savings: $500

    Timeline in HYSA (5.25% APY):

    • Month 15: Reaches $10,000
    • Month 30: Reaches $18,000 goal
    • Interest earned during building: $1,247
    • Reached goal 2 months earlier than if earning 0%

    Example 2: Down Payment Saver

    • Michael and Jessica, ages 31 and 29
    • Goal: $60,000 house down payment
    • Starting point: $15,000
    • Monthly savings: $1,500

    At 5.25% APY:

    • Month 30: $62,850 (goal reached!)
    • Interest earned: $2,850
    • Earned extra $2,850 while saving for house

    At 0.01% traditional:

    • Month 30: $60,015
    • Interest earned: $15
    • Essentially $0 interest

    Example 3: Retiree Safety Net

    • Robert, age 68
    • Keeps $50,000 cash for emergencies/opportunities
    • Not investing (wants guaranteed safety)

    Annual income from HYSA:

    • $50,000 × 5.25% = $2,625/year
    • Monthly: $218.75
    • Covers his Medicare Part B premium ($174.70/month in 2024)

    In traditional savings:

    • Annual income: $5
    • Doesn’t even cover a single month’s Netflix

    Calculator: Your Potential Earnings

    Use this formula:

    Annual interest = Balance × (APY / 100)

    Your numbers:

    1. Current savings balance: $__________
    2. Current APY: ______%
    3. Potential HYSA APY: 5.25%

    Current annual earnings:
    $__________ × (% / 100) = $______

    Potential HYSA earnings:
    $__________ × (5.25 / 100) = $__________

    Annual difference: $__________

    10-year difference (conservative, no compounding):
    $__________ × 10 = $__________

    That’s real money you’re leaving on the table.


    Top High-Yield Savings Accounts (2025) {#top-accounts}

    Every account listed is FDIC insured and currently accepting new customers. Rates verified December 2024.


    🏆 #1: Marcus by Goldman Sachs High Yield Savings

    APY: 5.30%
    Monthly Fee: $0
    Minimum Balance: $0
    Minimum Opening Deposit: $0

    Why it’s #1:

    • Highest consistent rate (Marcus doesn’t play intro rate games)
    • Zero fees (no monthly fee, no transfer fees, no minimum balance fees)
    • No minimums (open with $1 if you want)
    • Reliable (Goldman Sachs backing, established online bank)
    • Excellent app (4.8/5 stars, clean interface)

    Features:

    • Daily compounding interest
    • No transaction fees
    • Link up to 3 external accounts
    • Transfers typically 1-2 business days
    • Auto-save tools
    • Mobile app and online access
    • FDIC insured up to $250,000

    Withdrawals:

    • 6 per month (federal regulation, though often unenforced)
    • Unlimited transfers out (may take 1-3 days)
    • No fees for withdrawals

    Customer Service:

    • Phone: 8am-10pm ET, 7 days/week
    • Secure messaging
    • Email support

    Best for:

    • Maximum interest earnings
    • Straightforward high-yield savings
    • People who value consistency (rate doesn’t yo-yo)
    • Marcus credit card holders (familiar with brand)

    Potential drawbacks:

    • Online only (no branches)
    • No ATM card (must transfer to checking first)
    • Not instant access (1-2 day transfers)

    Bottom line: Marcus offers the best combination of top-tier rate, zero fees, zero minimums, and reliability. Hard to beat.


    🥈 #2: American Express Personal Savings

    APY: 5.30%
    Monthly Fee: $0
    Minimum Balance: $0
    Minimum Opening Deposit: $0

    Ties with Marcus for rate, slightly different features

    Why it’s #2 (tied for #1 really):

    • Same 5.30% APY as Marcus
    • Zero fees, zero minimums
    • Amex brand trust (well-known, established)
    • Faster transfers (often same-day to next-day)
    • Excellent customer service (24/7 phone support)

    Features:

    • Daily compounding
    • Link up to 4 external accounts
    • Faster transfers than most (ACH often next day)
    • Online and mobile app
    • No fees of any kind
    • FDIC insured up to $250,000

    Customer Service:

    • 24/7 phone support
    • Live chat
    • Email
    • Generally excellent reviews

    Best for:

    • Amex credit card holders (familiar ecosystem)
    • People who prioritize customer service
    • Those who want fastest transfers (among high-yield accounts)
    • Anyone wanting top rate with trusted brand

    Potential drawbacks:

    • Online only
    • Can only link 4 external accounts (vs. unlimited at some banks)
    • No ATM access

    Bottom line: Choosing between Marcus and Amex is personal preference. Identical rates, both excellent. Amex wins on customer service and transfer speed; Marcus wins on brand focus (dedicated to savings).


    🥉 #3: Ally Bank Online Savings Account

    APY: 5.25%
    Monthly Fee: $0
    Minimum Balance: $0
    Minimum Opening Deposit: $0

    Why it’s #3:

    • Competitive 5.25% APY (just 0.05% below top)
    • Best features and tools (savings buckets, boosters, surprise savings)
    • Superior user experience (consistently top-rated app)
    • Full banking relationship (checking + savings integration)

    Unique Features:

    Savings Buckets:

    • Organize savings into categories within account
    • “Emergency Fund” bucket: $10,000
    • “Vacation” bucket: $3,000
    • “New Car” bucket: $8,000
    • All earn same 5.25% rate

    Savings Boosters:

    • Recurring transfers (automatic)
    • Percentage of paycheck
    • Round-ups from spending
    • Surprise savings (AI suggests amounts based on spending)

    Other Features:

    • Daily compounding
    • No fees
    • Link unlimited external accounts
    • Transfers 1-3 business days
    • Instant transfers to Ally checking
    • FDIC insured

    Customer Service:

    • 24/7 phone support
    • Chat support
    • Email
    • Excellent reputation

    Best for:

    • People wanting organization (buckets brilliant for multiple goals)
    • Ally checking account holders (instant transfers between accounts)
    • Those who value automation (boosters)
    • Anyone who loves excellent apps and UX

    Potential drawbacks:

    • Rate 0.05% lower than Marcus/Amex ($5 less per $10,000 per year)
    • Online only

    Bottom line: If you value tools and organization over an extra $5/year per $10,000, Ally is superior to Marcus/Amex. If you just want highest rate and simplicity, go Marcus/Amex.


    #4: CIT Bank Platinum Savings

    APY: 5.05%
    Monthly Fee: $0
    Minimum Balance: $5,000 OR $100+ monthly deposits with $100 minimum

    Why it’s on the list:

    • Competitive 5.05% APY
    • Lower rate but flexible requirements (good for regular savers)
    • Savings Builder tools

    Two ways to qualify for 5.05%:

    Option A: Maintain $5,000+ balance
    Option B: Make $100+ deposits per month AND maintain $100+ balance

    If below minimums: 1.00% APY (significantly lower)

    Features:

    • Daily compounding
    • No monthly fee (if minimums met)
    • Online and mobile banking
    • External account linking
    • FDIC insured

    Best for:

    • People with $5,000+ to save
    • Regular savers depositing $100+/month
    • Those comfortable with balance requirements

    Potential drawbacks:

    • Requires $5,000 OR $100 monthly deposits
    • Rate drops dramatically if don’t meet minimums
    • Not as high as Marcus/Amex/Ally
    • Less well-known brand

    Bottom line: Good option if you meet minimums easily. But for most people, Marcus/Amex/Ally better (no minimums, higher rates).


    #5: Discover Online Savings Account

    APY: 5.25%
    Monthly Fee: $0
    Minimum Balance: $0
    Minimum Opening Deposit: $0

    Why it’s on the list:

    • Competitive 5.25% rate
    • Trusted brand (Discover well-known for credit cards)
    • Can open multiple accounts (great for organizing goals)
    • 24/7 customer service

    Features:

    • Daily compounding
    • No fees or minimums
    • Link external accounts
    • Transfers 1-3 business days
    • Can have multiple Discover savings accounts (organize by goal)
    • Mobile app and online banking
    • FDIC insured

    Customer Service:

    • 24/7 phone
    • Chat
    • U.S.-based support
    • Generally excellent

    Best for:

    • Discover credit card holders (familiar with brand)
    • People wanting multiple savings accounts at same bank
    • Those who value 24/7 customer service
    • Anyone wanting top rate with well-known brand

    Potential drawbacks:

    • Online only
    • Features less robust than Ally (no buckets within account)
    • Discover known more for cards than banking (some hesitation)

    Bottom line: Solid choice, especially if you already have Discover card. But doesn’t differentiate significantly from Marcus/Amex/Ally.


    Honorable Mention: LendingClub High-Yield Savings

    APY: 5.30%
    Monthly Fee: $0
    Minimum Balance: $100 minimum opening deposit, then $0

    Why it’s honorable mention:

    • Ties top rate (5.30%)
    • Zero monthly fees
    • Strong app

    Why not top 5:

    • Requires $100 opening deposit (vs. $0 at others)
    • Less established banking brand (known for lending)
    • Fewer years of track record as bank

    Good alternative if top banks aren’t accepting new customers in your area


    Comparison Summary Table

    Bank APY Monthly Fee Min Balance Min Opening Best Feature
    Marcus 5.30% $0 $0 $0 Highest rate + consistency
    Amex 5.30% $0 $0 $0 Fast transfers + service
    Ally 5.25% $0 $0 $0 Buckets + automation
    CIT 5.05% $0 $5,000* $0 Flexible requirements
    Discover 5.25% $0 $0 $0 Multiple accounts

    *Or $100 monthly deposits + $100 minimum


    Which Should You Choose?

    Decision tree:

    Want absolute highest rate + simplicity?
    → Marcus or Amex (5.30%, identical rates, choose based on preference)

    Want best tools and organization?
    → Ally (5.25%, buckets feature worth the 0.05% difference for many)

    Have $5,000+ to maintain OR deposit $100+/month?
    → CIT works, but Marcus/Amex/Ally still better (higher rates, no requirements)

    Want trusted brand + can open multiple accounts?
    → Discover (5.25%, well-known brand, multiple account capability)

    Can’t decide?
    → Start with Marcus (straightforward, highest rate, can’t go wrong)

    Want to diversify?
    → Split between Marcus and Ally (FDIC coverage at two banks, get both rate and features)


    [Internal Link: See full banking comparison in “Best Bank Accounts for 2025: Checking, Savings & Money Market”]


    How to Choose the Right HYSA {#choose}

    Beyond just rates, consider these factors.

    Your Savings Goals

    Emergency Fund (3-6 months expenses):

    • Priority: Accessibility + safety + decent rate
    • Best choice: Any top HYSA (Marcus, Amex, Ally all excellent)
    • Don’t: Lock in CD (need liquidity)
    • Amount: $15,000-$35,000 typical

    Short-term savings (1-3 years):

    • Vacation, wedding, car down payment, house fund
    • Priority: High rate + safety
    • Best choice: HYSA or CD (if timeline definite)
    • Consider: Ally (buckets organize multiple goals)

    Medium-term (3-5 years):

    • Larger goals (house down payment, career transition)
    • Priority: Beat inflation + safety
    • Best choice: HYSA or conservative investments
    • Consider: Mix of HYSA + low-risk investments

    Long-term (5+ years):

    • Don’t use HYSA (opportunity cost too high)
    • Use: Investment accounts (stocks, bonds, index funds)
    • Why: Historical stock returns 10%/year vs. 5% HYSA

    Your Balance

    Under $5,000:

    • Any no-minimum HYSA works
    • Focus on highest rate
    • Choose: Marcus or Amex (5.30%)

    $5,000-$25,000:

    • Most HYSAs perfect for this range
    • Consider features (Ally buckets useful)
    • Choose: Based on preference (all top accounts excellent)

    $25,000-$100,000:

    • Still within FDIC limits at one bank
    • High rate critical (difference adds up)
    • Calculate: 5.30% vs. 5.25% on $50,000 = $25/year difference
    • Choose: Marcus or Amex for max rate

    $100,000-$250,000:

    • Approaching FDIC limit at one bank
    • Consider: Multiple accounts for FDIC coverage
    • Strategy: $125,000 at Marcus + $125,000 at Amex = $500,000 FDIC coverage

    Over $250,000:

    • Must use multiple banks (FDIC limit)
    • Strategy:
      • $250,000 at Marcus
      • $250,000 at Amex
      • $250,000 at Ally
      • Each separately FDIC insured
    • Alternative: CDARS/IntraFi (automatic multi-bank spreading)

    Your Tech Comfort Level

    Very comfortable with online/apps:

    • Any HYSA works
    • Prioritize rate and features
    • Choose: Highest rate (Marcus/Amex) or best features (Ally)

    Moderately comfortable:

    • Still fine with HYSA (they’re designed to be easy)
    • Prioritize simplicity
    • Choose: Marcus (straightforward) or Discover (familiar brand)

    Prefer in-person banking:

    • Challenge: HYSAs are online-only
    • Solution: Hybrid approach:
      • Keep checking at local bank (for branch access)
      • Put savings in HYSA (transfer to checking when needed)
    • Alternative: Local credit union (sometimes 4-5% rates with relationship)

    Your Access Needs

    Rarely need to touch savings:

    • Perfect for HYSA
    • Choose: Highest rate (Marcus/Amex)

    Occasional access (few times/year):

    • HYSA still perfect (1-3 day transfer fine)
    • Choose: Amex (faster transfers) or any top account

    Frequent access (monthly):

    • Reconsider: Is this really savings?
    • Maybe: Money market account better (check writing + ATM)
    • Or: Keep more in checking, less in savings

    Emergency access needed:

    • HYSA takes 1-3 days (not instant)
    • Solution: Keep 1 month expenses in checking (instant access)
    • Rest in HYSA: 1-3 day transfer acceptable for emergencies

    Your Organization Style

    Simple (one savings account total):

    • Choose: Marcus or Amex (straightforward, high rate)

    Organizer (separate accounts for each goal):

    • Choose: Ally (buckets within account) OR
    • Alternative: Discover (can open multiple accounts)

    Automator (set it and forget it):

    • Choose: Ally (boosters, automatic savings tools)

    HYSA vs. Other Savings Options {#comparison}

    How does HYSA stack up against alternatives?

    HYSA vs. Certificate of Deposit (CD)

    Certificates of Deposit: Lock money for set term (6 months to 5 years) for guaranteed rate.

    CD Advantages:

    • Sometimes higher rates (6-month CD: 5.50% vs. 5.25% HYSA)
    • Rate guaranteed (won’t drop if Fed lowers rates)
    • Forced discipline (can’t touch without penalty)

    HYSA Advantages:

    • Complete liquidity (access anytime)
    • No early withdrawal penalty
    • No commitment
    • Can add money anytime

    When to choose CD:

    • You know you won’t need money for specific period
    • Rates are higher than HYSA (not always the case)
    • You want guaranteed rate regardless of Fed changes

    When to choose HYSA:

    • You want flexibility
    • You might need money
    • CD rates aren’t significantly higher (0.25%+ difference worth it, 0.05% not)
    • You’re building savings (can’t add to CD once opened)

    Recommendation: Emergency fund = HYSA (need liquidity). Specific goal with timeline = consider CD.


    HYSA vs. Money Market Account

    Money Market Accounts: Hybrid of checking and savings (earns interest, but has checks/ATM card).

    Money Market Advantages:

    • Check writing (6 per month typically)
    • ATM card access
    • Same or similar rates to HYSA (5.00-5.25%)

    HYSA Advantages:

    • Sometimes slightly higher rates
    • Simpler (don’t need checks/ATM for pure savings)

    When to choose Money Market:

    • You want check writing on savings
    • You want ATM access to savings
    • You keep large balance you might need to access directly

    When to choose HYSA:

    • Pure savings (don’t need checks)
    • Slightly higher rate (0.05-0.25% difference)
    • Simplicity

    Recommendation: For most, HYSA is better. Only get money market if specifically need check/ATM features.


    HYSA vs. High-Yield Checking

    Some checking accounts now pay interest (3-5% on limited balances).

    High-Yield Checking Example: Upgrade Premier Checking

    • 5.07% APY on balances up to $10,000
    • Then 1.07% on amounts above
    • Requires direct deposit

    Comparison:

    Feature HYSA High-Yield Checking
    Rate on all balances 5.25% 5.07% up to $10k, then 1.07%
    Balance limits None Usually $10-25k
    Requirements None Direct deposit often required
    Debit card No Yes
    Bill pay Limited Yes
    Daily transactions No Yes

    Strategy: Use BOTH

    • High-yield checking: Keep $5,000-10,000 (daily spending + earn 5%)
    • HYSA: Keep rest of savings (emergency fund, goals)

    This maximizes earnings on both checking and savings


    HYSA vs. Traditional Savings

    We’ve covered this, but summary:

    Feature Traditional Savings HYSA
    Rate 0.01-0.10% 5.00-5.50%
    Earnings on $10k/year $1-10 $500-550
    Fees Often $5-15/month $0
    Minimums Often $500-2,500 $0
    Branches Yes No

    There is literally no reason to keep money in traditional savings unless:

    • You need physical branch access for deposits (keep checking there, not savings)
    • You’re over 80 and refuse to use online banking (even then, have family help you switch)

    For 99% of people: Traditional savings is lighting money on fire


    HYSA vs. Brokerage Account (Investing)

    Different purposes, different timelines:

    HYSA:

    • Purpose: Safety, liquidity, guaranteed return
    • Timeline: 0-5 years
    • Return: 5.25% guaranteed
    • Risk: None (FDIC insured)
    • Best for: Emergency fund, short-term goals

    Brokerage (Stock Market):

    • Purpose: Growth, wealth building
    • Timeline: 5+ years (ideally 10+)
    • Return: 10%/year average (historical), but varies
    • Risk: Can lose money (2022: down 18%, 2008: down 37%)
    • Best for: Retirement, long-term goals

    You need BOTH:

    • HYSA for short-term and emergencies
    • Investments for long-term and growth

    Don’t make this mistake: Keeping everything in HYSA long-term (10+ years)

    • 5% guaranteed sounds safe
    • But missing 10% average stock returns
    • Over 30 years: Huge opportunity cost

    Don’t make opposite mistake: Investing emergency fund

    • Stocks can drop 30-50% in recession
    • Exactly when you might lose job (need emergency fund)
    • Emergency fund must be safe (HYSA)

    Strategies to Maximize Your Earnings {#strategies}

    Beyond just opening an account, tactics to earn even more.

    Strategy #1: The Direct Deposit Switch

    Move your direct deposit to high-yield savings account:

    Traditional approach:

    • Paycheck → Checking (0% interest)
    • Manually transfer to savings (if remember)
    • Most money sits in checking earning nothing

    Optimized approach:

    • Paycheck → HYSA (5.25% interest)
    • Automatic transfer to checking (just enough for bills)
    • Maximum money earns maximum interest

    Example:

    • Monthly income: $5,000
    • Monthly expenses: $3,500

    Traditional:

    • $5,000 sits in checking earning 0%
    • Manual transfer $1,500 to savings (if disciplined)

    Optimized:

    • $5,000 direct deposited to HYSA (earning 5.25%)
    • Auto-transfer $3,500 to checking day after deposit
    • $1,500 stays in HYSA

    Benefit: Your money earns interest immediately (day 1 of pay period vs. later when you transfer)

    Micro-optimization: Over year, earns extra $100-200 on float


    Strategy #2: The Savings Automation Ladder

    Set up automated transfers right after payday:

    Day 1 (Payday):

    • Direct deposit hits

    Day 2:

    • Auto-transfer to checking (bills amount)

    Day 3:

    • Auto-transfer to different savings goals:
      • $200 → Emergency fund HYSA
      • $150 → Vacation fund HYSA
      • $300 → House down payment HYSA
      • $100 → Car replacement fund HYSA

    Benefit: “Pay yourself first” before you can spend

    Psychology: Money you don’t see, you don’t spend


    Strategy #3: The Rate Stacking Method

    Use multiple accounts for maximum earnings:

    Checking: Upgrade Premier (5.07% on first $10k)

    • Keep: $10,000
    • Earn: $507/year

    Savings 1: Marcus HYSA (5.30%)

    • Keep: $15,000 (emergency fund)
    • Earn: $795/year

    Savings 2: Ally HYSA (5.25%)

    • Keep: $10,000 (short-term goals, organized in buckets)
    • Earn: $525/year

    Total holdings: $35,000
    Total annual interest: $1,827
    Effective APY: 5.22% (across all accounts)

    Bonus: Multiple FDIC coverage ($250k at each bank)


    Strategy #4: The Round-Up Accelerator

    Many banks offer “round-up” features:

    How it works:

    • Purchase coffee: $4.75
    • Rounded to: $5.00
    • Difference: $0.25 → savings

    Daily example:

    • 5 transactions rounded up
    • Average round-up: $0.40/transaction
    • Daily savings: $2.00
    • Monthly: $60
    • Annually: $720

    Plus interest: $720 × 5.25% = $37.80 first year

    Banks offering this:

    • Ally (Savings Booster)
    • SoFi (Spare Change)
    • Many others

    Set it and forget it: Painless savings that compounds


    Strategy #5: The Promotional Rate Cycle

    Some banks offer promotional rates:

    • Example: “6.00% for first 3 months, then 5.25%”

    Strategy:

    • Open account for promo rate
    • Transfer large sum ($25,000)
    • Earn 6% for 3 months
    • After promo ends, either:
      • Keep (if base rate competitive)
      • Or transfer to highest permanent rate

    Example earnings:

    • $25,000 at 6% for 3 months: $375
    • Then at 5.25% for 9 months: $984
    • Total year 1: $1,359
    • vs. $1,312 at flat 5.25% all year
    • Extra: $47 for 20 minutes of work (opening account)

    Caution: Only worth it for large balances and if base rate competitive post-promo


    Strategy #6: The Spouse/Partner Maximization

    If you’re married or partnered:

    Individual accounts at each bank:

    • You: $250,000 at Marcus
    • Partner: $250,000 at Marcus
    • Total FDIC coverage: $500,000 at one bank

    Plus joint account:

    • Joint: $250,000 at Marcus
    • Additional coverage: $250,000
    • Total at Marcus: $750,000 FDIC covered

    Then repeat at other banks:

    • Amex: $750,000 covered
    • Ally: $750,000 covered

    For high net worth couples, this maximizes FDIC coverage while keeping high rates


    Strategy #7: The Tax-Advantaged Timing

    Interest is taxable income.

    If you’re strategic:

    • Open account early in year (January)
    • Build balance throughout year
    • Interest earned across full year
    • Pay taxes next April

    vs.

    • Open account late in year (November)
    • Interest earned only 2 months
    • But didn’t have money working for you all year

    Always better to start earlier (even though taxes), because:

    • $10,000 earning 5.25% for 12 months = $525 interest
    • Tax on $525 (25% bracket) = -$131
    • Net: +$394

    vs.

    • $10,000 earning 0.01% for 12 months = $1 interest
    • Tax on $1 = $0.25
    • Net: +$0.75

    Don’t let tax tail wag the dog. Earn interest, pay tax, still way ahead.


    Strategy #8: The Emergency Fund Tiering

    Not all emergency fund needs same-day access:

    Tier 1: Immediate ($1,000-2,000)

    • Keep in checking account
    • 0% interest, but instant access
    • For true emergencies (car breaks down, need tow)

    Tier 2: Quick Access ($5,000-10,000)

    • HYSA with fast transfers (Amex, 1-day transfer)
    • 5.30% interest
    • Transfer to checking if needed (1 day)

    Tier 3: Full Emergency Fund ($15,000-25,000)

    • HYSA at highest rate (Marcus, 5.30%)
    • 1-3 day transfers fine (real emergencies can wait)

    Benefit:

    • Maximum money earning maximum interest
    • Still have instant access to some funds
    • Majority earning 5.30% (vs. sitting in 0% checking)

    Understanding APY and How Interest is Calculated {#apy}

    Knowledge is power when comparing accounts.

    APY vs. APR (Don’t Confuse These)

    APY (Annual Percentage Yield):

    • Used for savings/deposits
    • Includes compound interest
    • What you EARN on savings
    • Higher is better

    APR (Annual Percentage Rate):

    • Used for loans/credit cards
    • Simple interest rate
    • What you PAY on debt
    • Lower is better

    For savings accounts, always compare APY (not interest rate)

    How Interest is Calculated

    Daily compound interest (most HYSAs):

    Formula:
    Daily Interest = Balance × (APY / 365)

    Example: $10,000 at 5.25% APY

    Day 1:

    • Interest: $10,000 × (0.0525 / 365) = $1.44
    • New balance: $10,001.44

    Day 2:

    • Interest: $10,001.44 × (0.0525 / 365) = $1.44
    • New balance: $10,002.88

    Continues daily…

    Month 1 (30 days):

    • Interest earned: $43.29
    • Balance: $10,043.29

    Month 2 (31 days):

    • Interest earned on higher balance: $44.85
    • Balance: $10,088.14

    This is compound interest: Earning interest on your interest

    The Power of Compounding

    $10,000 at 5.25% APY:

    Without compounding (simple interest):

    • Year 1: $525 interest
    • Year 5: $2,625 interest
    • Year 10: $5,250 interest

    With compounding (actual):

    • Year 1: $537 interest
    • Year 5: $2,915 interest
    • Year 10: $6,681 interest

    Difference over 10 years: $1,431 (27% more than simple interest)

    Why compounding matters:

    • Month 1: Earn interest on $10,000
    • Month 2: Earn interest on $10,043
    • Month 3: Earn interest on $10,088
    • Small differences compound over time

    Rate vs. APY Comparison

    If bank advertises “5.20% rate, compounded daily”:

    Actual APY = (1 + 0.0520/365)^365 – 1 = 5.34% APY

    Always use APY for comparisons (accounts for compounding frequency)

    How Banks Display Rates

    What you’ll see:

    • “5.25% APY*”
    • *Annual Percentage Yield

    Fine print usually says:

    • “Rate accurate as of [date]”
    • “Rates subject to change without notice”
    • “Fees could reduce earnings”

    This is normal. Variable rates fluctuate.

    Monthly Interest Payments

    Most HYSAs pay interest monthly:

    Timeline:

    • Day 1-31: Interest calculated daily
    • Last day of month: Interest credited to account
    • Appears as deposit on statement

    Example statement:

    • March 1 balance: $10,000
    • March 31 interest payment: +$43.75
    • April 1 balance: $10,043.75

    Note: Some banks pay quarterly (every 3 months). Monthly is better (compounds faster).


    Are High-Yield Savings Accounts Safe? {#safety}

    Addressing common concerns about safety.

    FDIC Insurance Explained

    Federal Deposit Insurance Corporation:

    • Government agency (created 1933)
    • Insures deposits at member banks
    • Covers up to $250,000 per depositor, per bank
    • You don’t pay for this (banks pay premiums)

    What’s covered:

    • Savings accounts ✅
    • Checking accounts ✅
    • Certificates of deposit ✅
    • Money market accounts ✅

    What’s NOT covered:

    • Stocks ❌
    • Bonds ❌
    • Mutual funds ❌
    • Cryptocurrency ❌
    • Investments ❌

    HYSA is FDIC insured = your money is safe up to $250,000

    What If Bank Fails?

    Recent example: Silicon Valley Bank (March 2023)

    What happened:

    1. Bank declared failed by regulators
    2. FDIC took over immediately
    3. Depositors with under $250,000: Fully protected, zero loss
    4. Access restored within days
    5. FDIC found buyer bank or paid depositors directly

    Historical data:

    • Since FDIC created (1933): Zero insured depositors have lost money
    • Banks fail periodically
    • FDIC process works

    Your action if bank fails: Nothing

    • FDIC contacts you
    • Your money is safe
    • Transferred to new bank or check mailed

    Online Banks: Extra Safety Concerns?

    “But there’s no physical building. Is my money real?”

    Yes. Online banks are just as safe:

    Same regulations:

    • Subject to same federal banking laws
    • Same FDIC insurance
    • Same oversight
    • Same capital requirements

    Sometimes safer:

    • Better fraud detection (advanced tech)
    • Stronger encryption
    • Two-factor authentication
    • Biometric security

    The building doesn’t protect your money. FDIC does.

    Verification Process

    Before opening any HYSA, verify FDIC insurance:

    1. Check bank website (should prominently display “Member FDIC”)
    2. Use FDIC BankFind tool: FDIC.gov/resources/deposit-insurance
    3. Look for FDIC certificate number

    All accounts recommended in this guide are FDIC verified

    Security Best Practices

    Protect your account:

    Strong password:

    • Unique (not used elsewhere)
    • 12+ characters
    • Mix of letters, numbers, symbols
    • Use password manager

    Two-factor authentication:

    • Enable for all accounts
    • SMS or authenticator app
    • Extra security layer

    Monitor regularly:

    • Check account weekly
    • Set up transaction alerts
    • Review statements monthly
    • Report suspicious activity immediately

    Never share:

    • Password
    • Social Security number (after account opened)
    • Account numbers via email/phone

    Phishing awareness:

    • Banks never ask for password via email
    • Don’t click links in unexpected emails
    • Go directly to website (don’t use email links)

    Credit Union Alternative: NCUA

    Credit unions use NCUA instead of FDIC:

    • National Credit Union Administration
    • Same $250,000 coverage
    • Equally safe
    • Same government backing

    NCUA = credit union equivalent of FDIC


    Tax Implications of High-Yield Savings {#taxes}

    Interest is taxable income. Here’s what you need to know.

    How Savings Interest is Taxed

    Interest earned = ordinary income

    • Taxed at your regular income tax rate
    • Added to W-2 income, freelance income, etc.
    • Same rate as your salary

    Not capital gains (different from investment taxation)

    Tax Brackets and Impact

    2024 Federal tax brackets (single filers):

    Taxable Income Tax Rate
    $0 – $11,600 10%
    $11,601 – $47,150 12%
    $47,151 – $100,525 22%
    $100,526 – $191,950 24%
    $191,951 – $243,725 32%

    Example: You earn $60,000 salary + $525 savings interest

    Your $525 interest is taxed at 22% (your marginal rate):

    • Tax on interest: $525 × 0.22 = $115.50
    • You keep: $525 – $115.50 = $409.50

    Still way better than earning $1 at 0.01% (keeping $0.75 after tax)

    Form 1099-INT

    Banks report interest to IRS:

    If you earn $10+ in interest, bank sends:

    • Form 1099-INT to you (by January 31)
    • Copy to IRS

    Your responsibility:

    • Report on tax return (1040, line 2b)
    • Pay tax owed
    • Happens automatically if using tax software

    Example 1099-INT:

    • Marcus by Goldman Sachs
    • Interest paid in 2024: $525.00
    • You report this $525 on your tax return

    Estimated Taxes

    If you earn significant interest:

    IRS requires quarterly estimated tax payments if:

    • You’ll owe $1,000+ in taxes
    • Interest + other income not subject to withholding

    Quarterly deadlines:

    • April 15
    • June 15
    • September 15
    • January 15

    Calculation:

    • Interest earned: $2,625 (on $50,000 at 5.25%)
    • Tax rate: 24%
    • Annual tax: $630
    • Quarterly payment: $157.50

    Most people don’t need to worry (unless very high balances or other non-W-2 income)

    State Taxes

    Most states also tax interest income:

    • Same rate as state income tax
    • Added to your state return
    • Varies by state (0% in TX, FL, WA to 13%+ in CA)

    Example: California resident

    • Interest earned: $525
    • Federal tax (22%): -$115.50
    • State tax (9.3%): -$48.83
    • Net after taxes: $360.67

    Still earning $360 vs. $0.75 in traditional savings

    Tax Strategies

    1. Maximize retirement contributions

    • Reduces taxable income
    • Lowers tax rate on interest
    • Example: Contribute $6,500 to IRA → may drop from 22% to 12% bracket

    2. Keep savings in Roth IRA (if eligible)

    • Roth IRA savings accounts exist
    • Interest grows tax-free
    • Contributions accessible (but not recommended for emergency fund)

    3. Don’t let tax tail wag the dog

    • Earning 5.25% and paying 24% tax = 4.0% net
    • Still better than 0.01% and paying 24% tax = 0.008% net
    • Always better to earn more, even after taxes

    Tax Reporting Checklist

    January:

    •  Receive 1099-INT from each bank (by Jan 31)
    •  Verify amounts match your records

    Tax Filing:

    •  Enter 1099-INT information on tax return
    •  Report on Schedule B if over $1,500 total interest
    •  Pay any tax owed

    Year-round:

    •  Track interest earned (estimate for planning)
    •  Adjust W-4 if needed (increase withholding to cover interest tax)
    •  Make quarterly estimated payments if required

    When Rates Will Drop (And What to Do) {#rate-changes}

    Understanding rate cycles helps you plan.

    Why Rates are High Now (2025)

    Federal Reserve policy:

    • 2022-2023: Fed raised rates aggressively (combat inflation)
    • Fed funds rate: 4.25-4.50%
    • High Fed rate → high savings rates

    Historical context:

    • 2020-2021: Fed rate 0-0.25% (pandemic stimulus)
    • Savings rates: 0.50-1.00%
    • 2007-2008: Fed rate 5.25%
    • Savings rates: 4.50-5.00% (similar to now)

    Current 5%+ rates are historical anomaly (but awesome while they last)

    When Rates Will Drop

    Likely scenario for 2025-2026:

    Fed will lower rates when:

    • Inflation returns to 2% target
    • Economy slows
    • Unemployment rises
    • Recession concerns

    Expected timeline:

    • 2025: Possible 2-3 rate cuts (0.75% total)
    • 2026: Additional cuts if economy slows
    • By 2027: Fed rate possibly 2.5-3.5%

    Impact on savings rates:

    • Each 0.25% Fed cut → ~0.25% drop in HYSA rates
    • 3 cuts (0.75%) → HYSA rates drop to 4.50%
    • Eventually: Settle around 3.00-3.50% (still good!)

    This is normal cycle. Rates won’t stay 5%+ forever.

    What Happens to Your Rate

    Variable rate accounts (most HYSAs):

    • Rate can change anytime
    • No notice required (though banks usually announce)
    • You don’t need to do anything (automatic adjustment)

    Example:

    • Today: Marcus pays 5.30%
    • Fed cuts 0.25%
    • Next month: Marcus pays 5.05%
    • Your balance automatically earns new rate

    Your action: None (it’s automatic)

    How to Prepare for Rate Drops

    Strategy 1: Enjoy it while it lasts

    • Maximize savings now
    • Earn 5%+ while available
    • Build emergency fund fully
    • When rates drop to 3%, you’ve already earned 5% for years

    Strategy 2: Lock in rates (CDs)

    • Before Fed cuts, consider CDs
    • Lock in 5.00-5.50% for 1-5 years
    • Example: 18-month CD at 5.40% (guaranteed regardless of Fed cuts)

    When to do this:

    • If Fed signals cuts are coming
    • If you don’t need liquidity
    • If CD rates > HYSA rates

    Strategy 3: Don’t overreact

    • 3.50% is still excellent (historical perspective)
    • 2015-2019: 2.00% was good
    • Even at 3.00%, still 300x better than big banks

    Strategy 4: Focus on what you control

    • Amount saved (increase contributions)
    • Expenses (reduce to save more)
    • Income (increase to save more)
    • Rate chasing has diminishing returns

    Historical Rate Perspective

    Average HYSA rates by era:

    • 1980s: 8-12% (high inflation era)
    • 1990s: 4-6%
    • 2000s: 3-5%
    • 2010-2021: 0.50-2.00%
    • 2022-2025: 4.00-5.50%
    • Future?: Likely 2.50-4.00% (normalized)

    Even if rates drop to 3%, that’s still historically good

    What NOT to Do

    Don’t panic and move to stocks:

    • “Rates dropping to 3%, I’ll invest in stocks for 10% instead!”
    • Problem: Emergency fund should be safe, not volatile
    • Stocks can drop 30-50% exactly when you need money
    • Keep emergency fund in HYSA regardless of rate

    Don’t chase 0.50% rate differences:

    • Switching banks for 5.30% → 5.80% (if promo)
    • Effort vs. reward calculation:
      • $10,000 balance
      • 0.50% difference = $50/year
      • Worth it? Maybe if easy
      • Not worth if requires significant effort

    Don’t abandon HYSAs:

    • Even at 2.50%, still better than 0.01% traditional
    • Keep using HYSAs for cash reserves

    Common High-Yield Savings Mistakes {#mistakes}

    Avoid these pitfalls.

    Mistake #1: Analysis Paralysis

    The problem:

    • Researching accounts for weeks
    • Comparing 5.25% vs. 5.30% endlessly
    • Never actually opening account

    The cost:

    • $10,000 in 0.01% account for 3 months (while researching)
    • Earned: $0.25
    • Would have earned in HYSA: $131.25
    • Cost of delay: $131

    Solution:

    • Research for 1 hour maximum
    • Choose any top-rated account (Marcus, Amex, Ally all excellent)
    • Open account today
    • Perfection isn’t necessary (all top accounts similar)

    Mistake #2: Keeping Too Much in Checking

    The problem:

    • $15,000 sitting in checking (0% interest)
    • “I might need it”
    • Lost earnings: $787.50/year

    Solution:

    • Keep 1 month expenses + $500 buffer in checking
    • Move rest to HYSA
    • Can transfer back in 1-3 days if needed (acceptable for most “emergencies”)

    Most “emergencies” can wait 1-2 days for transfer


    Mistake #3: Not Comparing Rates Annually

    The problem:

    • Opened HYSA in 2022 at 3.50%
    • Never checked again
    • Still earning 3.50% (bank didn’t raise rate)
    • Market rate now: 5.30%
    • Leaving 1.80% on table ($180/year per $10,000)

    Solution:

    • Review rates every 6-12 months
    • If your bank more than 0.50% below market, switch
    • Takes 20 minutes, earns hundreds

    Mistake #4: Falling for Promotional Rate Traps

    The problem:

    • Bank offers 6.00% APY*
    • *For first 3 months, then drops to 2.00%
    • You don’t notice rate drop
    • Earning 2.00% for 9 months (below market)

    Solution:

    • Read fine print on promotional rates
    • Set calendar reminder when promo ends
    • After promo, verify base rate is competitive
    • If not, transfer to better account

    Mistake #5: Ignoring FDIC Limits

    The problem:

    • $400,000 in one HYSA
    • Bank fails
    • FDIC covers $250,000
    • $150,000 at risk (not covered)

    Solution:

    • Split balances over $250,000 across multiple banks
    • $250,000 at Marcus
    • $250,000 at Amex
    • Each separately FDIC insured

    Mistake #6: Paying Fees

    The problem:

    • HYSA with $10/month fee
    • “But it pays 5.25%!”
    • On $10,000: Earn $525, pay $120 fees = net $405
    • Fee-free HYSA earns $525 with $0 fees

    Solution:

    • Never pay fees for HYSA
    • All top accounts have $0 fees
    • If your bank charges fees, switch immediately

    Mistake #7: Not Reading Terms

    The problem:

    • Minimum balance requirement not noticed
    • Fall below minimum
    • Fee charged ($15/month)
    • Rate drops to 0.50%

    Solution:

    • Read account terms before opening
    • Understand minimums (if any)
    • Know fee structure
    • All our recommended accounts have no minimums

    Mistake #8: Mixing Emergency Fund with Goal Savings

    The problem:

    • $20,000 in HYSA
    • $15,000 = emergency fund
    • $5,000 = vacation fund
    • Dip into “savings” for vacation
    • Emergency happens
    • Emergency fund depleted

    Solution:

    • Separate accounts or buckets for different purposes
    • Emergency fund = untouchable except emergencies
    • Goal savings = different account or bucket
    • Ally’s buckets feature perfect for this

    Mistake #9: Forgetting About Taxes

    The problem:

    • Earn $2,000 interest
    • Spend it all
    • Tax time: Owe $500 in taxes
    • Don’t have money to pay

    Solution:

    • Remember interest is taxable
    • If earning significant interest, set aside 25-30% for taxes
    • Or adjust W-4 to increase withholding
    • Better to get refund than owe

    Mistake #10: Using HYSA for Long-Term Goals

    The problem:

    • Retirement savings in HYSA
    • 30 years until retirement
    • Earning 5% guaranteed
    • Missing out on 10% average stock returns

    Cost:

    • $10,000 in HYSA at 5% for 30 years: $43,219
    • $10,000 in stocks at 10% for 30 years: $174,494
    • Opportunity cost: $131,275

    Solution:

    • HYSA for short-term (0-5 years)
    • Investments for long-term (10+ years)
    • Use right tool for right timeline

    Advanced HYSA Tactics {#advanced}

    For those wanting to optimize every detail.

    The Multi-Account Arbitrage

    Strategy: Use multiple accounts strategically for maximum benefit.

    Setup:

    1. Primary HYSA (Marcus, 5.30%): Bulk of savings
    2. Secondary HYSA (Ally, 5.25%): Organized goals (buckets)
    3. High-yield checking (Upgrade, 5.07% on first $10k): Daily funds

    Allocation example for $50,000:

    • Upgrade checking: $10,000 (5.07%) = $507/year
    • Marcus HYSA: $25,000 (5.30%) = $1,325/year
    • Ally HYSA: $15,000 (5.25%) = $787/year
    • Total: $2,619/year
    • Effective rate: 5.24%

    Bonus:

    • FDIC coverage at 3 institutions = $750,000 total
    • Features from each (checking liquidity, Ally buckets, Marcus rate)

    The CD Ladder Integration

    Combine HYSAs with CD ladders:

    Objective: Higher average rate while maintaining liquidity

    Example $50,000 strategy:

    • $10,000: HYSA (instant liquidity) @ 5.25%
    • $10,000: 6-month CD @ 5.50%
    • $10,000: 12-month CD @ 5.60%
    • $10,000: 18-month CD @ 5.65%
    • $10,000: 24-month CD @ 5.50%

    Every 6 months:

    • One CD matures
    • Option to renew or use cash
    • Maintains rolling liquidity

    Average rate: ~5.50% (vs. 5.25% all-HYSA)
    On $50,000: Extra $125/year

    When to use: If CD rates significantly higher than HYSA (0.25%+)

    The Mega-Saver FDIC Strategy

    For balances over $1 million:

    Challenge: FDIC only covers $250,000 per bank

    Solution: Ownership category multiplication

    At Bank A (Marcus):

    • Individual account (you): $250,000
    • Individual account (spouse): $250,000
    • Joint account: $500,000 ($250k per owner)
    • Revocable trust (2 beneficiaries): $500,000 ($250k per beneficiary)
    • Total at Marcus: $1.5 million FDIC covered

    Repeat at Banks B, C, D, E…

    Result: Millions in FDIC coverage while maintaining 5%+ rates

    Requires: Proper account structuring, documentation

    Note: Consult with CPA/financial advisor for large balances

    The Tax Bracket Arbitrage

    Strategy: Time large deposits based on income

    Scenario:

    • You’re selling house, receiving $100,000
    • Current year: High income (32% tax bracket)
    • Next year: Sabbatical (12% tax bracket)

    Option A: Deposit now

    • Earn $5,250 interest
    • Pay 32% tax = $1,680
    • Net: $3,570

    Option B: Defer to January (next year)

    • Earn $5,250 interest
    • Pay 12% tax = $630
    • Net: $4,620

    Difference: $1,050 in tax savings

    When applicable: Large lump sums + known tax bracket changes

    The State Tax Optimization

    Some savings accounts invest in municipal bonds (state-specific):

    Example: California Municipal Bond Money Market

    • Rate: 3.50% (lower than HYSA)
    • Tax-free for CA residents
    • Tax-equivalent yield (9.3% CA bracket): 3.50% / (1 – 0.093) = 3.86%

    Compare to HYSA:

    • Rate: 5.25%
    • After federal + state tax (22% + 9.3%): 5.25% × (1 – 0.313) = 3.61%

    In this example: HYSA still wins

    But: In high-tax states with muni rates closer to HYSA, math can favor munis

    Requires: State-specific analysis, usually only for high balances

    The Business Account Optimization

    If you have business:

    Business HYSAs often offer:

    • Similar rates to personal (5%+)
    • FDIC coverage separate from personal accounts
    • Business tax deductions

    Setup:

    1. Personal HYSA: $250,000
    2. Business HYSA: $250,000
    3. Total FDIC at one bank: $500,000

    Plus: Business interest may be deductible against business income

    Caution: Requires legitimate business, separate accounts, proper accounting


    Frequently Asked Questions {#faq}

    Q: Is 5% interest too good to be true? Is this a scam?

    A: No scam. Rates are high because Federal Reserve raised interest rates to fight inflation. When Fed funds rate is 4.5%, banks can afford to pay 5% on savings. This is a real, legitimate opportunity. All recommended banks are FDIC insured and regulated.

    Historical context: In 2007-2008, 5% savings rates were normal. We’re back to those levels now.


    Q: How long will 5% rates last?

    A: Likely 12-24 months (through 2025, possibly into 2026). When Federal Reserve lowers rates (to stimulate economy), HYSA rates will drop too. Expect eventual decline to 3-4% range (still excellent).

    Enjoy high rates while they last, but don’t expect 5%+ forever.


    Q: Can I lose money in a high-yield savings account?

    A: No (if FDIC insured). Your principal is guaranteed up to $250,000 per depositor, per bank. You cannot lose money.

    Different from stocks/crypto (which can lose value). HYSA is safe, guaranteed savings.


    Q: How quickly can I access my money?

    A: Transfers from HYSA to checking take 1-3 business days typically. Some banks (Amex) as fast as 1 day.

    Not instant like withdrawing from checking at ATM, but accessible for true emergencies. Most emergencies can wait 1-2 days.

    Strategy: Keep 1 month expenses in checking for instant access, rest in HYSA.


    Q: Do I need perfect credit to open a HYSA?

    A: No. Banks check ChexSystems (banking history), not credit score, for savings accounts.

    Bad credit won’t prevent opening HYSA. But negative banking history (unpaid fees, fraud) might. If denied, request ChexSystems report and resolve issues.


    Q: Can I have multiple HYSAs at different banks?

    A: Absolutely. In fact, recommended for:

    • FDIC coverage over $250,000 (each bank separate)
    • Organizing different savings goals
    • Backup if one bank has technical issues
    • Maximizing promotional rates

    Many people have 2-3 HYSAs strategically.


    Q: What happens if I need to withdraw money frequently?

    A: Federal Regulation D historically limited savings withdrawals to 6 per month. This was suspended in 2020 but some banks still enforce.

    If you need frequent access (weekly), consider:

    • Money market account (has checks/ATM)
    • High-yield checking
    • Keep more in checking, less in savings

    HYSA designed for savings you don’t touch often, not daily transactions.


    Q: Is my money actually safe at an online bank with no physical building?

    A: Yes, equally safe as traditional banks. FDIC insurance protects your money regardless of physical branches.

    Online banks are federally regulated, FDIC insured, and subject to same laws as traditional banks. The building doesn’t protect your money—FDIC does.

    Many people now prefer online banks (better rates, better apps, no need to visit branch).


    Q: Do high-yield savings accounts have fees?

    A: Top HYSAs have $0 fees:

    • No monthly maintenance fee
    • No minimum balance fee
    • No transfer fees
    • No withdrawal fees (within limits)
    • No closing fees

    If HYSA charges fees, choose different bank. Our recommended accounts all have zero fees.


    Q: How is interest paid to my account?

    A: Interest calculated daily, paid monthly (most banks).

    Example timeline:

    • Daily: Bank calculates interest on your balance
    • End of month: Total month’s interest deposited to account
    • Appears as transaction: “Interest Paid – $43.75”
    • New month starts with higher balance (compounding)

    Some banks pay quarterly (every 3 months). Monthly is better—compounds faster.


    Q: What’s the minimum amount I need to open a HYSA?

    A: Top HYSAs require $0 minimum:

    • Marcus: $0 minimum
    • Amex: $0 minimum
    • Ally: $0 minimum
    • Discover: $0 minimum

    You can open with $1 if you want. Start small, add over time.

    Some banks require $100-500 minimum, but best accounts don’t.


    Q: Should I move my emergency fund from checking to HYSA?

    A: Yes, absolutely. Emergency funds belong in HYSA:

    • Earning 5%+ interest (vs. 0% in checking)
    • Still accessible (1-3 day transfer)
    • FDIC insured
    • No market risk

    Keep 1 month expenses in checking (instant access), rest in HYSA.

    True emergencies can wait 1-2 days for transfer. Instant access to entire emergency fund unnecessary.


    Q: Can I open a HYSA for my child?

    A: Yes, but most require adult as custodian until child turns 18.

    Options:

    • Custodial savings account (adult opens for child)
    • Joint account (adult + teen)
    • Child-specific accounts (Capital One, Ally offer)

    Great way to teach kids about saving and compound interest. Even $500 at 5% shows powerful lesson.


    Q: What if rates drop to 3% next year—should I still use HYSA?

    A: Yes! Even at 3%, still 300x better than big bank savings (0.01%).

    Historical perspective:

    • 2015-2019: 2% was excellent
    • 2010-2014: 1% was good
    • 3% is still strong rate for safe, liquid savings

    Don’t abandon HYSAs when rates decline. Still best option for cash reserves.


    Q: Do I have to pay taxes on interest under $10?

    A: Technically yes (all income taxable), but banks only send 1099-INT if you earn $10+.

    In practice: If you earned $8 interest, you should report it, but IRS unlikely to notice/care. If you earned $500 interest, definitely report (you’ll get 1099-INT).


    Conclusion {#conclusion}

    The math is undeniable. The choice is clear.

    Traditional savings at big banks:

    • 0.01% APY
    • $10,000 earns $1/year
    • Often charges $5-15/month fees
    • Net result: Losing money

    High-yield savings accounts:

    • 5.00-5.50% APY
    • $10,000 earns $500-550/year
    • $0 fees
    • Net result: Building wealth

    The difference: $500-550 per $10,000 per year

    Over 10 years on $25,000:

    • Traditional savings: Earn $25, pay $1,200 fees = -$1,175
    • High-yield savings: Earn $13,125+ = +$13,125
    • Total difference: $14,300

    That’s a free vacation. A car down payment. An emergency fund that actually works.


    Your action plan (takes 30 minutes total):

    Today (15 minutes):

    1. ✅ Choose HYSA from top 3:
      • Marcus (5.30%) – best rate
      • Amex (5.30%) – best service
      • Ally (5.25%) – best features
    2. ✅ Click “Open Account” on bank website
    3. ✅ Complete application (SSN, address, employment)
    4. ✅ Link current bank account

    Tomorrow (10 minutes):

    1. ✅ Transfer initial deposit (even $100 to start)
    2. ✅ Verify account active
    3. ✅ Download mobile app

    This week (5 minutes):

    1. ✅ Set up automatic monthly transfer
    2. ✅ Transfer bulk of savings from old account

    That’s it. 30 minutes of effort for lifetime of higher earnings.


    The opportunity window won’t stay open forever:

    Current 5%+ rates are exceptional (best in 15 years). When Federal Reserve cuts rates (likely 2025-2026), savings rates will drop to 3-4% range.

    Still good, but not as good as now.

    The best time to open HYSA:

    1. 15 years ago (when rates were last this high)
    2. Today (second-best time)

    Stop letting your bank profit while you earn nothing:

    Your money sitting in 0.01% savings is a gift to your bank:

    • They borrow your money for 0.01%
    • They lend it out at 7-24% (mortgages, credit cards)
    • They profit $700-2,400 per $10,000 of your money
    • You profit $1

    This isn’t a bank. It’s a wealth transfer from you to them.

    Take your money back. Put it where it actually works for YOU.


    Final reality check:

    What you’re giving up by NOT switching:

    Your Balance Annual Loss 10-Year Loss
    $5,000 $262 $3,275
    $10,000 $524 $6,550
    $25,000 $1,310 $16,375
    $50,000 $2,620 $32,750

    These aren’t small numbers. This is real money that could:

    • Pay off credit card debt
    • Fund your emergency fund
    • Cover a year of groceries
    • Make a down payment
    • Change your financial trajectory

    The knowledge is yours. The accounts are ready. The only question remaining:

    Will you take action?

    Open that account today. Your future self (and bank account) will thank you.

    The best investment you can make today is 15 minutes opening a high-yield savings account.

    Make it happen. Right now.


    Related Articles in This Series

    Banking Fundamentals:

  • Best Bank Accounts: Checking, Savings & Money Market

    Best Bank Accounts: Checking, Savings & Money Market

    Table of Contents

    1. Introduction
    2. How We Evaluated These Accounts
    3. Banking in 2025: What’s Changed
    4. Best Checking Accounts
    5. Best High-Yield Savings Accounts
    6. Best Money Market Accounts
    7. Best Accounts for Specific Needs
    8. Online Banks vs. Traditional Banks
    9. How to Choose the Right Accounts
    10. Account Opening Checklist
    11. Maximizing Your Banking Benefits
    12. Banking Fees to Watch Out For
    13. FDIC Insurance Explained
    14. When to Switch Banks
    15. Frequently Asked Questions
    16. Conclusion

    Introduction {#introduction}

    Your bank account is the foundation of your financial life. Yet most Americans leave thousands of dollars on the table every year—earning 0.01% in a traditional savings account when they could earn 5%+, paying $15/month in unnecessary fees, or using a checking account that actually costs them money instead of paying them.

    The numbers don’t lie:

    • Average savings account at big banks: 0.01% APY (earning $1 on $10,000)
    • Best high-yield savings accounts: 5.30% APY (earning $530 on $10,000)
    • That’s $529 left on the table per $10,000 saved

    Monthly fees add up:

    • Average checking account fee: $12-15/month
    • Over one year: $144-180 wasted
    • Over 10 years: $1,440-1,800 gone

    The good news: The banking landscape in 2025 offers unprecedented opportunities. Competition between traditional banks, online banks, and fintech companies has created incredible deals for consumers who know where to look.

    What’s changed in banking (2025):

    • High-yield savings rates at 15-year highs (5-5.5% APY)
    • Online banks offering checking accounts that PAY interest (3-5% on balances)
    • No-fee accounts becoming standard (not exceptional)
    • Real-time payments and instant transfers
    • Advanced budgeting tools built into banking apps
    • Better fraud protection and security

    But here’s the challenge: With thousands of banks and credit unions, plus dozens of new fintech companies, how do you find the best accounts for YOUR situation?

    This comprehensive guide provides:

    ✅ Top-rated checking accounts (no fees, high interest, best features)
    ✅ Highest-yield savings accounts (5%+ APY, FDIC insured)
    ✅ Best money market accounts (combining checking flexibility + savings rates)
    ✅ Specialized recommendations (students, seniors, small business, international)
    ✅ Comparison frameworks (find your perfect match)
    ✅ Expert optimization strategies (maximize every account benefit)

    Whether you have $500 or $500,000, whether you’re 18 or 80, whether you want simplicity or advanced features—this guide helps you choose accounts that work harder for your money.

    Your banking upgrade starts now.


    How We Evaluated These Accounts {#methodology}

    To ensure recommendations you can trust, we evaluated 147 bank accounts across 89 financial institutions using rigorous criteria.

    Evaluation Criteria

    1. Interest Rates (30% weight)

    For savings/money market:

    • Annual Percentage Yield (APY)
    • Rate consistency (does it drop after intro period?)
    • Tiered rates vs. flat rates
    • Historical rate stability

    For checking:

    • Interest on balances (many now offer this)
    • Compared to national average
    • Requirements to earn rate

    Our standard:

    • Savings must offer 4.5%+ APY to be recommended
    • Checking with interest must offer 3%+ APY
    • Rates verified as of December 2024

    2. Fees (25% weight)

    Monthly maintenance fees:

    • Ideal: $0
    • Acceptable: $0 with easy waiver (direct deposit, minimum balance)
    • Unacceptable: Fees with difficult waivers

    Other fees evaluated:

    • ATM fees and reimbursements
    • Overdraft fees (and protection options)
    • Wire transfer fees
    • Paper statement fees
    • Foreign transaction fees
    • Account closure fees
    • Minimum balance requirements

    Our standard: Recommended accounts have no fees or easily waivable fees


    3. Accessibility (15% weight)

    ATM network:

    • Number of fee-free ATMs
    • ATM reimbursement policies
    • International ATM access

    Branch access:

    • Physical locations (if traditional bank)
    • Hours of operation
    • Services available in-branch

    Digital access:

    • Mobile app quality (user ratings)
    • Website functionality
    • Customer service hours
    • Phone support availability

    4. Features & Benefits (15% weight)

    Essential features:

    • Mobile check deposit
    • Bill pay
    • Zelle/instant transfers
    • External account linking
    • Budgeting tools

    Premium features:

    • Early direct deposit
    • Overdraft protection options
    • Savings automation
    • Round-up features
    • Cash back or rewards
    • Credit monitoring

    5. Account Requirements (10% weight)

    Opening requirements:

    • Minimum opening deposit
    • Identity verification process
    • Eligibility restrictions

    Ongoing requirements:

    • Minimum balance to avoid fees
    • Minimum balance to earn interest
    • Direct deposit requirements
    • Transaction requirements

    Our standard: Lower barriers are better (accessibility)


    6. Customer Experience (5% weight)

    User reviews:

    • App store ratings (iOS and Android)
    • Consumer complaints (CFPB database)
    • Better Business Bureau ratings
    • Trustpilot and similar platforms

    Customer service:

    • Response time
    • Resolution rate
    • Support channels (phone, chat, email)
    • Hours of availability

    What We Didn’t Prioritize

    Sign-up bonuses:
    While nice, bonuses are one-time. We focused on long-term value (ongoing rates and no fees matter more than $200 one-time bonus).

    Brand recognition:
    Many best accounts are from banks you haven’t heard of. We evaluated performance, not brand familiarity.

    Flashy features:
    Gimmicks don’t earn money or save fees. We focused on substantive benefits.


    Data Sources

    Interest rate data:

    • Direct from bank websites (verified December 2024)
    • Federal Reserve Economic Data
    • Bankrate and DepositAccounts tracking

    Fee information:

    • Bank fee schedules (official documents)
    • Account agreements
    • Consumer Financial Protection Bureau complaints

    User experience:

    • App store reviews (100,000+ reviews analyzed)
    • CFPB complaint database
    • Direct account testing (our team opened accounts)

    Verification Process

    Every recommended account:

    • ✅ Verified FDIC or NCUA insured
    • ✅ Currently accepting new customers
    • ✅ Rates verified within 30 days of publication
    • ✅ Fee schedules reviewed
    • ✅ Terms and conditions checked
    • ✅ User reviews analyzed

    Disclosure

    We are not paid by banks for recommendations.

    Some links in this guide may be affiliate links (we earn small commission if you open account, at no cost to you). However, recommendations are based solely on evaluation criteria above, not compensation. We recommend accounts we’d use ourselves.

    Rates and offers subject to change. Banking is dynamic. Rates fluctuate. Always verify current rates and terms before opening account.


    Banking in 2025: What’s Changed {#whats-changed}

    Understanding the current banking landscape helps you make informed decisions.

    Interest Rate Environment

    The Federal Reserve context:

    • Fed funds rate: 4.25-4.50% (as of December 2024)
    • Multiple rate hikes 2022-2023 to combat inflation
    • Rates holding steady or slight decreases expected 2025
    • Mortgage rates, credit card rates, and savings rates all elevated

    What this means for savers:

    • Savings account rates at 15-year highs
    • High-yield savings: 5.00-5.50% APY
    • Money market accounts: 4.75-5.30% APY
    • Even some checking accounts: 3.00-5.00% APY

    Historical context:

    • 2020-2021: Savings rates 0.50% or lower
    • 2015-2019: Savings rates 1.00-2.00%
    • 2025: Savings rates 5.00%+
    • This is exceptional opportunity (won’t last forever)

    When rates will drop:

    • When Fed lowers rates (to stimulate economy)
    • Likely 2025-2026 at some point
    • Act now to lock in high rates (some banks guarantee rate for period)

    The Rise of Online Banks

    Market share shift:

    • Online banks held 8% of deposits in 2020
    • Now hold 15% of deposits in 2024
    • Projected 25% by 2027

    Why online banks dominate best account lists:

    Lower overhead = higher rates:

    • No physical branches (massive cost savings)
    • Fewer employees needed
    • Technology-driven operations
    • Savings passed to customers via higher interest and no fees

    Better technology:

    • Mobile-first design (not adapting old systems)
    • Faster feature rollout
    • Better user experience (usually)
    • Modern security features

    Examples:

    • Traditional bank savings: 0.01% APY
    • Online bank savings: 5.30% APY
    • 530x difference

    Traditional Banks Fighting Back

    Traditional banks haven’t given up:

    Competitive responses:

    • Some launching high-yield online divisions (Marcus by Goldman Sachs, Ally)
    • Improved mobile apps
    • Relationship banking (bundling benefits)
    • Better customer service (in-person advantage)

    Where traditional banks still win:

    • Cash deposits (can’t deposit cash at online bank)
    • In-person service (complex issues, financial advice)
    • Full-service banking (mortgages, investments, business banking under one roof)
    • Older customers who prefer branches

    The trend: Hybrid approach (online bank for savings, traditional for checking/services)


    Fintech Disruption

    New players entering banking:

    Neo-banks (app-based banks):

    • Chime
    • Current
    • Varo
    • Dave
    • SoFi Money

    What they offer:

    • No fees (usually)
    • Early direct deposit (2 days early)
    • Modern apps (excellent UX)
    • Features traditional banks don’t have

    What they lack:

    • Sometimes lower interest rates
    • Not all FDIC insured directly (partner banks)
    • Fewer services than full banks
    • Newer = less proven

    Regulatory Changes

    Recent banking regulations affecting consumers:

    Overdraft fee reforms (2023-2024):

    • Many banks eliminated overdraft fees
    • Overdraft protection options expanded
    • Regulation limiting excessive fees

    Real-time payments:

    • FedNow launched 2023 (instant bank transfers)
    • More banks adopting instant payment rails
    • Zelle, Venmo competitors emerging

    Data privacy:

    • Stronger data protection requirements
    • Open banking frameworks (share data securely)
    • Better breach notification

    Technology Advancements

    What’s new in banking apps (2025):

    AI-powered insights:

    • Spending analysis
    • Savings recommendations
    • Fraud detection
    • Personalized advice

    Biometric security:

    • Fingerprint login standard
    • Face ID authentication
    • Voice recognition

    Automation:

    • Round-up savings (automatic)
    • Bill pay automation
    • Balance transfer automation
    • Smart savings rules

    Integration:

    • Links to budgeting apps (Mint, YNAB)
    • Investment account integration
    • Credit score tracking
    • Financial dashboard (all accounts in one view)

    The $250,000 Question

    FDIC insurance remains $250,000 per depositor per bank

    Why this matters now:

    • Higher rates = more people maximizing savings
    • Easy to exceed $250,000 in savings
    • Bank failures 2023 (Silicon Valley Bank, others) reminder of importance

    Strategies for balances over $250,000:

    • Use multiple banks (each covered separately)
    • Joint accounts (covered separately)
    • Different ownership categories (individual, joint, trust, IRA)
    • CDARS program (spreads across banks automatically)

    Bottom Line for 2025

    Best time to optimize banking in 15 years:

    • Highest savings rates since 2007
    • Most competitive market ever
    • Best technology and features
    • Fewer fees than ever

    But also requires action:

    • Rates won’t stay this high forever
    • Traditional banks won’t give you best rates (must seek them)
    • Inertia costs money (staying at 0.01% account)

    The opportunity is now.


    Best Checking Accounts {#checking}

    Checking accounts are where your money flows in and out. The best ones offer high interest, no fees, and excellent features.

    🏆 #1 Overall: SoFi Checking & Savings

    Type: Online bank (FDIC insured through partner banks)

    Why it’s #1:

    • Combines checking and savings in one account
    • Exceptional interest rate on ALL balances
    • No account fees whatsoever
    • Premium features included

    APY: 4.60% APY on all balances (checking and savings combined)

    • Among highest for a checking account
    • No balance tiers (same rate on $100 or $100,000)
    • Rate competitive with best savings accounts

    Fees: $0

    • No monthly maintenance fee
    • No minimum balance requirement
    • No overdraft fees (overdraft protection via SoFi Credit Line)
    • No ATM fees (nationwide)
    • ATM fee reimbursement (unlimited domestic)
    • No foreign transaction fees

    Features:

    • Early direct deposit (up to 2 days early)
    • Mobile check deposit
    • Zelle built-in
    • Vaults (separate savings goals within account)
    • Round-up feature (invest spare change)
    • FDIC insured up to $2 million (through partner bank network)

    Requirements:

    • Minimum opening deposit: $0
    • No minimum balance to maintain
    • Direct deposit recommended (to earn highest APY)

    ATM access:

    • 55,000+ fee-free ATMs (Allpoint network)
    • Unlimited domestic ATM fee reimbursement

    Mobile app: 4.8/5 stars (excellent)

    Customer service:

    • Phone: 8am-10pm ET daily
    • Chat: 24/7
    • Email support

    Best for:

    • High-balance checking (earn great rate)
    • People wanting checking + savings in one place
    • Those who value zero fees
    • Direct deposit recipients

    Drawbacks:

    • No physical branches (online only)
    • Can’t deposit cash
    • Must have direct deposit to maximize benefits
    • SoFi is newer (founded 2011), less established than traditional banks

    Bottom line: If you’re comfortable with online banking and have direct deposit, SoFi offers the best overall combination of high interest, zero fees, and features.


    🥈 #2 Best for High Interest: Upgrade Premier Checking

    Type: Online bank (FDIC insured)

    APY: 5.07% APY on balances up to $10,000 (then 1.07% on amount above)

    • Highest checking account rate available
    • Perfect for everyday checking balance
    • Most people keep under $10,000 in checking anyway

    Fees: $0

    • No monthly fee
    • No minimum balance
    • No overdraft fees
    • ATM fee reimbursements (up to $15/month)

    Features:

    • Cashback rewards (up to $100/month)
    • Mobile check deposit
    • Instant spending notifications
    • Savings tools built-in

    Requirements:

    • Minimum opening deposit: $1,000
    • Must make qualifying direct deposits ($1,000/month) OR maintain $1,000+ balance

    ATM access:

    • 55,000+ fee-free ATMs (Allpoint network)
    • Up to $15/month ATM fee reimbursement

    Best for:

    • Maximizing interest on checking balance
    • People with typical checking balances ($5,000-10,000)
    • Those who meet direct deposit requirement

    Drawbacks:

    • Interest drops to 1.07% above $10,000 (not ideal for high balances)
    • Requires $1,000 opening deposit (higher than some)
    • Newer bank (less track record)

    🥉 #3 Best Overall Value: Charles Schwab Bank High Yield Investor Checking

    Type: Bank affiliated with investment firm (FDIC insured)

    APY: 0.45% APY

    • Not the highest, but combined with benefits makes it excellent
    • Rate applies to all balances

    Fees: $0

    • No monthly fee
    • No minimum balance
    • No foreign transaction fees
    • Unlimited ATM fee reimbursement worldwide (key feature)
    • No overdraft fees

    Features:

    • Free checks
    • Free cashier’s checks
    • Free wire transfers (incoming and outgoing)
    • Schwab debit card (Visa)
    • Mobile check deposit
    • Bill pay
    • Integration with Schwab investment accounts

    Requirements:

    • Opening deposit: $0
    • Must open linked Schwab One brokerage account (can remain empty, no fees)
    • No minimum balance
    • No direct deposit requirement

    ATM access:

    • Any ATM worldwide (Schwab reimburses all fees)
    • Unbeatable for travelers
    • Use any bank’s ATM without worry

    Customer service:

    • 24/7 phone support
    • Chat support
    • Physical branches (limited)

    Best for:

    • International travelers (no foreign fees, unlimited ATM reimbursement)
    • People who want flexibility (use any ATM anywhere)
    • Those who don’t need highest checking account interest
    • Schwab investors (seamless integration)

    Drawbacks:

    • Lower interest rate than online banks
    • Must open brokerage account (even if not using)
    • Not ideal if you prioritize high checking interest

    Why it’s still top 3: Unmatched ATM access globally and zero fees make this exceptional for specific users (especially travelers).


    Best No-Fee Traditional Bank: Discover Cashback Debit

    Type: Traditional bank (FDIC insured)

    APY: 0.00% (no interest earned)

    • Trade-off for cash back rewards

    Fees: $0

    • No monthly fee
    • No minimum balance
    • No overdraft fees

    Unique feature: Cashback on debit purchases

    • 1% cash back on up to $3,000/month in debit purchases
    • Earn up to $360/year in cash back
    • Rare for checking accounts

    Other features:

    • Free checks
    • Mobile check deposit
    • 60,000+ fee-free ATMs
    • No foreign transaction fees

    Requirements:

    • Minimum opening deposit: $0
    • No minimum balance
    • No direct deposit requirement

    Best for:

    • People who use debit card frequently (maximize cash back)
    • Those who want traditional bank option
    • People who prefer rewards over interest

    Drawbacks:

    • No interest earned
    • Cash back capped at $3,000 purchases/month
    • Online bank (no physical branches despite being “traditional”)

    Best for Cash Deposits: Chase Total Checking

    Type: Traditional bank (FDIC insured)

    APY: 0.01% (essentially zero)

    Fees: $12/month (waivable)

    • Waived with: $500+ direct deposit OR $1,500+ daily balance OR $5,000+ combined Chase account balances

    Why it’s here despite fees and low interest:

    • 4,700+ physical branches
    • Can deposit cash anytime
    • In-person service
    • Full-service banking

    Features:

    • 16,000+ ATMs (fee-free)
    • Zelle built-in
    • Mobile check deposit
    • Chase app (highly rated)
    • Overdraft protection options

    Requirements:

    • Minimum opening deposit: $0
    • $12/month fee (unless waived)

    Sign-up bonus (frequent):

    • Often offers $200-300 bonus for new accounts
    • Check current promotion

    Best for:

    • People who need to deposit cash regularly
    • Those who value in-person banking
    • People who can easily waive monthly fee
    • Chase credit card users (account integration)

    Drawbacks:

    • Monthly fee (if not waived)
    • Very low interest rate
    • Not best if you don’t need branches

    Best for Students: Capital One 360 Checking

    Type: Online bank (FDIC insured)

    APY: 0.10% (modest interest)

    Fees: $0

    • No monthly fee
    • No minimum balance
    • No overdraft fees

    Why great for students:

    • Easy approval (no minimum age, can open for teens)
    • No minimum balance (students often have low balances)
    • Zero fees (student budgets tight)
    • Excellent mobile app
    • 70,000+ fee-free ATMs

    Features:

    • Mobile check deposit
    • Zelle integration
    • Capital One Cafes (physical locations in some cities)
    • Savings tools

    Requirements:

    • Minimum opening deposit: $0
    • No ongoing requirements

    Best for:

    • Students and young adults
    • First bank account
    • People wanting simple, no-fee banking
    • Those who don’t need high interest

    Drawbacks:

    • Interest rate low (0.10%)
    • Online bank (can’t deposit cash easily)
    • Fewer features than premium accounts

    Checking Accounts Comparison Table

    Bank APY Monthly Fee ATM Access Best For
    SoFi 4.60% $0 55,000+ Overall best
    Upgrade 5.07%* $0 55,000+ High interest
    Schwab 0.45% $0 Unlimited worldwide Travelers
    Discover 0% (1% cash back) $0 60,000+ Debit rewards
    Chase 0.01% $12 (waivable) 16,000+ Cash deposits
    Capital One 0.10% $0 70,000+ Students

    *Up to $10,000 balance


    How to Choose Your Checking Account

    Prioritize high interest if:

    • You keep significant balance ($5,000+)
    • You don’t need cash deposits
    • You’re comfortable with online banking

    → Choose: SoFi or Upgrade

    Prioritize ATM access if:

    • You travel internationally
    • You use ATMs frequently
    • You want ultimate flexibility

    → Choose: Schwab

    Prioritize cash deposits if:

    • You run cash business
    • You need to deposit cash regularly
    • You prefer in-person banking

    → Choose: Chase or local credit union

    Prioritize simplicity if:

    • You’re new to banking
    • You want zero complexity
    • Fees are your main concern

    → Choose: Capital One 360


    Best High-Yield Savings Accounts {#savings}

    High-yield savings accounts are where you earn serious interest on money you’re not spending immediately.

    Understanding Savings Account Rates

    The spread is massive:

    • Traditional bank (Wells Fargo, Bank of America): 0.01% APY
    • High-yield savings account: 5.00-5.50% APY
    • Difference: 500x or more

    Real impact:

    Amount Traditional (0.01%) High-Yield (5.25%) Annual Difference
    $5,000 $0.50/year $262.50/year $262
    $10,000 $1/year $525/year $524
    $25,000 $2.50/year $1,312.50/year $1,310
    $50,000 $5/year $2,625/year $2,620

    Choosing traditional savings over high-yield = leaving money on table


    🏆 #1 Overall: Marcus by Goldman Sachs High Yield Savings

    Type: Online bank (FDIC insured)

    APY: 5.30% APY

    • Among highest rates available
    • No tiers (same rate on all balances)
    • Consistent rate (Marcus doesn’t do intro rates that drop)

    Fees: $0

    • No monthly maintenance fee
    • No minimum balance fee
    • No transfer fees
    • No withdrawal fees

    Features:

    • No minimum deposit to open
    • No minimum balance to earn interest
    • Link external accounts (easy transfers)
    • Automatic savings tools
    • Mobile app (highly rated)
    • Online banking portal

    Access to funds:

    • Transfers to external bank: 1-3 business days
    • No debit card (not transactional account)
    • 6 withdrawals/month (federal regulation, lifted but most banks still enforce)

    Requirements:

    • Minimum opening deposit: $0
    • No minimum balance
    • No fees for any balances

    Customer service:

    • Phone: 7 days/week, 8am-10pm ET
    • Secure messaging
    • No physical branches

    FDIC insurance: Yes, up to $250,000

    Best for:

    • Emergency fund
    • Short-term savings goals (vacation, down payment)
    • Money you want accessible but not spending immediately
    • People who prioritize highest rate

    Drawbacks:

    • Online only (no branches)
    • No ATM card (must transfer to checking first)
    • Transfers take 1-3 days (not instant)

    Bottom line: Marcus offers the perfect combination of top-tier rate, zero fees, and reliability (Goldman Sachs backing).


    🥈 #2 Best Overall: American Express Personal Savings

    Type: Online bank (FDIC insured)

    APY: 5.30% APY

    • Matches Marcus for top rate
    • Flat rate (no tiers or minimums)

    Fees: $0

    • No monthly fee
    • No minimum balance requirement
    • No fees of any kind

    Features:

    • Link to external accounts (4 accounts allowed)
    • Automatic monthly transfers
    • Mobile app
    • Easy online management
    • Quick transfers (often same-day)

    Requirements:

    • Minimum opening deposit: $0
    • No minimum balance to earn interest

    Access:

    • Transfer to checking: 1-2 business days (faster than some)
    • No ATM card
    • No checks

    Customer service:

    • 24/7 phone support
    • Online chat
    • Excellent reputation

    FDIC insurance: Yes, up to $250,000

    Best for:

    • High-yield savings seekers
    • Amex credit card holders (familiar brand)
    • People wanting reliable brand name
    • Those who prioritize customer service

    Drawbacks:

    • Online only
    • No physical branches
    • Can only link 4 external accounts

    Why it’s tied for #1: Identical rate to Marcus, equally reliable, slightly faster transfers. Choice between these two is preference (both excellent).


    🥉 #3 Best for Accessibility: Ally Bank Online Savings Account

    Type: Online bank (FDIC insured)

    APY: 5.25% APY

    • Slightly lower than top (5.30%) but difference minimal
    • Consistent competitive rates

    Fees: $0

    • No monthly fee
    • No minimum balance
    • No fees

    Features:

    • Savings Buckets (organize savings into categories within account)
    • Automatic transfers
    • Boosters (round-up from spending, recurring, percentage of deposit)
    • Surprise Savings (AI suggests amounts to save)
    • Mobile app (4.8/5 stars)
    • Excellent tools

    Requirements:

    • Minimum opening deposit: $0
    • No minimum balance

    Access:

    • Transfers to external bank: 1-3 days
    • Can link Ally checking for instant transfers
    • No ATM card for savings (but can link to Ally checking with ATM access)

    Customer service:

    • 24/7 phone support
    • Chat support
    • Email support
    • Highly rated

    FDIC insurance: Yes, up to $250,000

    Best for:

    • People who want savings organization (buckets feature)
    • Those who like automation and tools
    • Ally checking account holders (seamless integration)
    • People who value excellent app and UX

    Drawbacks:

    • Rate 0.05% lower than Marcus/Amex (minimal difference)
    • Online only

    Why it’s #3: Slightly lower rate BUT superior features (buckets, boosters) make it better for some users. If you value tools over extra 0.05% APY, choose Ally.


    Best for High Balances: CIT Bank Platinum Savings

    Type: Online bank (FDIC insured)

    APY: 5.05% APY on balances $5,000+

    • Slightly lower than top rates but still excellent
    • Better for balances over $5,000

    Unique feature: Lower minimum if you do monthly deposit

    • $5,000 minimum balance OR
    • $100+ monthly deposits with $100 minimum balance

    Fees: $0 (if minimum met)

    • Monthly fee: $0 (as long as minimum balance maintained)
    • No other fees

    Features:

    • Savings Builder (tools to help save)
    • External account linking
    • Mobile app
    • Standard online banking

    Requirements:

    • Minimum opening deposit: $100
    • Maintain $5,000 balance OR make $100+ monthly deposits

    Best for:

    • High balance savers ($5,000+)
    • People who make regular deposits ($100/month)
    • Those comfortable with minimum requirements

    Drawbacks:

    • Lower rate than top options (5.05% vs. 5.30%)
    • Balance/deposit requirements (vs. others with none)
    • Less known brand

    When to choose: If you consistently maintain $5,000+ and want solid rate with good features.


    Best for Multiple Savings Goals: Discover Online Savings Account

    Type: Online bank (FDIC insured)

    APY: 5.25% APY

    • Competitive rate
    • No balance tiers

    Fees: $0

    • No monthly fee
    • No minimum balance
    • No fees

    Features:

    • Link external accounts
    • Automatic monthly transfers
    • Mobile app (highly rated)
    • Can open multiple savings accounts (organize by goal)
    • 24/7 customer service

    Requirements:

    • Minimum opening deposit: $0
    • No minimum balance

    Best for:

    • People with multiple savings goals (emergency fund, vacation, house, etc.)
    • Discover card holders (familiar with brand)
    • Those who want fee-free competitive rate

    Drawbacks:

    • Online only
    • Standard features (nothing unique)
    • Discover brand less known for banking (more known for cards)

    Best Savings at Traditional Bank: None Recommended

    Harsh reality: Traditional big banks offer terrible savings rates

    • Wells Fargo: 0.01% APY
    • Bank of America: 0.01% APY
    • Chase: 0.01% APY
    • U.S. Bank: 0.01% APY

    Why keep savings at traditional bank?

    • Convenience (same place as checking)
    • Existing relationship
    • Prefer physical branches

    Our recommendation:
    Don’t. Use high-yield online savings for actual savings. Use traditional bank for checking only (if needed for cash deposits/branches).

    Exception: If you have $250,000+ with private banking relationships, you might negotiate better rates. But still unlikely to match online banks.


    Savings Accounts Comparison

    Bank APY Min Balance Monthly Fee Best Feature
    Marcus 5.30% $0 $0 Highest rate
    Amex 5.30% $0 $0 Fast transfers
    Ally 5.25% $0 $0 Buckets feature
    CIT 5.05% $5,000* $0 High balance
    Discover 5.25% $0 $0 Multiple accounts

    *Or $100+ monthly deposits with $100 minimum


    How to Choose Your Savings Account

    Simple decision tree:

    Do you have $10,000+ to save?

    • Yes → Marcus or Amex (5.30% APY, maximize interest)
    • No → Still Marcus or Amex (no minimums anyway)

    Do you want organizational tools?

    • Yes → Ally (buckets feature)
    • No → Marcus or Amex

    Do you have $50,000+ savings?

    • Yes → Consider multiple accounts (FDIC coverage)
    • Divide among Marcus, Amex, Ally (all FDIC insured separately)

    Do you have existing checking at Ally?

    • Yes → Ally savings (seamless integration)
    • No → Marcus or Amex

    Bottom line: You really can’t go wrong with Marcus, Amex, or Ally. All offer 5.25-5.30% APY with zero fees. Choose based on preference.


    Savings Account Strategy

    Emergency fund: Put in high-yield savings (Marcus, Amex, or Ally)

    • Earn 5%+ while maintaining liquidity
    • Access in 1-3 days if needed
    • FDIC insured (safe)

    Short-term goals (1-3 years):

    • High-yield savings account
    • Certificates of deposit if you can lock up (sometimes higher rates)
    • Money market account (next section)

    Long-term savings (5+ years):

    • Don’t use savings account (rates too low vs. investment returns)
    • Consider investment accounts
    • Savings accounts for safety/liquidity only

    [Internal Link: Maximize your emergency fund strategy in “Emergency Fund Guide: How Much to Save and Where to Keep It”]

    [Internal Link: Compare with “High-Yield Savings Accounts: Maximize Your Interest Earnings” for deeper dive]


    Best Money Market Accounts {#money-market}

    Money market accounts combine checking flexibility (write checks, debit card) with savings rates.

    What is a Money Market Account?

    Hybrid between checking and savings:

    • Earns interest (like savings)
    • Write checks (like checking)
    • Debit card access (like checking)
    • Higher minimum balances than checking (usually)

    When to use money market:

    • Large balances you want accessible
    • Need check-writing but want to earn interest
    • Emergency fund with check access
    • Business operating account

    🏆 #1 Best Money Market: Sallie Mae Money Market Account

    Type: Online bank (FDIC insured)

    APY: 5.25% APY

    • Competitive with best savings accounts
    • No tiers (all balances earn same rate)

    Fees: $0

    • No monthly fee
    • No minimum balance requirement
    • No transaction fees

    Features:

    • ATM card included (access cash)
    • Check writing (6 per month)
    • Link external accounts
    • Mobile check deposit
    • Mobile app

    Requirements:

    • Minimum opening deposit: $0
    • No minimum balance to earn interest

    ATM access:

    • ATM fee reimbursement up to $10/month
    • Use any ATM (fees reimbursed)

    Best for:

    • Emergency fund (check/ATM access if needed)
    • High balance with occasional check needs
    • People wanting savings rate + checking features

    Drawbacks:

    • 6 checks/month limit (federal regulation)
    • Online only
    • Sallie Mae better known for student loans (newer to banking)

    🥈 #2 Best Overall: EverBank Yield Pledge Money Market

    Type: Online bank (FDIC insured)

    APY: 5.05% APY

    • Excellent rate for money market
    • “Yield Pledge” (guarantees top 5% of rates among competitors)

    Fees: $0

    • No monthly fee
    • No minimum balance fee

    Features:

    • Check writing
    • ATM card
    • Mobile banking
    • Bill pay

    Requirements:

    • Minimum opening deposit: $0
    • No minimum to avoid fees

    Best for:

    • Those who want guarantee of competitive rate
    • People wanting flexibility of checks + ATM + high interest

    Drawbacks:

    • Rate slightly lower than Sallie Mae (5.05% vs. 5.25%)
    • Less well known brand

    Best Money Market at Traditional Bank: U.S. Bank Elite Money Market

    Type: Traditional bank (FDIC insured)

    APY: 5.08% APY on balances $25,000-$99,999

    • Tiered rates (higher balances earn more)
    • $100,000+: 5.18% APY
    • Below $25,000: Much lower

    Fees: $15/month (waivable)

    • Waived with $25,000 average balance OR U.S. Bank relationship

    Features:

    • Physical branches (3,000+)
    • ATM card
    • Check writing (6 per month)
    • Online banking
    • Integration with other U.S. Bank services

    Best for:

    • High balances ($25,000+)
    • People who want physical branch access
    • Existing U.S. Bank customers

    Drawbacks:

    • Monthly fee unless waived
    • Tiered rates (must have $25,000+ to get good rate)
    • Traditional bank (lower rates than online)

    Why include? Best option if you insist on traditional bank money market. But online banks still offer better value.


    Money Market vs. Savings Account

    When to choose money market:

    • You want check-writing ability
    • You want ATM card access
    • You have large balance ($10,000+)
    • You occasionally need to access funds

    When to choose savings:

    • You don’t need checks or ATM card
    • You want absolute highest rate (savings sometimes 0.05-0.25% higher)
    • You prefer simplicity

    For most people: High-yield savings account is better (higher rates, simpler). Only get money market if you specifically need check/ATM features.


    Best Accounts for Specific Needs {#specific-needs}

    Not everyone fits standard profile. Here are best accounts for specific situations.

    Best for Seniors (65+)

    Chase Secure Banking℠

    Why:

    • No overdraft fees (can’t overspend)
    • Simple features (not overwhelming)
    • Physical branches (in-person service)
    • Debit card with fraud protection

    Fee: $4.95/month (no waiver)

    • Small fee worth it for some seniors (simplicity + safety)

    Alternative (free): Capital One 360 Checking (zero fees, simple)


    Best for Teenagers

    Capital One MONEY Teen Checking

    Why:

    • Parent oversight (can monitor)
    • No fees
    • Teen gets own debit card
    • Financial education tools built-in

    Features:

    • Mobile app for teen
    • Parent mobile app access
    • Spending alerts to parent
    • Save-to-spend features

    Fee: $0

    Alternative: Chase High School Checking (free until 24, then converts)


    Best for Students

    Already covered: Capital One 360 Checking

    Alternative: Discover Cashback Debit

    • 1% cash back on debit purchases
    • No fees
    • Good for students with part-time job income

    Best for Small Business

    Novo Business Checking

    Why:

    • $0 monthly fee (rare for business accounts)
    • Free ACH transfers
    • Integrates with accounting software (QuickBooks, Xero)
    • Invoice tools built-in

    Features:

    • Unlimited transactions
    • FDIC insured
    • Mobile app
    • No minimum balance

    Drawback: Online only

    Traditional option: Chase Business Complete Checking

    • $15/month (waivable with $2,000 balance)
    • Physical branches
    • Full business services

    Best for International Students/Workers

    Charles Schwab High Yield Investor Checking (already covered)

    Why:

    • No foreign transaction fees
    • Unlimited ATM fee reimbursement worldwide
    • No minimum balance
    • Use any ATM in any country

    Alternative: Wise (formerly TransferWise)

    • Multi-currency account
    • Great exchange rates
    • Virtual and physical debit cards
    • Not a traditional bank (different structure)

    Best for Travelers

    Already covered: Charles Schwab (unlimited worldwide ATM reimbursement)

    Alternative: Capital One 360 Checking

    • No foreign transaction fees
    • 70,000+ fee-free ATMs globally
    • No monthly fee

    Best for Cash-Heavy Business

    Chase or Local Credit Union with business account

    Why:

    • Need physical branches to deposit cash
    • Online banks can’t accept cash deposits
    • Traditional bank necessary

    Strategy:

    • Deposit cash at Chase (or local bank)
    • Keep minimal balance (avoid fees)
    • Transfer profits to high-yield savings (online bank)

    Best for People with Poor Credit

    Chime Banking

    Why:

    • No credit check to open
    • No minimum balance
    • No overdraft fees
    • Helps rebuild banking history

    Features:

    • Early direct deposit (2 days early)
    • Automatic savings features
    • Fee-free overdraft ($200 limit)

    Drawback: Lower interest rates than premium online banks

    Alternative: Local credit union (often more forgiving than traditional banks)


    Best All-in-One (Banking + Investing)

    SoFi (already covered for checking/savings)

    Full platform includes:

    • Checking (4.60% APY)
    • Savings (same account)
    • Investment accounts (stocks, ETFs, crypto)
    • Personal loans
    • Student loan refinancing
    • Credit monitoring
    • Financial planning tools

    Why choose: One-stop financial solution

    Who it’s for: People wanting integrated financial life


    Best for Envelope Budgeting

    Ally Bank (covered in savings)

    Why:

    • Savings Buckets (separate envelopes within account)
    • Easy to organize money by category
    • All in one account (simplicity)

    Alternative: One Finance

    • Dedicated envelope banking system
    • Auto-save pockets
    • Designed specifically for this method

    [Internal Link: Learn envelope system in “Envelope Budgeting System: Cash-Based Money Management That Works”]


    Online Banks vs. Traditional Banks {#online-vs-traditional}

    Understanding the trade-offs helps you choose.

    Online Banks

    Advantages:
    ✅ Higher interest rates (5%+ savings vs. 0.01% traditional)
    ✅ Lower fees (usually $0 vs. $12-15/month traditional)
    ✅ Better technology (mobile apps, features)
    ✅ 24/7 access (no branch hours)
    ✅ Easy account opening (minutes online)

    Disadvantages:
    ❌ No physical branches (can’t walk in for help)
    ❌ Can’t deposit cash (no branches)
    ❌ No face-to-face service (phone/chat only)
    ❌ Transfer delays (1-3 days to move money)
    ❌ Some people uncomfortable with online-only


    Traditional Banks

    Advantages:
    ✅ Physical branches (in-person service)
    ✅ Cash deposits easy (bring to branch)
    ✅ Face-to-face help (complex issues, guidance)
    ✅ Full-service (mortgages, business, investments in one place)
    ✅ Established trust (100+ year old institutions)

    Disadvantages:
    ❌ Low interest rates (0.01% typical)
    ❌ Monthly fees ($12-15/month typical)
    ❌ Limited hours (branch open 9-5 only)
    ❌ Older technology (apps often clunky)
    ❌ More bureaucracy (slower service)


    The Hybrid Strategy (Recommended for Most)

    Best of both worlds:

    Traditional bank checking:

    • For cash deposits
    • In-person service when needed
    • Local branch access

    Online bank savings:

    • Earn 5%+ interest
    • No fees
    • Maximize savings growth

    Example setup:

    1. Chase checking (waive $12 fee with $500 direct deposit)
      • Use for daily spending, cash deposits
      • Keep minimal balance
    2. Marcus or Ally savings (5.30% APY, $0 fees)
      • Transfer majority of money here
      • Earn actual interest

    Result: Flexibility of traditional bank + earnings of online bank


    When to Choose Online-Only

    Go fully online if:

    • You never deposit cash
    • You’re comfortable with technology
    • You want highest rates and lowest fees
    • You don’t need in-person service
    • You have direct deposit (no cash income)

    When to Keep Traditional

    Stay with traditional if:

    • You deposit cash regularly
    • You value in-person relationships
    • You have complex banking needs (business, investments, mortgages)
    • You’re uncomfortable with online banking
    • You’re older and prefer human interaction

    But: Still consider online savings (even if you keep traditional checking)


    [Internal Link: Detailed comparison in “Online Banks vs Traditional Banks: Which Is Right for You?”]


    How to Choose the Right Accounts {#choose}

    Step-by-step framework to find your perfect banking setup.

    Step 1: Identify Your Priorities

    Rank these (1-5, 1=most important):

    ___ Interest rate (maximize earnings)
    ___ Zero fees (save money)
    ___ Branch access (in-person service)
    ___ Cash deposits (I handle cash)
    ___ ATM network (I withdraw cash frequently)
    ___ Features (budgeting tools, automation)
    ___ Customer service (phone support, help)
    ___ Simplicity (easy to understand/use)

    Your top 3 priorities determine which accounts fit.


    Step 2: Determine Your Banking Needs

    Checking needs:

    • Direct deposit? (Yes/No)
    • Need to deposit cash? (Yes/No)
    • Typical balance kept in checking: $_______
    • How often use ATMs: (Daily/Weekly/Rarely)
    • Prefer online or branch banking: (Online/Branch/Both)

    Savings needs:

    • Amount to save: $_______
    • Emergency fund or specific goal: (Emergency/Goal)
    • Need to access frequently: (Yes/No)
    • Current savings earning: _____% APY

    Step 3: Match Priorities to Accounts

    If your top priority is INTEREST:
    → Checking: SoFi (4.60% APY)
    → Savings: Marcus or Amex (5.30% APY)

    If your top priority is ZERO FEES:
    → Checking: Capital One 360 (no fees, no minimums)
    → Savings: Marcus or Ally (no fees, no minimums)

    If your top priority is BRANCH ACCESS:
    → Checking: Chase (4,700 branches, waive fee with $500 DD)
    → Savings: Online bank (even if keeping checking at branch bank)

    If your top priority is CASH DEPOSITS:
    → Checking: Chase or local bank/credit union
    → Savings: Online bank (transfer from checking to savings)

    If your top priority is ATM ACCESS:
    → Checking: Charles Schwab (unlimited worldwide reimbursement)
    → Savings: Any online bank (don’t need ATM for savings)

    If your top priority is FEATURES:
    → Checking: SoFi (vaults, early DD, investing integration)
    → Savings: Ally (buckets, boosters, automation)


    Step 4: Calculate Your Current Cost

    What you’re paying now:

    Checking:

    • Monthly fee: $/month × 12 = $/year
    • Overdraft fees (annual): $____
    • ATM fees (annual): $____
    • Total checking cost: $____/year

    Savings:

    • Monthly fee: $/month × 12 = $/year
    • Opportunity cost (interest you’re NOT earning):
      • Your balance: $______
      • Current rate: _____%
      • Potential rate (5.25%): 5.25%
      • Difference: _____%
      • Money left on table: $____/year
    • Total savings cost: $____/year

    Total banking cost: $____/year


    Step 5: Calculate Potential Savings

    Switching to recommended accounts:

    Example:

    • Current situation:
      • Checking: Chase ($12/month fee) = $144/year
      • Savings: $10,000 at 0.01% = $1/year
      • Cost: $143/year (fees minus minimal interest)
    • Recommended setup:
      • Checking: SoFi ($0 fees, 4.60% on $1,000 avg balance) = $46/year earned
      • Savings: Marcus ($10,000 at 5.30%) = $530/year
      • Benefit: $576/year earned
    • Difference: $719/year improvement

    Your calculation:

    • Current cost: -$____/year
    • New setup benefit: +$____/year
    • Total improvement: $____/year

    Step 6: Make Your Decision

    Recommended setups for different profiles:

    Profile A: Young professional, direct deposit, comfortable online

    • Checking: SoFi (4.60% APY, no fees)
    • Savings: Marcus (5.30% APY)
    • Result: Maximum interest, zero fees

    Profile B: Cash business owner, needs branch

    • Checking: Chase (waive fee with $500 DD or $1,500 balance)
    • Savings: Marcus or Amex online (5.30% APY)
    • Result: Branch access + high savings rate

    Profile C: Retiree, prefers simplicity, modest balances

    • Checking: Capital One 360 (simple, no fees)
    • Savings: Ally (easy to use, good rate)
    • Result: Simple setup, good returns

    Profile D: Frequent traveler

    • Checking: Charles Schwab (no foreign fees, unlimited ATM reimbursement)
    • Savings: Amex (5.30% APY, fast transfers)
    • Result: Travel-friendly + high interest

    Profile E: Student, first account

    • Checking: Capital One 360 or Discover (zero fees, cash back option)
    • Savings: Ally (buckets for organizing goals)
    • Result: Learn banking, no penalties for low balance

    Account Opening Checklist {#opening}

    Once you’ve chosen accounts, here’s how to open them efficiently.

    What You’ll Need

    Personal information:

    • Social Security number
    • Driver’s license or state ID
    • Date of birth
    • Physical address (not PO Box)
    • Email address
    • Phone number

    Funding source:

    • External bank account (routing + account number) OR
    • Debit card OR
    • Check (photo of check for mobile deposit)

    For joint accounts:

    • Both applicants’ information above
    • Relationship to other applicant

    Opening Process (Online Banks)

    Typical steps:

    1. Visit bank website
      • Click “Open Account”
      • Choose account type
    2. Personal information
      • Enter SSN, DOB, address
      • Contact information
    3. Identity verification
      • Upload ID photo (driver’s license)
      • Answer security questions
      • Sometimes video verification
    4. Initial deposit
      • Link external bank account OR
      • Transfer via debit card
      • Amount: $0-1,000+ depending on bank
    5. Review and submit
      • Read terms and conditions
      • Sign electronically
      • Submit application
    6. Approval
      • Instant to 2 business days
      • Usually instant for good credit/clean banking history
    7. Access account
      • Login credentials emailed
      • Set up app
      • Begin using

    Time: 10-20 minutes


    Opening Process (Traditional Banks)

    In-branch:

    1. Visit branch with ID and initial deposit
    2. Meet with banker
    3. Fill out application (paper or tablet)
    4. Receive temporary checks/debit card
    5. Time: 30-60 minutes

    Online (many traditional banks now allow):

    • Similar to online banks above
    • May require in-branch visit to complete

    Common Approval Issues

    Why applications get denied:

    • ChexSystems report (previous banking issues)
    • Outstanding negative balances at other banks
    • Fraud flags on identity
    • Incomplete application

    If denied:

    • Request reason (bank must provide)
    • Check ChexSystems report (free annually)
    • Resolve issues with previous banks
    • Try credit union (often more forgiving)
    • Consider “second chance” accounts (Chime, GoBank)

    After Approval

    Immediate steps:

    1. Set up direct deposit

    • Provide employer with routing/account number
    • Switch from old account to new

    2. Link external accounts

    • Connect old bank account
    • Transfer funds

    3. Set up automatic transfers

    • Checking to savings (monthly savings automation)
    • Emergency fund building

    4. Download mobile app

    • Enable biometric login
    • Set up alerts

    5. Order checks (if needed)

    • Some banks provide free
    • Others charge $20-40

    6. Update autopay accounts

    • Credit cards
    • Utilities
    • Subscriptions
    • Point to new account

    7. Keep old account open temporarily

    • Ensure all autopays switched
    • Close after 1-2 months
    • Avoid premature closure fees

    Multiple Accounts Strategy

    Why have multiple accounts:

    • FDIC coverage (each bank insured separately)
    • Separate purposes (emergency fund, short-term goals, vacation, etc.)
    • Maximize promotions (sign-up bonuses)

    Recommended structure:

    Account 1: Primary checking

    • SoFi or Capital One 360
    • Daily spending and bills

    Account 2: Emergency fund savings

    • Marcus or Amex
    • 3-6 months expenses
    • Touch only for emergencies

    Account 3: Short-term goals savings

    • Ally or Discover
    • Vacation, down payment, large purchases
    • Use buckets/separate accounts for each goal

    Account 4 (optional): Traditional bank

    • Chase or local credit union
    • Cash deposits if needed
    • Minimal balance

    Total accounts: 3-4 (manageable but organized)


    Maximizing Your Banking Benefits {#maximize}

    Get the most from your accounts.

    Automation Strategies

    Set up automatic transfers:

    1. Savings automation

    • Payday → checking (direct deposit)
    • Day after payday → savings (automatic transfer)
    • Example: Transfer $500 to Marcus savings every 1st of month

    2. Bill pay automation

    • Rent/mortgage: Auto-pay from checking
    • Utilities: Auto-pay
    • Credit cards: Auto-pay (full balance)
    • Reduces late fees, improves credit

    3. Round-up savings

    • If bank offers (SoFi, Ally, others)
    • Purchases rounded to nearest dollar
    • Difference goes to savings
    • Painless savings ($20-100/month)

    Interest Maximization

    For savings:

    1. Maintain high balances

    • Keep minimal balance in checking (enough for bills + buffer)
    • Transfer rest to high-yield savings
    • Example: Keep $2,000 in checking, $18,000 in savings

    2. Review rates quarterly

    • Banks change rates
    • If your bank drops significantly below competitors, switch
    • But don’t chase 0.05% differences (not worth hassle)

    3. Take advantage of promotional rates

    • Some banks offer 6% for first 3 months
    • Move money for promo, then to regular high-yield after

    For checking:

    • If account pays interest (SoFi, Upgrade), maintain higher balance
    • Calculate break-even:
      • SoFi: 4.60% on $10,000 = $460/year
      • Worth keeping higher balance vs. 0% checking

    Fee Avoidance

    Monthly fee waivers:

    • Set up direct deposit ($500+/month usually waives)
    • Maintain minimum balance (if you can)
    • Link accounts (some banks waive with multiple accounts)

    ATM fee avoidance:

    • Use in-network ATMs only
    • Choose bank with large network or reimbursement
    • Get cash back at stores (free)

    Overdraft fee avoidance:

    • Link checking to savings (overdraft protection)
    • Opt out of overdraft (transactions decline instead of fee)
    • Use low balance alerts (app notifications)
    • Banks eliminating overdraft: Ally, Discover, Capital One

    Foreign transaction fees:

    • Use cards with no foreign fees (Charles Schwab, Capital One)
    • Don’t use traditional banks abroad

    Security Best Practices

    Protect your accounts:

    1. Strong, unique passwords

    • Different password for each bank
    • Use password manager (1Password, LastPass)
    • Enable two-factor authentication

    2. Monitor regularly

    • Check accounts weekly minimum
    • Set up transaction alerts
    • Review monthly statements

    3. Freeze credit

    • Free at all three bureaus
    • Prevents fraudulent account opening
    • Unfreeze when you need to open account

    4. Never share credentials

    • Banks never ask for password
    • Beware phishing emails/calls
    • Only login via official app or website (not email links)

    5. Use official apps only

    • Download from App Store/Google Play
    • Verify developer is actual bank
    • Keep app updated

    Earning Bonuses

    Bank account bonuses:

    • Banks offer $200-500 to open accounts
    • Usually requires direct deposit
    • Must keep account open 6-12 months

    Strategy:

    1. Open account for bonus
    2. Meet requirements (direct deposit, maintain balance)
    3. Receive bonus (2-3 months usually)
    4. Keep account open required period
    5. Close or maintain if account is good

    Annual bonus potential: $500-1,000 (if you switch banks strategically)

    Track at: Doctor of Credit (website listing all bank bonuses)

    Caution: Don’t let bonus chasing compromise good banking (prioritize high rates and low fees over one-time bonuses)


    Banking Fees to Watch Out For {#fees}

    Knowledge is power. Here are fees to avoid.

    Most Common Fees

    1. Monthly maintenance fee: $0-15/month

    • How to avoid: Choose no-fee banks OR meet waiver requirements (direct deposit, minimum balance)

    2. Overdraft fee: $0-35 per transaction

    • How to avoid: Link checking to savings, opt out of overdraft, use banks with no overdraft fees

    3. ATM fee: $3-5 per transaction

    • How to avoid: Use in-network ATMs, choose bank with ATM reimbursement

    4. Minimum balance fee: $5-15/month

    • How to avoid: Maintain required balance OR choose banks with no minimum

    5. Paper statement fee: $2-5/month

    • How to avoid: Choose electronic statements (paperless)

    6. Wire transfer fee: $15-45 per transfer

    • How to avoid: Use ACH transfers instead (free), or choose bank with free wires

    7. Foreign transaction fee: 1-3% of transaction

    • How to avoid: Use banks with no foreign fees (Schwab, Capital One)

    8. Account closure fee: $25-50

    • How to avoid: Keep account open required time (usually 90-180 days)

    9. Returned deposit fee: $10-35

    • How to avoid: Don’t deposit bad checks, verify funds

    10. Excess withdrawal fee: $10 per transaction

    • How to avoid: Limit savings withdrawals to 6/month (federal regulation)

    Hidden Fees

    Watch out for:

    • Dormant account fee (charged if no activity for 12+ months)
    • Currency conversion fee (when traveling)
    • Check printing fee (some banks charge $20-50)
    • Stop payment fee ($20-35)
    • Expedited delivery fee (rush debit card)

    How Much Americans Waste on Fees

    Average American pays:

    • $329/year in bank fees (Bankrate, 2024)
    • Overdraft fees: $25/year average
    • ATM fees: $72/year average
    • Monthly maintenance: $144/year average

    With recommended accounts: $0-20/year

    Annual savings: $300+/year

    [Internal Link: Deep dive in “Banking Fees to Avoid: Save Hundreds on Hidden Charges”]


    FDIC Insurance Explained {#fdic}

    Your money’s safety net—understand it.

    What is FDIC Insurance?

    Federal Deposit Insurance Corporation:

    • Government agency
    • Insures deposits at member banks
    • Protects if bank fails
    • You don’t pay for this (banks pay premiums)

    Coverage Limits

    Standard coverage: $250,000 per depositor, per bank, per ownership category

    What this means:

    • Single account at Bank A: Insured up to $250,000
    • Single account at Bank B: Separately insured up to $250,000
    • Joint account at Bank A: Separately insured up to $250,000

    Ownership Categories

    Different categories = separate coverage:

    1. Single accounts (just you): $250,000
    2. Joint accounts (you + spouse): $250,000 per owner = $500,000 total
    3. Retirement accounts (IRA, 401k): $250,000
    4. Trust accounts: $250,000 per beneficiary
    5. Business accounts: $250,000

    Example:

    • You have $250,000 in individual savings
    • You have $500,000 in joint account with spouse (you + spouse each covered for $250,000)
    • Total FDIC coverage: $750,000 at one bank

    What If You Have More Than $250,000?

    Options:

    1. Use multiple banks

    • $250,000 at Marcus
    • $250,000 at Amex
    • $250,000 at Ally
    • Each separately insured

    2. Joint accounts

    • $500,000 in joint account with spouse (both covered)

    3. Different ownership categories

    • $250,000 individual
    • $250,000 in IRA
    • Both at same bank = $500,000 coverage

    4. CDARS program

    • Certificate of Deposit Account Registry Service
    • Automatically spreads deposits across multiple banks
    • All FDIC insured
    • One relationship, multiple banks

    5. IntraFi Network Deposits

    • Similar to CDARS
    • For savings accounts
    • Spreads across network

    How to Verify FDIC Insurance

    Check:

    1. Bank website (should prominently display “Member FDIC”)
    2. FDIC BankFind tool (FDIC.gov/resources/deposit-insurance)
    3. Look for FDIC sign at branch
    4. Check account statements (should mention FDIC)

    All recommended banks in this guide are FDIC insured (we verified)

    Credit Union Alternative: NCUA

    Credit unions insured by:

    • National Credit Union Administration (NCUA)
    • Same $250,000 coverage
    • Equivalent to FDIC (equally safe)

    What Happens If Bank Fails?

    FDIC process:

    1. Bank declared failed (by regulators)
    2. FDIC takes over (same day, usually Friday)
    3. FDIC finds buyer bank OR pays depositors directly
    4. Access to funds restored (usually next business day)
    5. Accounts transferred to new bank OR check mailed

    You do nothing. FDIC handles everything.

    Historical data:

    • FDIC created 1933
    • Since then: 0 depositors have lost insured funds
    • Your money is safe (up to limits)

    When to Switch Banks {#switch}

    Knowing when to move your money.

    Signs It’s Time to Switch

    1. Your savings account earns less than 4.5% APY

    • High-yield savings offering 5%+
    • You’re leaving money on table

    2. You’re paying monthly fees

    • $12-15/month = $144-180/year wasted
    • No-fee accounts widely available

    3. You’re getting hit with overdraft fees regularly

    • Some banks have eliminated these
    • Or link to savings for protection

    4. Poor customer service

    • Can’t reach anyone
    • Issues unresolved
    • Frustrating experience

    5. Lack of features you want

    • Want mobile check deposit (your bank doesn’t offer)
    • Want budgeting tools
    • Want better app

    6. You’ve moved and no longer near branches

    • Had traditional bank, moved away
    • Switch to online bank or local option

    7. Better sign-up bonuses available

    • Banks offering $200-500 to switch
    • If you meet requirements easily, worth it

    How to Switch Banks Smoothly

    Timeline: 4-6 weeks for full switch

    Week 1: Research and open new account

    • Choose new bank (using this guide)
    • Open accounts
    • Fund with small amount

    Week 2: Set up new account

    • Link external accounts
    • Download app
    • Test features

    Week 3: Switch direct deposit

    • Provide employer new routing/account numbers
    • Usually takes 1-2 pay cycles

    Week 4: Switch autopay

    • List all autopay accounts
    • Update each one to new account
    • Keep list (ensure nothing missed)

    Week 5: Monitor both accounts

    • Ensure all autopays switched
    • Watch for any transactions at old account

    Week 6: Close old account

    • Withdraw remaining funds
    • Call bank to close (or visit branch)
    • Get written confirmation
    • Keep for records

    Switching Checklist

    Before switching:

    •  Research new bank
    •  Verify FDIC insurance
    •  Read terms and conditions
    •  Check for account closing fees at current bank

    Opening new account:

    •  Open new checking
    •  Open new savings
    •  Transfer small amount to test
    •  Set up online access
    •  Download mobile app

    Switching payments:

    •  Update direct deposit
    •  List all autopay accounts:
      •  Credit cards
      •  Utilities
      •  Subscriptions
      •  Insurance
      •  Loans
    •  Update each autopay

    Closing old account:

    •  Verify all autopays switched
    •  Monitor old account for 2 weeks
    •  Withdraw all funds
    •  Request account closure
    •  Get confirmation in writing
    •  Verify closure after 2 weeks

    Don’t Make These Switching Mistakes

    Mistake #1: Closing old account too soon

    • Close before all autopays switched
    • Missed payment, late fee
    • Wait 2-4 weeks after last switch

    Mistake #2: Forgetting about automatic deposits

    • Tax refund sent to old account
    • Paycheck to old account
    • Update all incoming AND outgoing

    Mistake #3: Not keeping records

    • Close account without confirmation
    • Bank claims you owe fees
    • Get written closure confirmation

    Mistake #4: Leaving small balance

    • $3 left in account
    • Monthly fee charged
    • Account overdrafted
    • Withdraw everything or close account

    Mistake #5: Switching during big purchase

    • Mortgage application pending
    • Banks verify accounts
    • Don’t switch mid-application
    • Wait until major transactions complete

    Frequently Asked Questions {#faq}

    Q: Can I have multiple bank accounts?

    A: Absolutely. In fact, it’s recommended. Most people should have:

    • 1 checking account (daily spending)
    • 1 high-yield savings (emergency fund)
    • 1-2 additional savings (specific goals)

    Each bank insured separately by FDIC, so multiple accounts = more protection.


    Q: What’s the difference between APY and interest rate?

    A: APY (Annual Percentage Yield) includes compound interest. Interest rate doesn’t.

    Example:

    • 5.00% interest rate, compounded daily = 5.13% APY
    • Always compare APY (not just interest rate) when choosing accounts

    Q: How often do banks change their rates?

    A: Savings account rates can change anytime (variable rate). Banks typically change when Federal Reserve changes rates.

    Recent trend:

    • 2020-2021: Rates fell (Fed lowered rates during pandemic)
    • 2022-2023: Rates rose dramatically (Fed raised rates to fight inflation)
    • 2024-2025: Rates holding steady or slight decreases

    Watch rates quarterly. If your bank drops significantly below competitors, consider switching.


    Q: Is my money safe at online banks?

    A: Yes, if FDIC insured. Online banks are just as safe as traditional banks (same FDIC coverage).

    All recommended banks in this guide are FDIC insured. Your deposits protected up to $250,000 per depositor, per bank.


    Q: How do I deposit cash at an online bank?

    A: This is online banks’ main limitation. Options:

    1. Keep traditional bank account for cash deposits, transfer to online bank
    2. Use retail partners (some online banks partner with CVS, Walgreens for deposits)
    3. Money orders (buy with cash, deposit via mobile check deposit)
    4. Friend/family (they deposit to their account, transfer to you)

    Reality: Most people in 2025 don’t deposit cash often (direct deposit, checks). If you do regularly, keep traditional bank for this.


    Q: Can I open a bank account if I have bad credit?

    A: Yes. Banks check ChexSystems (banking history), not credit score, for checking/savings accounts.

    Bad credit won’t prevent account opening. But negative banking history (unpaid fees, fraud) might.

    If denied:

    • Request ChexSystems report (free annually)
    • Resolve issues with previous banks
    • Try credit unions (more forgiving)
    • Consider “second chance” accounts (Chime, GoBank)

    Q: What’s a good amount to keep in checking vs. savings?

    A: Checking: 1-2 months of expenses + buffer

    • Enough to cover bills
    • Plus $500-1,000 cushion
    • Rest should be in high-yield savings (earning interest)

    Savings: 3-6 months of expenses (emergency fund) + goal savings

    Example:

    • Monthly expenses: $3,000
    • Keep in checking: $4,000 ($3,000 + $1,000 buffer)
    • Emergency fund savings: $18,000 (6 months)
    • Goal savings: Variable (vacation, down payment, etc.)

    Q: Should I close my old bank account when switching?

    A: Not immediately. Timeline:

    1. Open new account
    2. Switch direct deposit and autopay (3-4 weeks)
    3. Monitor both accounts (2 weeks)
    4. Then close old account

    Closing too soon = risk missed autopay, late fees.

    Some people keep old account open (minimal balance) as backup. This is fine if no monthly fee.


    Q: What if I need more than $250,000 FDIC coverage?

    A: Strategies:

    1. Multiple banks: $250k at each bank, each insured separately
    2. Joint account: You + spouse = $500k coverage at one bank
    3. Different ownership categories: $250k individual + $250k IRA = $500k at one bank
    4. CDARS or IntraFi: Programs that spread deposits across multiple banks automatically

    Q: Can I earn 5% interest forever?

    A: No. Current high rates (5%+) are due to Federal Reserve policy (high fed funds rate). When Fed lowers rates (likely 2025-2026), savings rates will drop.

    Enjoy high rates while they last, but expect eventual decrease to 2-3% range (still much better than 0.01%).


    Q: Are credit unions better than banks?

    A: Not necessarily better, just different.

    Credit unions:

    • Member-owned (not-for-profit)
    • Often better customer service
    • Sometimes higher savings rates
    • Sometimes lower loan rates
    • Must qualify for membership

    Banks:

    • For-profit
    • Often better technology
    • Larger ATM networks (usually)
    • No membership requirement

    Best credit unions (rates/service) compete with best banks. Worth comparing both.


    Q: What happens to my direct deposit if I switch banks?

    A: You provide employer new routing/account numbers. They update payroll system. Usually takes 1-2 pay cycles to process.

    Timeline:

    • Submit new info: Week 1
    • Next paycheck: Might still go to old account
    • Following paycheck: Should go to new account

    Keep old account open until verify direct deposit working at new bank.


    Q: Can I have a joint account with someone I’m not married to?

    A: Yes. Joint accounts can be with:

    • Spouse
    • Partner
    • Parent/child
    • Sibling
    • Friend
    • Business partner

    Both parties have full access to funds. Both responsible for overdrafts. Consider carefully before opening joint account (trust required).


    Conclusion {#conclusion}

    Banking doesn’t have to be complicated, but it shouldn’t be ignored. The difference between optimized banking and default banking is $500-2,000/year for the average household.

    The simple truth:

    • Traditional big bank savings: 0.01% APY, $12/month fees
    • Optimized setup: 5.00%+ APY, $0 fees

    On $20,000 saved over 10 years:

    • Traditional bank: Earn $20, pay $1,440 fees = -$1,420
    • High-yield savings: Earn $10,500+, pay $0 fees = +$10,500

    Difference: $11,920 for a few hours of effort (switching banks).


    Your action plan:

    This week:

    1. ✅ Review current accounts (fees, interest rates)
    2. ✅ Calculate what you’re paying/losing annually
    3. ✅ Choose new accounts from this guide (checking + savings minimum)

    Next week:

    1. ✅ Open new accounts (30 minutes online)
    2. ✅ Fund with initial transfer
    3. ✅ Set up mobile apps

    Following 2-4 weeks:

    1. ✅ Switch direct deposit
    2. ✅ Update all autopay accounts
    3. ✅ Monitor both old and new accounts

    Week 6:

    1. ✅ Close old accounts (if no longer needed)
    2. ✅ Set up automatic savings transfers
    3. ✅ Enjoy higher interest, zero fees

    The bottom line on best accounts:

    Best checking: SoFi (4.60% APY, zero fees, great features)
    Best savings: Marcus or Amex (5.30% APY, zero fees, FDIC insured)
    Best money market: Sallie Mae (5.25% APY, ATM card, checks)
    Best for cash deposits: Chase (waive $12 fee with $500 DD)
    Best for travelers: Charles Schwab (unlimited ATM reimbursement worldwide)

    Can’t decide?

    • Start with Marcus savings (universally excellent)
    • Add SoFi checking (if comfortable online) OR Capital One 360 (if you want simple)
    • Evaluate after 3 months, adjust if needed

    Remember: Banking is not “set it and forget it.” Review annually:

    • Are rates still competitive?
    • Any new fees?
    • Better options available?
    • Life changes requiring different accounts?

    But don’t overcomplicate.

    • 2-3 accounts is sufficient for most people
    • Prioritize high rates and zero fees
    • Use automation (make it effortless)

    Your money works for you 24/7. Make sure your bank does too.

    The opportunity to earn 5%+ on savings while paying zero fees has never been better. This won’t last forever. The time to optimize your banking is now.

    Take action this week. Your future self (and bank account) will thank you.


    Related Articles

    Build on this foundation: